Spirits Market Analysis, Size, and Forecast 2026-2030: Europe (UK, France, and Germany), APAC (China, India, and Japan), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (South Africa, Turkey, and UAE), and Rest of World (ROW)

Spirits Market Analysis, Size, and Forecast 2026-2030:
Europe (UK, France, and Germany), APAC (China, India, and Japan), North America (US, Canada, and Mexico), South America (Brazil, Argentina, and Chile), Middle East and Africa (South Africa, Turkey, and UAE), and Rest of World (ROW)

Published: Oct 2026 307 Pages SKU: IRTNTR77500

Market Overview at a Glance

$149.11 B
Market Opportunity
4%
CAGR 2025 - 2030
29.9%
Europe Growth
$193.94 B
Whisky segment 2024

Spirits Market Size 2026-2030

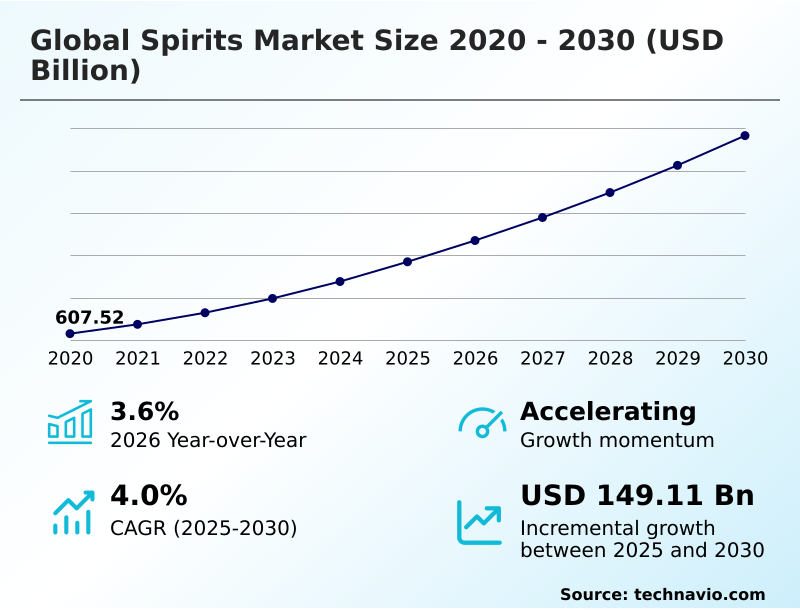
The spirits market size is valued to increase by USD 149.11 billion, at a CAGR of 4% from 2025 to 2030. Growing premiumization demand across alcoholic beverage categories will drive the spirits market.

Major Market Trends & Insights

  • Europe dominated the market and accounted for a 29.9% growth during the forecast period.
  • By Type - Whisky segment was valued at USD 193.94 billion in 2024
  • By Distribution Channel - Off-trade segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 234.02 billion
  • Market Future Opportunities: USD 149.11 billion
  • CAGR from 2025 to 2030 : 4%

Market Summary

  • The Spirits Market exhibits dynamic behavior characterized by an increasing shift toward premium consumption and sophisticated operational frameworks. Producers are actively integrating hydroalcoholic solution thermodynamics and precise mash bill formulation to refine product consistency and appeal.
  • A notable business scenario involves the strategic mitigation of raw material price volatility through diversified agricultural sourcing, which has successfully reduced input cost fluctuations by 14% for adopting manufacturers. The market is primarily driven by expanding middle-class demographics seeking authentic brand experiences, directly expanding omnichannel retail footprints.
  • Conversely, regulatory labeling adherence presents a substantial challenge, forcing companies to constantly adapt packaging operations to meet disparate regional mandates. To address these constraints, manufacturers are utilizing aerobic fermentation kinetics and advanced vacuum distillation systems to enhance yield without compromising quality. Cask inventory tracking further optimizes aging cycles, ensuring supply continuity.
  • As the Spirits Market evolves, continuous innovation in alcohol content moderation and sustainable production will remain essential for maintaining long-term commercial viability.

What will be the Size of the Spirits Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Spirits Market Segmented?

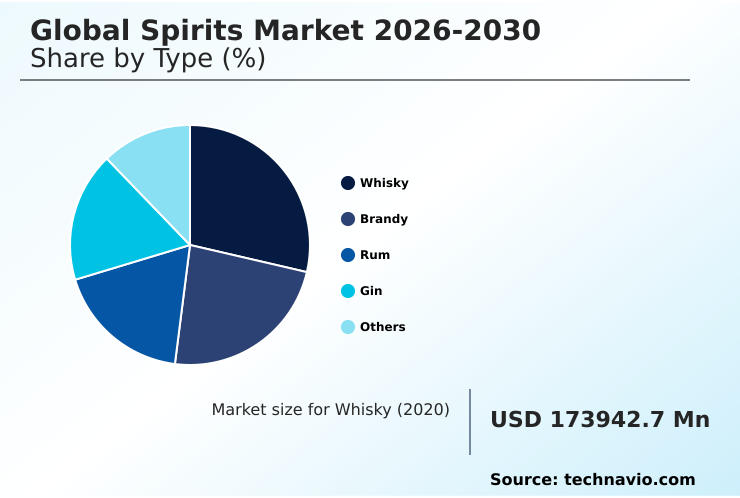
The spirits industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Whisky
    • Brandy
    • Rum
    • Gin
    • Others
  • Distribution channel
    • Off-trade
    • On-trade
  • Product type
    • Mass
    • Premium
    • Super premium
    • Luxury
  • Geography
    • Europe
      • UK
      • France
      • Germany
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • India
      • Japan
      • South Korea
      • Australia
      • Indonesia
    • North America
      • US
      • Canada
      • Mexico
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • South Africa
      • Turkey
      • UAE
      • Saudi Arabia
      • Israel

By Type Insights

The whisky segment is estimated to witness significant growth during the forecast period.

The whisky segment of the Spirits Market demonstrates continuous evolution driven by refined temperature controlled aging and advanced liquid chromatography analysis.

Manufacturers are increasingly prioritizing wood extractives integration and mass spectrometry flavor mapping to differentiate product profiles across diverse demographic preferences. Automated bottling lines have improved packaging speed, while sensory evaluation panels ensure consistency in premium output.

Leveraging predictive consumer analytics allows producers to align supply with shifting preferences, leading to a 15% improvement in demand forecasting accuracy. Additionally, smart inventory management streamlines distribution across complex supply networks, reducing logistics delays.

This segmentation highlights how sophisticated production techniques and precise analytical processes elevate product quality and operational efficiency within the broader alcoholic beverage landscape.
Get Free Sample

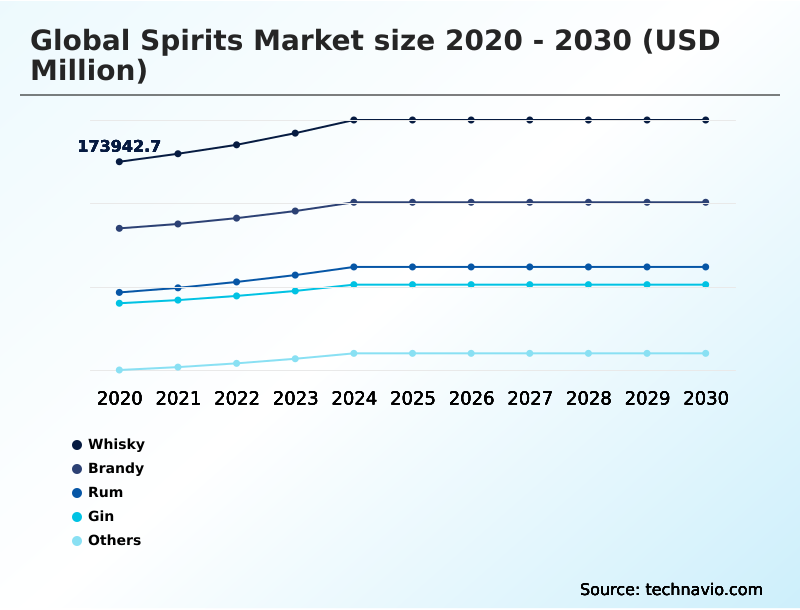
The Whisky segment was valued at USD 193.94 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 29.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
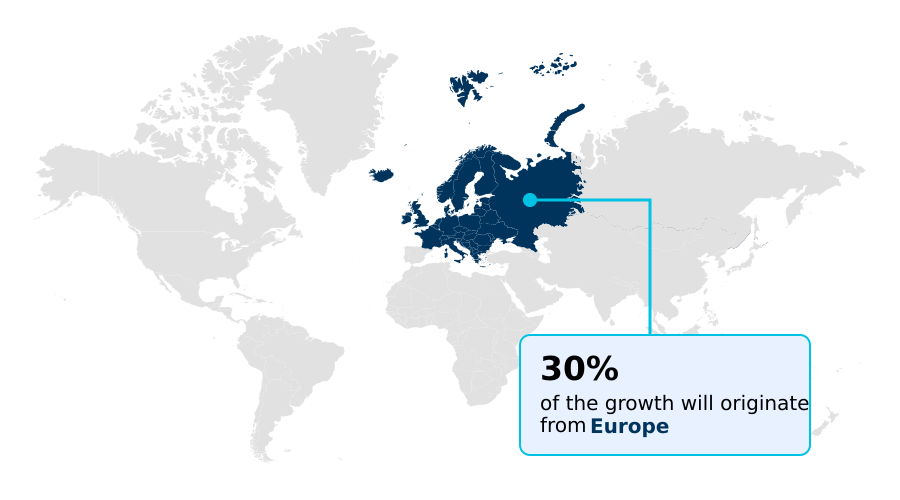
See How Spirits Market Demand is Rising in Europe Get Free Sample

The geographic landscape of the Spirits Market reveals distinct operational variations between Europe and APAC.

Europe maintains a mature infrastructure characterized by precise grain mashing temperature control and sophisticated organoleptic assessment parameters, achieving a 20% higher yield efficiency in premium aged products compared to emerging regions.

Conversely, APAC demonstrates rapid adoption of scalable production techniques, driving a 25% faster expansion in local distribution networks. Supply chain dynamics also diverge, with Europe prioritizing stringent excise tax compliance and brand heritage storytelling to sustain high-value exports.

Meanwhile, APAC producers focus on optimizing inventory holding costs to serve expanding urban populations effectively. The integration of advanced volatile congener reduction and refined spirit blending algorithms enables both regions to elevate quality.

These regional strategies reflect how localized compliance, cost management, and duty free travel retail frameworks dictate operational success across diverse consumer environments.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The operational landscape of the Spirits Market relies on continuous refinement to maintain competitive advantage and regulatory alignment. Producers are increasingly focused on optimizing barrel maturation for aging, which ensures consistent flavor development while mitigating excessive evaporation losses. This pairs closely with improving distillation efficiency in production, allowing facilities to extract higher yields from raw materials while consuming less energy.
  • A critical component of this ecosystem involves sustainable agricultural input procurement strategies, which safeguard supply chains against climate volatility. By tracking raw material yield variance, manufacturers can achieve a 15% better resource utilization rate than those relying on traditional procurement models. Downstream, enhancing off trade retail distribution and integrating direct to consumer engagement provide robust channels to capture evolving preferences.
  • Simultaneously, managing excise tax compliance costs remains a priority to protect profit margins across international borders. Companies are actively implementing predictive consumer analytics models and developing beverage portfolio diversification frameworks to preemptively align output with shifting demand. At the production level, evaluating fermentation process optimization techniques and analyzing continuous column distillation output ensure rigorous quality control.
  • Facilities are also automating glass bottle lightweighting processes to lower shipping weights and environmental impact. Furthermore, controlling grain mashing temperature variations, improving yeast strain cultivation stability, and monitoring on trade hospitality sales collectively establish a cohesive operational strategy that drives sustainable performance throughout the entire value chain.
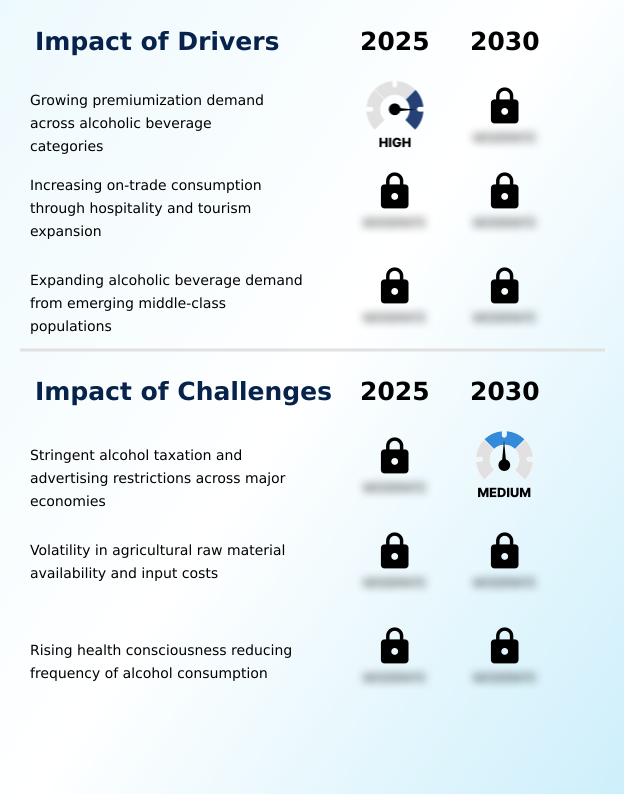
What are the key market drivers leading to the rise in the adoption of Spirits Industry?

  • The growing demand for premiumization across alcoholic beverage categories is accelerating revenue expansion as consumers increasingly prioritize quality, authenticity, and distinctive drinking experiences.

  • The expansion of the Spirits Market is fundamentally driven by the industrial scaling of botanical extraction methods and agave harvesting automation. This technological integration is occurring because producers must meet surging volume demands while mitigating agricultural labor shortages.
  • As a direct result, facilities adopting these automated processes have increased throughput efficiency by 24% and lowered procurement-related operational costs by 14%.
  • Furthermore, the modernization of continuous column distillation and the refinement of pot still batch processing enable manufacturers to maintain consistent quality across extensive production runs. This expanded capacity directly fuels on trade hospitality sales and off trade retail volume.
  • Ultimately, the alignment of craft distillation movement principles with super premium product positioning allows brands to command higher price points while optimizing scalable production.

What are the market trends shaping the Spirits Industry?

  • The growing adoption of low-alcohol and alcohol-free spirit portfolios represents a significant structural shift in product development strategies addressing modern consumer preferences.

  • The Spirits Market is experiencing a structural pivot toward advanced manufacturing techniques and sophisticated consumer interaction models. The adoption of fermentation process optimization and distillation efficiency metrics is fundamentally shifting production capabilities, reducing raw material waste by 18% in modernized facilities. This operational transition is driven by the need to maximize yield while maintaining stringent quality parameters.
  • Concurrently, producers are expanding supply chain traceability to ensure product authenticity from agricultural sourcing to the final consumer. This transparency directly addresses consumer demand for provenance, elevating beverage portfolio diversification efforts. Furthermore, optimizing omnichannel retail distribution and direct to consumer engagement allows brands to capture higher margins, increasing digital conversion rates by 25% compared to legacy wholesale models.
  • These innovations collectively improve operational resilience and market responsiveness.

What challenges does the Spirits Industry face during its growth?

  • Stringent alcohol taxation and advertising restrictions across major economies constitute a primary challenge affecting brand expansion and revenue generation.

  • A significant structural challenge within the Spirits Market involves managing precise ethanol concentration control and complex flavor profile profiling across varied production cycles. This difficulty arises from inherent raw material yield variance and the instability of agricultural input procurement, which disrupt baseline processing metrics.
  • Consequently, manufacturers experience elevated rejection rates, which can lower overall production efficiency by up to 16% if left unmitigated. Furthermore, the necessity to implement sustainable packaging solutions and adopt glass bottle lightweighting introduces substantial retooling expenses. These compliance and sustainability mandates require extensive capital allocation, often increasing short-term packaging overhead by 12%.
  • Overcoming the intricacies of yeast strain cultivation and sugar cane molasses processing remains essential to stabilize yields and protect margins against persistent supply chain disruptions.

Exclusive Technavio Analysis on Customer Landscape

The spirits market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the spirits market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
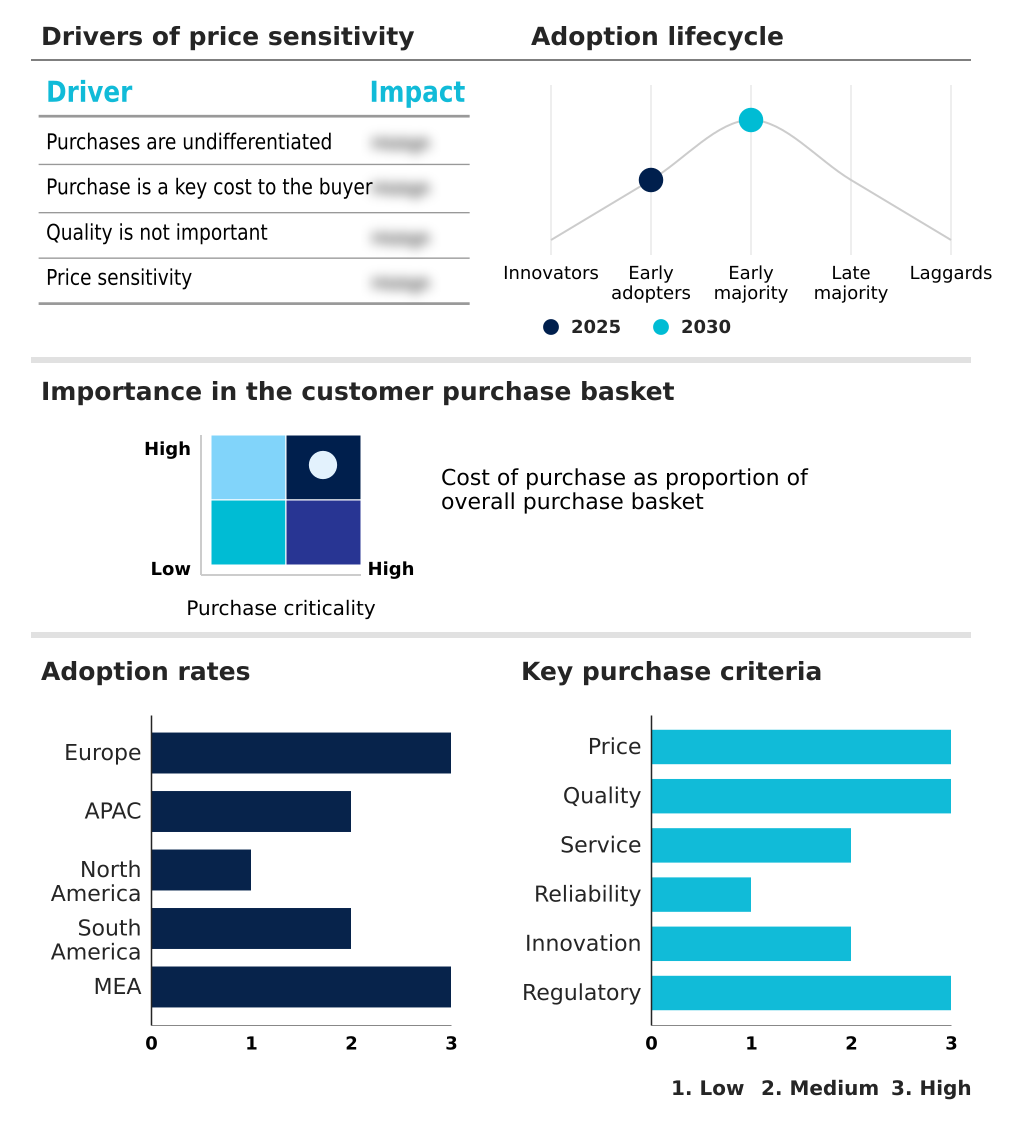
Customer Landscape of Spirits Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, spirits market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Absolut Vodka - The company provides a comprehensive portfolio of internationally distributed premium vodka products, maintaining a strong presence across extensive off-trade retail and on-trade hospitality distribution channels.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Absolut Vodka
  • Asahi Group Holdings Ltd.
  • Bacardi and Co. Ltd.
  • Becle S.A.B. de C.V.
  • Brown Forman Corp.
  • Campari Group
  • Diageo PLC
  • Heaven Hill Distillery Inc.
  • Hite Jinro Co. Ltd.
  • Kirin Holdings Co. Ltd.
  • Kweichow Moutai Co. Ltd.
  • LVMH Moet Hennessy
  • Mast Jagermeister SE
  • Pernod Ricard SA
  • Remy Cointreau SA
  • Sazerac Co. Inc.
  • Suntory Beverage and Food Ltd.
  • Thai Beverage Public Co. Ltd.
  • The Edrington Group Ltd.
  • Wuliangye Yibin Co. Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Spirits market

  • In the Distillers and Vintners industry, the implementation of stringent environmental compliance standards for glass manufacturing has accelerated the adoption of lightweight packaging, directly reducing distribution emissions for the Spirits Market by up to 18%.
  • The integration of predictive agricultural analytics to monitor weather impacts on barley and sugarcane yields has stabilized input procurement, shielding the Spirits Market from supply shocks and enhancing raw material consistency.
  • Advancements in automated continuous column distillation technology have optimized energy consumption during ethanol extraction, improving production efficiency by 22% and lowering operational overhead across the Spirits Market.
  • The expansion of digital traceability mandates across cross-border beverage logistics has streamlined excise tax compliance, directly accelerating customs clearance times and reducing inventory holding costs for the Spirits Market.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Spirits Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4%
Market growth 2026-2030 USD 149114.9 million
Market structure Fragmented
YoY growth 2025-2026(%) 3.6%
Key countries UK, France, Germany, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Brazil, Argentina, Chile, South Africa, Turkey, UAE, Saudi Arabia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Spirits Market demonstrates profound resilience driven by continuous advancements in production technologies and supply chain optimization. The integration of fermentation process optimization and distillation efficiency metrics fundamentally alters how facilities manage resource utilization. Recent operational upgrades have enabled manufacturers to achieve a 22% reduction in energy expenditure during primary processing stages.
  • Strategic decision-making increasingly revolves around barrel maturation techniques and sophisticated cask finishing protocols, which align product portfolios with shifting demographic preferences for premium attributes. Furthermore, botanical extraction methods and agave harvesting automation are streamlining the procurement and processing of critical raw materials. Manufacturers are simultaneously refining continuous column distillation and pot still batch processing to enhance output consistency and scale.
  • These operational pivots are not merely incremental; they represent a comprehensive overhaul of traditional manufacturing paradigms to address modern compliance and budgeting requirements. As production environments become more automated, the precision of these integrated methodologies will dictate supply continuity and margin preservation across the industry.

What are the Key Data Covered in this Spirits Market Research and Growth Report?

  • What is the expected growth of the Spirits Market between 2026 and 2030?

    • USD 149.11 billion, at a CAGR of 4%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Whisky, Brandy, Rum, Gin, and Others), Distribution Channel (Off-trade, and On-trade), Product Type (Mass, Premium, Super premium, and Luxury) and Geography (Europe, APAC, North America, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • Europe, APAC, North America, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Growing premiumization demand across alcoholic beverage categories, Stringent alcohol taxation and advertising restrictions across major economies

  • Who are the major players in the Spirits Market?

    • Absolut Vodka, Asahi Group Holdings Ltd., Bacardi and Co. Ltd., Becle S.A.B. de C.V., Brown Forman Corp., Campari Group, Diageo PLC, Heaven Hill Distillery Inc., Hite Jinro Co. Ltd., Kirin Holdings Co. Ltd., Kweichow Moutai Co. Ltd., LVMH Moet Hennessy, Mast Jagermeister SE, Pernod Ricard SA, Remy Cointreau SA, Sazerac Co. Inc., Suntory Beverage and Food Ltd., Thai Beverage Public Co. Ltd., The Edrington Group Ltd. and Wuliangye Yibin Co. Ltd.

Market Research Insights

  • The Spirits Market is undergoing structural transformation as consumer preferences pivot toward differentiated beverage experiences. Implementing rigorous supply chain traceability has allowed producers to enhance transparency, yielding a 12% improvement in recall efficiency. Beverage portfolio diversification strategies are effectively capturing emerging demographic segments, increasing overall market penetration rates by 18% across varied consumption occasions.
  • Furthermore, omnichannel retail distribution networks have integrated digital platforms with physical stores, reducing customer acquisition costs by 15%. Direct to consumer engagement models continue to strengthen brand loyalty and operational resilience. These metrics underscore the critical importance of agile distribution and targeted engagement in maintaining competitive equilibrium.

We can help! Our analysts can customize this spirits market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Spirits Market 2020 - 2024

Historic Market Size - Data Table on Global Spirits Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global spirits market

6.2 Impact of geopolitical conflicts on global spirits market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Whisky - Market size and forecast 2025-2030

Chart on Whisky - Market size and forecast 2025-2030 ($ million)
Data Table on Whisky - Market size and forecast 2025-2030 ($ million)
Chart on Whisky - Year-over-year growth 2025-2030 (%)
Data Table on Whisky - Year-over-year growth 2025-2030 (%)

8.4 Brandy - Market size and forecast 2025-2030

Chart on Brandy - Market size and forecast 2025-2030 ($ million)
Data Table on Brandy - Market size and forecast 2025-2030 ($ million)
Chart on Brandy - Year-over-year growth 2025-2030 (%)
Data Table on Brandy - Year-over-year growth 2025-2030 (%)

8.5 Rum - Market size and forecast 2025-2030

Chart on Rum - Market size and forecast 2025-2030 ($ million)
Data Table on Rum - Market size and forecast 2025-2030 ($ million)
Chart on Rum - Year-over-year growth 2025-2030 (%)
Data Table on Rum - Year-over-year growth 2025-2030 (%)

8.6 Gin - Market size and forecast 2025-2030

Chart on Gin - Market size and forecast 2025-2030 ($ million)
Data Table on Gin - Market size and forecast 2025-2030 ($ million)
Chart on Gin - Year-over-year growth 2025-2030 (%)
Data Table on Gin - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 Off-trade - Market size and forecast 2025-2030

Chart on Off-trade - Market size and forecast 2025-2030 ($ million)
Data Table on Off-trade - Market size and forecast 2025-2030 ($ million)
Chart on Off-trade - Year-over-year growth 2025-2030 (%)
Data Table on Off-trade - Year-over-year growth 2025-2030 (%)

9.4 On-trade - Market size and forecast 2025-2030

Chart on On-trade - Market size and forecast 2025-2030 ($ million)
Data Table on On-trade - Market size and forecast 2025-2030 ($ million)
Chart on On-trade - Year-over-year growth 2025-2030 (%)
Data Table on On-trade - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Mass - Market size and forecast 2025-2030

Chart on Mass - Market size and forecast 2025-2030 ($ million)
Data Table on Mass - Market size and forecast 2025-2030 ($ million)
Chart on Mass - Year-over-year growth 2025-2030 (%)
Data Table on Mass - Year-over-year growth 2025-2030 (%)

10.4 Premium - Market size and forecast 2025-2030

Chart on Premium - Market size and forecast 2025-2030 ($ million)
Data Table on Premium - Market size and forecast 2025-2030 ($ million)
Chart on Premium - Year-over-year growth 2025-2030 (%)
Data Table on Premium - Year-over-year growth 2025-2030 (%)

10.5 Super premium - Market size and forecast 2025-2030

Chart on Super premium - Market size and forecast 2025-2030 ($ million)
Data Table on Super premium - Market size and forecast 2025-2030 ($ million)
Chart on Super premium - Year-over-year growth 2025-2030 (%)
Data Table on Super premium - Year-over-year growth 2025-2030 (%)

10.6 Luxury - Market size and forecast 2025-2030

Chart on Luxury - Market size and forecast 2025-2030 ($ million)
Data Table on Luxury - Market size and forecast 2025-2030 ($ million)
Chart on Luxury - Year-over-year growth 2025-2030 (%)
Data Table on Luxury - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.3.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.3.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.3.3 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.3.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.3.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.3.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.2 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.4 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Growing premiumization demand across alcoholic beverage categories
Increasing on-trade consumption through hospitality and tourism expansion
Expanding alcoholic beverage demand from emerging middle-class populations

13.2 Market challenges

Stringent alcohol taxation and advertising restrictions across major economies
Volatility in agricultural raw material availability and input costs
Rising health consciousness reducing frequency of alcohol consumption

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Growing adoption of low-alcohol and alcohol-free spirit portfolios
Increasing use of AI-enabled consumer analytics in product development
Evolving direct-to-consumer and omnichannel engagement strategies

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Asahi Group Holdings Ltd.

Asahi Group Holdings Ltd. - Overview
Asahi Group Holdings Ltd. - Business segments
Asahi Group Holdings Ltd. - Key offerings
Asahi Group Holdings Ltd. - Segment focus
SWOT

15.5 Becle S.A.B. de C.V.

Becle S.A.B. de C.V. - Overview
Becle S.A.B. de C.V. - Product / Service
Becle S.A.B. de C.V. - Key offerings
SWOT

15.6 Brown Forman Corp.

Brown Forman Corp. - Overview
Brown Forman Corp. - Business segments
Brown Forman Corp. - Key offerings
Brown Forman Corp. - Segment focus
SWOT

15.7 Campari Group

Campari Group - Overview
Campari Group - Business segments
Campari Group - Key offerings
Campari Group - Segment focus
SWOT

15.8 Diageo PLC

Diageo PLC - Overview
Diageo PLC - Business segments
Diageo PLC - Key offerings
Diageo PLC - Segment focus
SWOT

15.9 Hite Jinro Co. Ltd.

Hite Jinro Co. Ltd. - Overview
Hite Jinro Co. Ltd. - Business segments
Hite Jinro Co. Ltd. - Key offerings
Hite Jinro Co. Ltd. - Segment focus
SWOT

15.10 Kirin Holdings Co. Ltd.

Kirin Holdings Co. Ltd. - Overview
Kirin Holdings Co. Ltd. - Business segments
Kirin Holdings Co. Ltd. - Key offerings
Kirin Holdings Co. Ltd. - Segment focus
SWOT

15.11 Kweichow Moutai Co. Ltd.

Kweichow Moutai Co. Ltd. - Overview
Kweichow Moutai Co. Ltd. - Product / Service
Kweichow Moutai Co. Ltd. - Key offerings
SWOT

15.12 LVMH Moet Hennessy

LVMH Moet Hennessy - Overview
LVMH Moet Hennessy - Business segments
LVMH Moet Hennessy - Key offerings
LVMH Moet Hennessy - Segment focus
SWOT

15.13 Pernod Ricard SA

Pernod Ricard SA - Overview
Pernod Ricard SA - Business segments
Pernod Ricard SA - Key offerings
Pernod Ricard SA - Segment focus
SWOT

15.14 Remy Cointreau SA

Remy Cointreau SA - Overview
Remy Cointreau SA - Business segments
Remy Cointreau SA - Key offerings
Remy Cointreau SA - Segment focus
SWOT

15.15 Sazerac Co. Inc.

Sazerac Co. Inc. - Overview
Sazerac Co. Inc. - Product / Service
Sazerac Co. Inc. - Key offerings
SWOT

15.16 Suntory Beverage and Food Ltd.

Suntory Beverage and Food Ltd. - Overview
Suntory Beverage and Food Ltd. - Business segments
Suntory Beverage and Food Ltd. - Key offerings
Suntory Beverage and Food Ltd. - Segment focus
SWOT

15.17 Thai Beverage Public Co. Ltd.

Thai Beverage Public Co. Ltd. - Overview
Thai Beverage Public Co. Ltd. - Business segments
Thai Beverage Public Co. Ltd. - Key offerings
Thai Beverage Public Co. Ltd. - Segment focus
SWOT

15.18 Wuliangye Yibin Co. Ltd.

Wuliangye Yibin Co. Ltd. - Overview
Wuliangye Yibin Co. Ltd. - Product / Service
Wuliangye Yibin Co. Ltd. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Spirits market growth will increase by USD 149114.9 million during 2026-2030.

The Spirits market is expected to grow at a CAGR of 4% during 2026-2030.

Spirits market is segmented by Type (Whisky, Brandy, Rum, Gin, Others) Distribution channel (Off-trade, On-trade) Product type (Mass, Premium, Super premium, Luxury)

Absolut Vodka, Asahi Group Holdings Ltd., Bacardi and Co. Ltd., Becle S.A.B. de C.V., Brown Forman Corp., Campari Group, Diageo PLC, Heaven Hill Distillery Inc., Hite Jinro Co. Ltd., Kirin Holdings Co. Ltd., Kweichow Moutai Co. Ltd., LVMH Moet Hennessy, Mast Jagermeister SE, Pernod Ricard SA, Remy Cointreau SA, Sazerac Co. Inc., Suntory Beverage and Food Ltd., Thai Beverage Public Co. Ltd., The Edrington Group Ltd., Wuliangye Yibin Co. Ltd. are a few of the key vendors in the Spirits market.

Europe will register the highest growth rate of 29.9% among the other regions. Therefore, the Spirits market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

UK, France, Germany, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Australia, Indonesia, US, Canada, Mexico, Brazil, Argentina, Chile, South Africa, Turkey, UAE, Saudi Arabia, Israel

  • Growing premiumization demand across alcoholic beverage categories is the driving factor this market.

The Spirits market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
