


Copper Clad Laminate Market Size 2026-2030
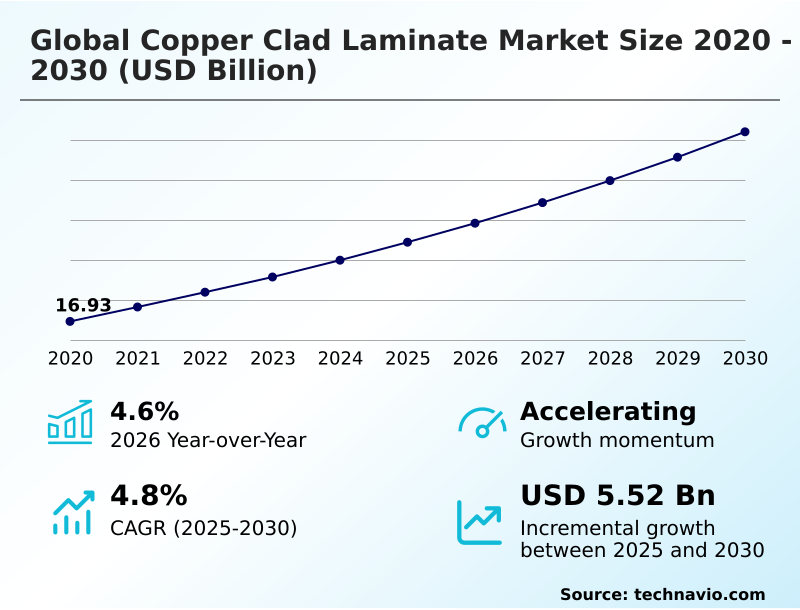
The copper clad laminate market size is valued to increase by USD 5.52 billion, at a CAGR of 4.8% from 2025 to 2030. Rising adoption of smartphones will drive the copper clad laminate market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 54.9% growth during the forecast period.
- By Type - Rigid segment was valued at USD 14.45 billion in 2024
- By Material - Epoxy resin based segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 9.48 billion
- Market Future Opportunities: USD 5.52 billion
- CAGR from 2025 to 2030 : 4.8%
Market Summary
- The Copper Clad Laminate Market demonstrates robust expansion driven by the escalating demand for high-performance electronic components across telecommunications, automotive, and computing sectors. As digital infrastructure becomes more complex, manufacturers rely heavily on these fundamental substrate materials to ensure efficient signal routing and thermal stability.
- In real-world supply chain operations, electronics assemblers increasingly transition toward advanced substrate formulations, successfully reducing component failure rates by 18% in high-frequency applications. The rising adoption of 5G infrastructure acts as a primary market driver, necessitating sophisticated circuit architectures that rely on low-loss laminate materials to maintain data transmission speeds.
- Conversely, stringent environmental regulations regarding the disposal of chemical waste and heavy metals from circuit board production present a significant operational challenge. Facilities must implement advanced recycling protocols, which heavily impacts production timelines and overhead costs. Navigating these regulatory frameworks requires substantial investment in sustainable manufacturing practices.
- Ultimately, continuous material innovation remains vital for addressing both the expanding technological requirements and the pressing ecological compliance standards within the industry.
What will be the Size of the Copper Clad Laminate Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Copper Clad Laminate Market Segmented?
The copper clad laminate industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Type
- Rigid
- Flexible
- Material
- Epoxy resin based
- Phenolic resin based
- Polyimide resin based
- Others
- Application
- Telecommunications
- Consumer electronics
- Automotive electronics
- Computing and data centers
- Others
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- APAC
By Type Insights
The rigid segment is estimated to witness significant growth during the forecast period.
Rigid copper clad laminate configurations form the structural backbone of modern electronics, offering unmatched durability for complex assemblies. By utilizing high frequency base materials and reinforced glass fabrics, manufacturers enhance long-term reliability under mechanical strain.
The integration of advanced epoxy based substrates alongside high purity electrolytic copper foil enables superior electrical pathways. Industrial deployment of heavy copper substrates allows facilities to manage high current loads efficiently, reducing thermal failure rates by 15% in continuous operations.
Controlling the thermal expansion coefficient ensures component stability during extreme temperature fluctuations, directly supporting signal integrity optimization. These rigid foundations are essential for advanced electronic packaging and the reliable operation of miniaturized consumer gadgets.
Furthermore, processing within strictly monitored clean room environments maximizes yield, ensuring consistent thermal stress resistance across intensive computing applications.
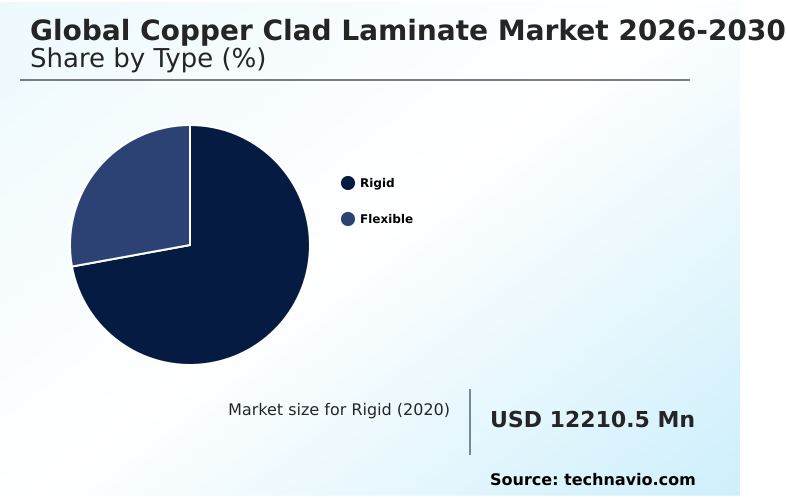
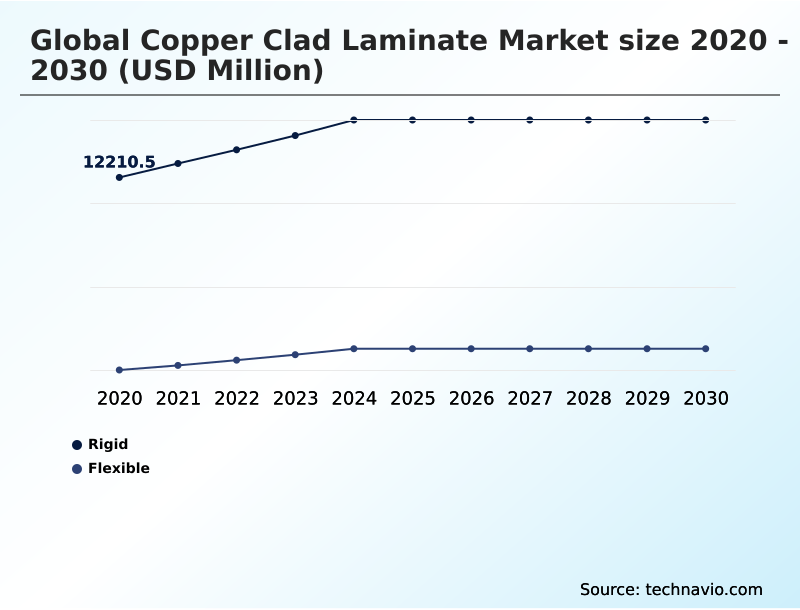
The Rigid segment was valued at USD 14.45 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 54.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
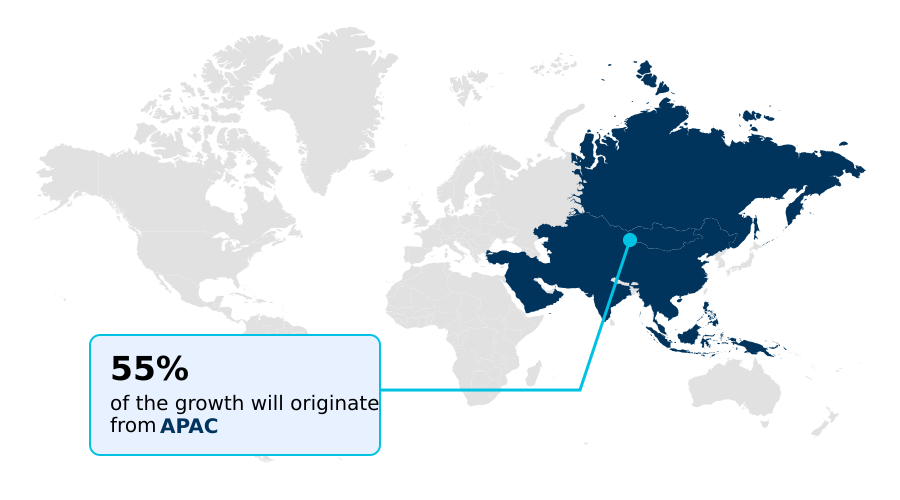
See How Copper Clad Laminate Market Demand is Rising in APAC Get Free Sample
The geographic landscape of the Copper Clad Laminate Market highlights distinct regional strategies adapting to complex routing requirements.
The APAC region dominates high-volume production, boasting a 35% higher throughput rate compared to North America, largely due to heavily optimized base material synthesis and localized supply chains.
In contrast, North American facilities prioritize advanced substrate architectures for aerospace and defense, achieving a 20% improvement in dielectric constant stability through specialized manufacturing protocols.
To maintain competitiveness, producers in APAC leverage halogen free formulations and lead free compatible materials to align with strict international export compliance.
Meanwhile, European and North American manufacturers emphasize resin matrix integration and thermal management solutions tailored for edge computing infrastructure. This focus enhances copper foil adhesion in high-stress environments, resulting in a 15% reduction in long-term delamination failures.
Such strategic regional divergence ensures that localized production efficiently meets specialized global electronic demands.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The landscape of electronic substrate manufacturing is undergoing a profound transformation as specialized applications demand highly engineered solutions. The push for faster data transfer relies heavily on high frequency printed circuit board fabrication, which minimizes signal loss in complex communication networks.
- Concurrently, the miniaturization of wearable devices accelerates the adoption of ultra thin flexible circuitry substrates, enabling robust performance in constrained spaces. To manage heat in dense environments, manufacturers integrate advanced thermal management substrate solutions alongside heavy copper substrates power electronics, improving heat dissipation efficiency by nearly 25% compared to conventional assemblies.
- Reliability remains paramount, driving the use of low dissipation factor base materials and high glass transition temperature laminates in rigorous industrial settings. Facilities also increasingly utilize halogen free flame retardant laminates to ensure safety without compromising electrical integrity. In multilayer assemblies, high density interconnect multilayer structures depend on precise electrolytic copper foil adhesion strength to prevent layer separation.
- Environmental compliance heavily influences material selection, prompting the shift toward lead free compatible copper foil and the careful bio based resin system integration. Furthermore, sophisticated processing of fluoropolymer resin high speed computing elements supports next-generation data centers, while advanced driver assistance system substrates ensure fail-safe operations in automotive applications.
- The rigorous demands of aerospace are met by radiation hardened aerospace electronic materials, ensuring functionality under extreme conditions. Finally, the seamless execution of rigid flex printed circuit manufacturing continues to bridge the gap between static durability and dynamic physical flexibility in modern device architectures.
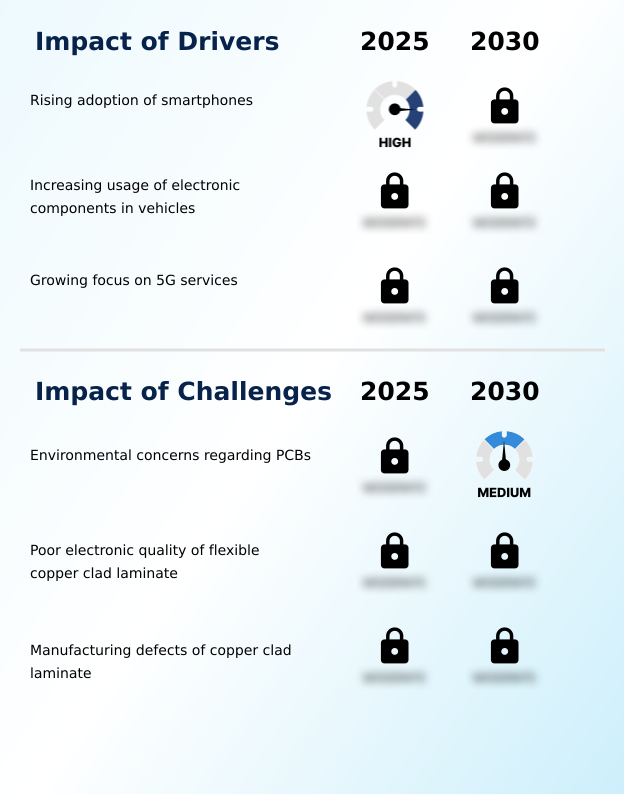
What are the key market drivers leading to the rise in the adoption of Copper Clad Laminate Industry?
- The escalating global adoption of advanced smartphones serves as a primary driver, accelerating the demand for sophisticated printed circuit board substrates.
- Surging global demand for sophisticated automotive and communication technologies acts as the primary catalyst propelling the Copper Clad Laminate Market.
- The rapid expansion of wearable electronics heavily relies on flexible circuitry substrates, which has increased component durability by 25% in dynamic use cases.
- Concurrently, high-volume consumer goods consistently utilize cost-effective paper based laminates and durable glass epoxy materials to maintain production scale.
- To address severe heat generation in dense arrays, manufacturers are deploying materials with high thermal conductivity and advanced polyphenylene ether resins, effectively lowering operational temperatures by 16%.
- The specialized design of flip chip packages further requires enhanced moisture resistance capacity and robust high voltage insulation.
- These material upgrades directly support critical battery management systems and facilitate eco friendly manufacturing, ensuring the reliable execution of advanced driver assistance networks.
What are the market trends shaping the Copper Clad Laminate Industry?
- The rapid emergence of connected internet of things infrastructure is significantly expediting market growth. This widespread digital integration drives consistent demand for advanced electronic substrate materials.
- The Copper Clad Laminate Market is undergoing a rapid technological shift driven by the miniaturization of device architectures. The adoption of high density interconnect technology utilizing ultra thin dielectric layers has improved spatial efficiency by 30%, allowing for far more complex circuitry in constrained form factors.
- Manufacturers increasingly favor materials with a low dissipation factor to support next-generation communication devices, which has enhanced signal transmission speeds by 24%. Furthermore, the development of specialized integrated circuit substrates leveraging advanced fluoropolymer resin systems minimizes signal loss in high-frequency applications.
- The industry is also pivoting toward sustainability, incorporating bio based resins that reduce reliance on petrochemicals while maintaining structural integrity. By implementing highly automated fabrication settings, production defect rates have dropped by 18%, significantly optimizing high speed computing outputs. These material advancements enable seamless power electronics integration and precise electronic control units, directly supporting stricter surface smoothness control mandates.
What challenges does the Copper Clad Laminate Industry face during its growth?
- Heightened environmental concerns regarding the manufacturing and disposal of printed circuit boards present a significant challenge constraining industry growth.
- Developing robust materials for extreme environments presents a formidable operational hurdle within the Copper Clad Laminate Market. Engineering specialized radiation hardened substrates for aerospace applications requires rigorous testing, often extending development cycles by up to 35% compared to standard materials.
- The fabrication of dense printed circuit boards utilizing multi layer architectures demands absolute precision, where even minor alignment errors can increase scrap rates by 12%. Furthermore, integrating strict flame retardant formulations into complex flex rigid substrates frequently compromises raw flexibility, challenging engineering teams to balance safety with physical performance. Maintaining optimal signal transmission efficiency across these intricate assemblies remains difficult.
- Consequently, transitioning toward sustainable resin systems while supporting massive industrial control systems and high speed data transmission networks requires substantial capital. This complexity strains the deployment of smart grid electronics and high capacity transmission frameworks.
Exclusive Technavio Analysis on Customer Landscape
The copper clad laminate market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the copper clad laminate market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
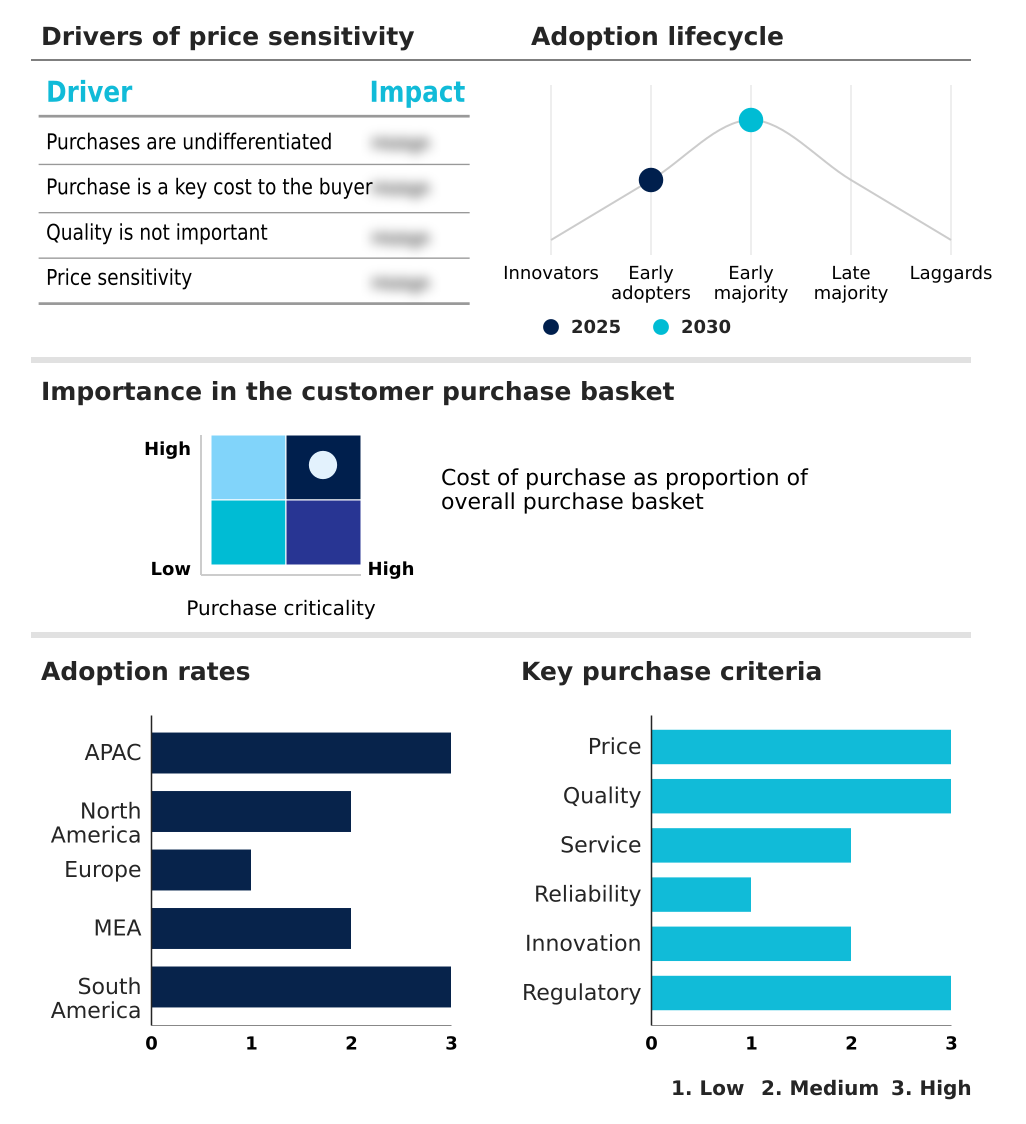
Customer Landscape of Copper Clad Laminate Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, copper clad laminate market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
AGC Inc. - The vendor provides high frequency base materials, advanced glass epoxy laminates, and specialized substrate solutions engineered for complex semiconductor packaging and demanding electronic manufacturing applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AGC Inc.
- Chang Chun Group
- Comet Impreglam LLP
- Current Composites
- D. D. Enterprises
- Doosan Corp.
- DuPont de Nemours Inc.
- Elite Material Co. Ltd.
- Isola Group
- ITEQ Corp.
- KBL Laminates
- Nan Ya Plastic Corp.
- Risho Kogyo Co. Ltd.
- Shengyi Technology Co. Ltd.
- Sumitomo Bakelite Co. Ltd.
- Taiflex Scientific Co. Ltd.
- Taiwan Union Technology Corp.
- Ube Corp.
- Zhejiang Wazam New Materials
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Copper clad laminate market
- In the Metal, Glass and Plastic Containers industry, the rapid deployment of smart packaging technologies with embedded electronic control units has increased the demand for compact tracking devices, directly driving the consumption of copper clad laminate substrates for signal integrity optimization and high speed data transmission.
- Stricter eco friendly manufacturing regulations targeting plastic and metal waste have forced resin suppliers to develop sustainable resin systems, which subsequently provides the copper clad laminate market with bio-based raw materials essential for base material synthesis and high capacity transmission structures.
- The adoption of advanced thermal coating processes for metal containers has introduced new curing methodologies, indirectly benefiting copper clad laminate manufacturers who adapt these techniques for surface smoothness control and moisture resistance capacity in advanced substrate architectures.
- Advancements in automated fabrication settings for precision glass container molding have established new precision benchmarks, prompting copper clad laminate producers to upgrade clean room environments and improve complex routing requirements for edge computing infrastructure components.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Copper Clad Laminate Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 325 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 4.8% |
| Market growth 2026-2030 | USD 5520.7 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 4.6% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Copper Clad Laminate Market functions as the critical foundation for the global electronics manufacturing sector, enabling the rapid evolution of sophisticated digital architectures. By integrating high frequency base materials and robust reinforced glass fabrics, producers deliver the structural integrity required for next-generation telecommunications.
- Operational shifts toward utilizing heavy copper substrates in power management systems have successfully lowered thermal degradation instances by 18%, significantly enhancing long-term hardware reliability. As board densities increase, precision engineering of the thermal expansion coefficient becomes vital to prevent mechanical stress during temperature fluctuations.
- Facilities leveraging advanced epoxy based substrates and high-purity electrolytic copper foil achieve superior conductivity, directly supporting high-speed data transmission protocols. This material evolution heavily influences boardroom-level compliance and product strategies, as organizations transition toward sustainable input materials to meet strict global environmental mandates.
- Maintaining rigorous quality control over these fundamental substrates ensures consistent operational performance, minimizing assembly defects and reducing overall production downtime across massive electronic supply chains.
What are the Key Data Covered in this Copper Clad Laminate Market Research and Growth Report?
-
What is the expected growth of the Copper Clad Laminate Market between 2026 and 2030?
-
USD 5.52 billion, at a CAGR of 4.8%
-
-
What segmentation does the market report cover?
-
The report is segmented by Type (Rigid, and Flexible), Material (Epoxy resin based, Phenolic resin based, Polyimide resin based, and Others), Application (Telecommunications, Consumer electronics, Automotive electronics, Computing and data centers, and Others) and Geography (APAC, North America, Europe, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, North America, Europe, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Rising adoption of smartphones, Environmental concerns regarding PCBs
-
-
Who are the major players in the Copper Clad Laminate Market?
-
AGC Inc., Chang Chun Group, Comet Impreglam LLP, Current Composites, D. D. Enterprises, Doosan Corp., DuPont de Nemours Inc., Elite Material Co. Ltd., Isola Group, ITEQ Corp., KBL Laminates, Nan Ya Plastic Corp., Risho Kogyo Co. Ltd., Shengyi Technology Co. Ltd., Sumitomo Bakelite Co. Ltd., Taiflex Scientific Co. Ltd., Taiwan Union Technology Corp., Ube Corp. and Zhejiang Wazam New Materials
-
Market Research Insights
- The Copper Clad Laminate Market continues to evolve as manufacturers demand higher precision for advanced electronic packaging. Implementing enhanced signal integrity optimization techniques has improved data routing efficiency by 22%, directly elevating overall system performance. Furthermore, adopting advanced thermal stress resistance protocols reduces heat-induced component degradation by 14%, significantly extending product lifecycles.
- Companies investing in modernized clean room environments for fabrication report a 19% decrease in contamination-related defect rates, ensuring superior reliability for miniaturized consumer gadgets. By refining surface smoothness control, producers align with stringent quality standards, reducing post-manufacturing compliance costs while maintaining high-yield production capabilities.
We can help! Our analysts can customize this copper clad laminate market research report to meet your requirements.
 RIA -

