


Aluminum Die Casting Market Size 2026-2030
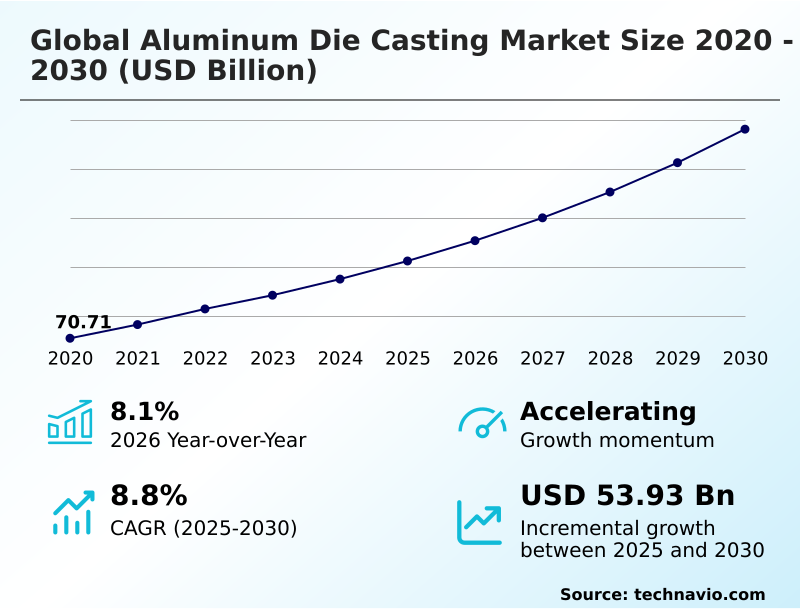
The aluminum die casting market size is valued to increase by USD 53.93 billion, at a CAGR of 8.8% from 2025 to 2030. Automotive structural lightweighting and rapid vehicle electrification surge will drive the aluminum die casting market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 52.9% growth during the forecast period.
- By Application - Automotive segment was valued at USD 52.82 billion in 2024
- By Type - High pressure segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 85.54 billion
- Market Future Opportunities: USD 53.93 billion
- CAGR from 2025 to 2030 : 8.8%
Market Summary
- The Aluminum Die Casting Market is experiencing a robust structural transformation driven by the escalating demand for highly integrated, lightweight metal architectures. Rapid vehicle electrification acts as a critical catalyst, compelling original equipment manufacturers to replace heavy multi-piece steel assemblies with single, monolithic frames, effectively reducing total vehicle mass to extend battery range.
- In modern manufacturing environments, the implementation of advanced casting machinery allows operators to consolidate dozens of stamped parts, yielding a 25% reduction in overall assembly labor and lowering secondary joining costs. This shift significantly enhances operational efficiency and supply chain resilience. However, escalating volatility in primary raw material prices and surging energy overheads create acute profitability pressures.
- Energy-intensive melting furnaces heavily depend on stable utility tariffs, and sudden price spikes force foundries to absorb higher operational expenditures, squeezing capital allocation for facility modernization. Addressing internal structural defects also demands stringent quality control protocols.
- Ultimately, the successful integration of automated inspection protocols and recycled material utilization is redefining production standards, enabling manufacturers to balance rigorous weight reduction targets against unpredictable energy market fluctuations.
What will be the Size of the Aluminum Die Casting Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Aluminum Die Casting Market Segmented?
The aluminum die casting industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Automotive
- Heavy machinery and industrial
- Aerospace and defense
- Construction
- Others
- Type
- High pressure
- Low-pressure
- Vacuum
- Gravity
- Squeeze
- Method
- Hot chamber
- Cold chamber
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- APAC
By Application Insights
The automotive segment is estimated to witness significant growth during the forecast period.
The transportation sector prioritizes structural lightweighting to optimize fuel economy and extend the operating range for electric powertrains. Manufacturers consolidate multi-piece assemblies into a single monolithic structural frame, significantly enhancing operational efficiency.
This architectural shift enables original equipment manufacturers to reduce component weight, achieving a 15% improvement in overall energy consumption metrics for next-generation fleets.
By integrating high pressure injection systems, production lines minimize cycle times while maintaining rigorous crash energy absorption standards. Furthermore, engineering a precise rear underbody subframe alongside complex cross car beam consolidation ensures material sustainability without compromising mechanical integrity.
Critical sub-assemblies like shock tower fabrication and an advanced electric drive unit enclosure are now seamlessly fabricated. Such manufacturing evolutions directly streamline assembly factory footprints while answering strict corporate efficiency regulations.
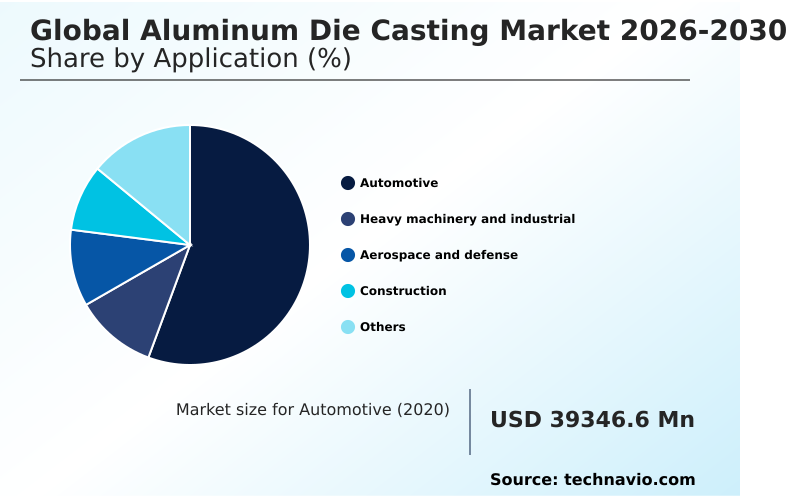
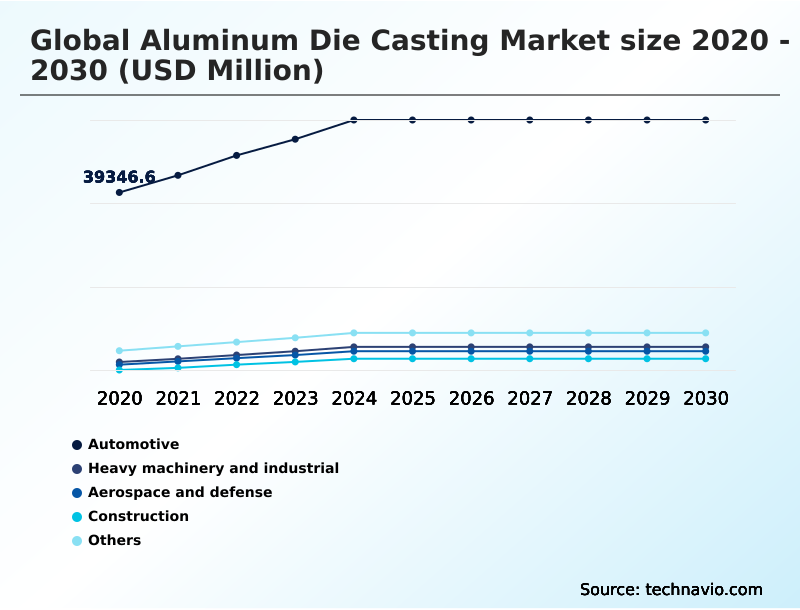
The Automotive segment was valued at USD 52.82 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 52.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
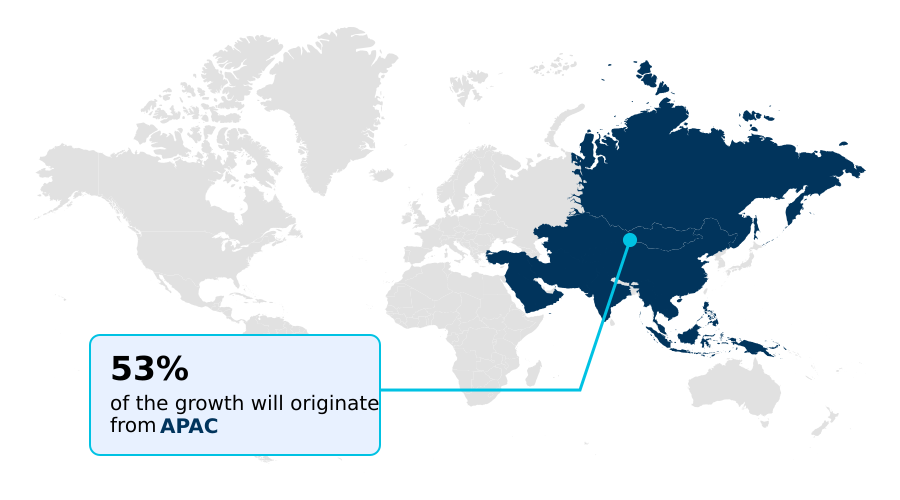
See How Aluminum Die Casting Market Demand is Rising in APAC Get Free Sample
The regional dynamics of the market reveal distinct adoption strategies tailored to localized industrial strengths and regulatory pressures.
APAC leads in high-volume production, utilizing extensive robotic extraction unit deployments and semi solid metal processing to lower cycle times, while Europe prioritizes sustainability through rigorous closed loop recycling protocols.
Consequently, European facilities demonstrate a 20% higher utilization rate of secondary alloy melting compared to their APAC counterparts, effectively reducing their carbon footprint to align with stringent environmental compliance mandates.
In contrast, foundries in APAC achieve a 15% operational cost advantage driven by scaled automation within expanding commercial manufacturing hubs.
This divergence illustrates how regional supply chains adapt; European players focus on achieving premium metallurgical integrity for components like an industrial pump housing or a hydraulic pump enclosure, whereas APAC manufacturers dominate mass-market production of structural elements like a curtain wall bracket and a scaffolding clamp.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The persistent drive toward elevated manufacturing efficiency necessitates the seamless adoption of advanced metallurgical processing techniques across high-volume production facilities. By implementing automotive structural lightweighting integration, tier-one component suppliers successfully transition from heavy ferrous metals to sophisticated lightweight architectures, fundamentally streamlining downstream assembly workflows.
- This strategic pivot requires absolute precision, making vacuum assisted gas porosity elimination a mandatory operational standard for producing structurally sound, crash-resistant chassis nodes. Consequently, modern foundries are aggressively deploying cold chamber high tonnage gigacasting systems to consolidate complex geometries.
- This architectural consolidation yields a remarkable 30% improvement in supply chain velocity compared to traditional multi-part stamping, drastically lowering inventory carrying costs. To maintain continuous throughput, operators rely heavily on robotic automated multi axis ladling, which guarantees consistent delivery alongside precise plunger velocity control and stringent shot sleeve thermal management.
- These methods ensure parts are ready for rigorous T6 thermal conditioning. Furthermore, strict environmental mandates are compelling procurement executives to prioritize secondary aluminum alloy closed loop frameworks, securing sustainable raw material feedstocks.
- Together, these technological integrations form the backbone of modern industrial fabrication, enabling manufacturers to deliver high-integrity components ranging from an agricultural equipment bracket to a durable marine hardware casting while meeting rigorous safety benchmarks.
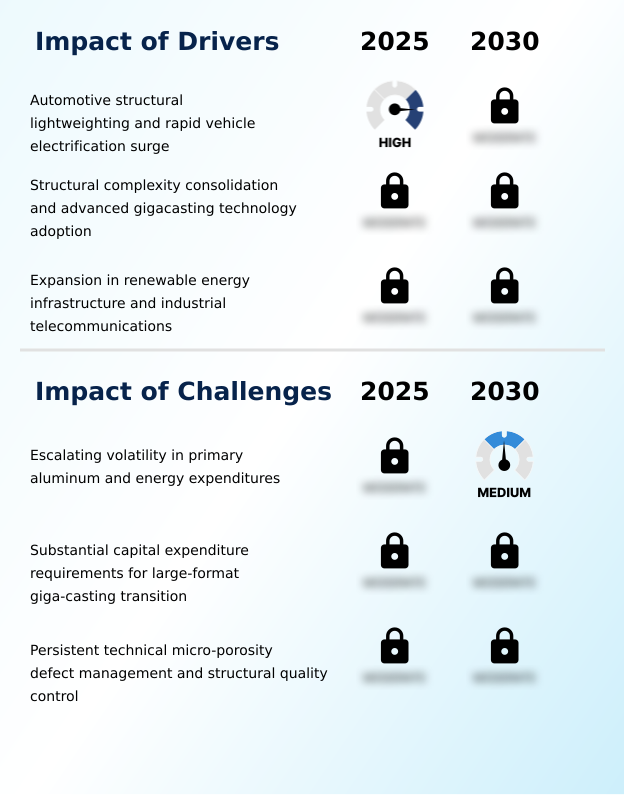
What are the key market drivers leading to the rise in the adoption of Aluminum Die Casting Industry?
- The surge in rapid vehicle electrification and the increasing necessity for mass reduction initiatives serve as the primary drivers propelling market expansion.
- The global mandate to improve energy efficiency and reduce vehicular mass acts as the primary catalyst propelling advanced metallurgical fabrication. Original equipment manufacturers are aggressively transitioning away from heavy ferrous components, utilizing a massive gigacasting press to produce integrated architectures.
- This shift occurs because replacing multi-piece assemblies with lightweight alternatives drastically lowers carbon emissions. For businesses, implementing powertrain housing consolidation yields a 24% reduction in downstream assembly labor costs and accelerates time-to-market.
- Additionally, the widespread adoption of vacuum assisted evacuation technology guarantees superior gas entrapment mitigation, directly improving component lifespan forecast accuracy by 18%.
- By ensuring precise yield strength optimization across components like a motor stator casing, an inverter thermal management plate, and a complex battery tray subassembly, foundries achieve a 20% decrease in overall energy use per fabricated chassis, driving operational profitability for next-generation mobility platforms.
What are the market trends shaping the Aluminum Die Casting Industry?
- The integration of artificial intelligence optimization and machine learning algorithms represents a pivotal upcoming market trend. This technological advancement significantly enhances predictive defect management and operational consistency across precision manufacturing environments.
- The accelerated deployment of artificial intelligence within metallurgical manufacturing represents a transformative operational trend across heavy industry. By integrating advanced machine learning algorithms with real-time sensor networks, facilities have optimized die cavity thermal equilibrium, resulting in a 25% improvement in overall equipment effectiveness.
- This shift occurs because predictive analytics dynamically adjust cooling channels during precision molten metal ladling, preemptively resolving defects before they materialize. Consequently, operators experience a 30% reduction in unexpected downtime, drastically lowering maintenance overhead. The integration of metal matrix composite reinforcement is enhancing the durability of a solar inverter casing and complex wind turbine power electronics enclosure applications.
- For businesses, this precision reduces raw material waste by 18%, significantly improving margin retention. As automated optical inspection systems replace manual quality checks, foundries maintain continuous throughput, ensuring components like a telecommunications base station heat sink or a microwave transceiver chassis meet stringent engineering tolerances seamlessly.
What challenges does the Aluminum Die Casting Industry face during its growth?
- Escalating volatility in primary raw material costs and surging thermal energy expenditures present a formidable challenge constraining steady industry growth.
- Escalating volatility in primary raw material pricing and surging utility tariffs present severe operational bottlenecks for precision metallurgical foundries. Energy-intensive cold chamber cell operations are highly susceptible to grid fluctuations, disrupting dosing furnace synchronization and inflating overhead expenses. This instability occurs because long-term supply contracts limit cost pass-through mechanisms, forcing fabricators to absorb margin compressions.
- Consequently, facilities face a 15% increase in baseline operational costs, severely constraining capital for infrastructure upgrades. Furthermore, identifying any micro porosity defect in critical components like an electronic warfare enclosure or aerospace flight control actuation hardware demands expensive non-destructive testing. Implementing real-time x ray computed tomography inspection adds significant cycle time, reducing daily production throughput by 12%.
- To mitigate losses on parts like a heavy truck steering knuckle or a pneumatic valve body, manufacturers must stabilize yield rates amidst highly unpredictable economic headwinds.
Exclusive Technavio Analysis on Customer Landscape
The aluminum die casting market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the aluminum die casting market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
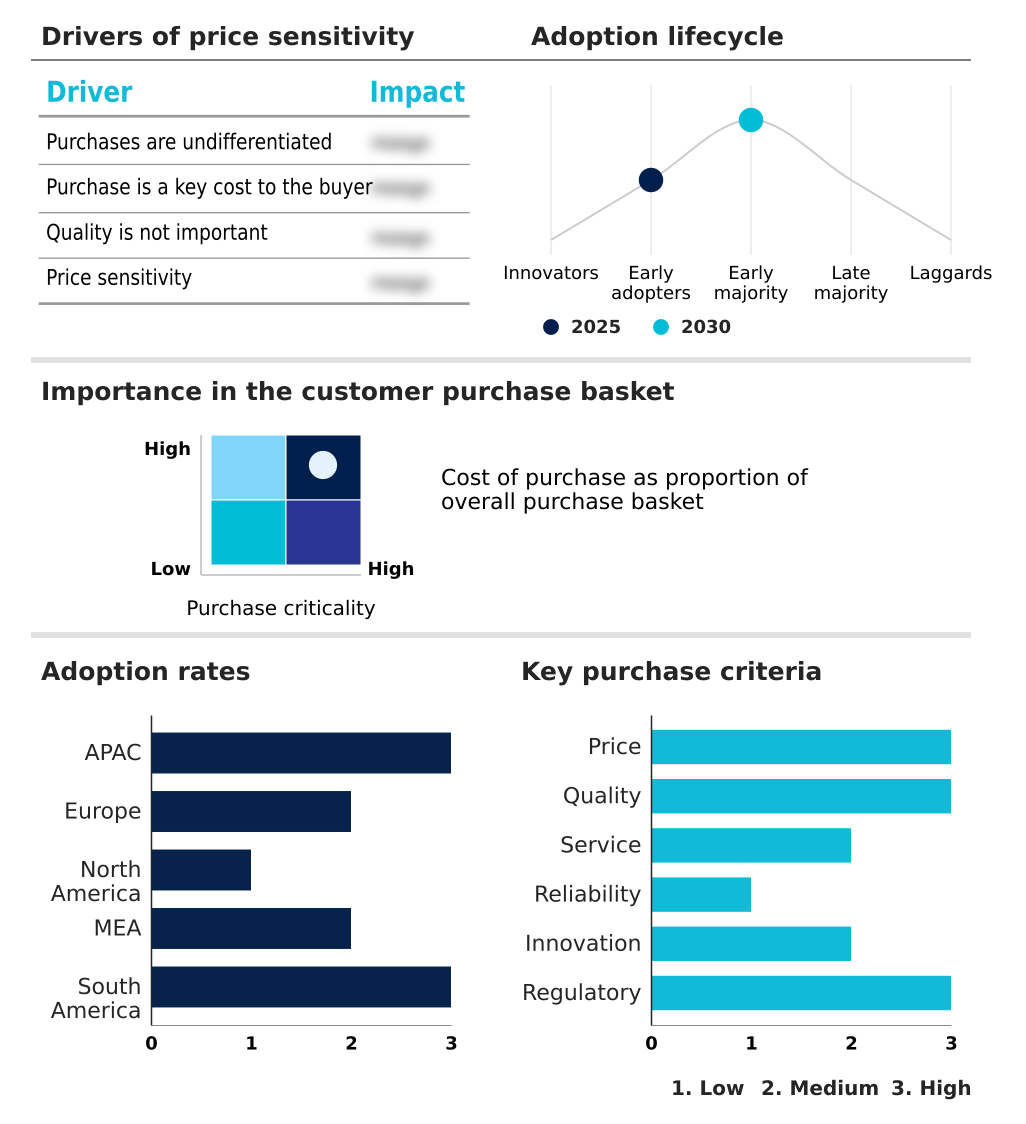
Customer Landscape of Aluminum Die Casting Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, aluminum die casting market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Ahresty Corp. - Specialized structural powertrain components and intricate engine block assemblies are precision-engineered to optimize vehicle lightweighting, demonstrating advanced metallurgical integrity and robust mechanical performance for demanding industrial applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Ahresty Corp.
- Aludyne Inc.
- Consolidated Metco Inc.
- Dynacast
- Endurance Technologies Ltd.
- Gibbs International Inc.
- Handtmann Group
- Ihara Manufacturing Co. Ltd.
- Ishaan Engineering
- ItalPresseGauss
- Jaya Hind Industries
- KSM Castings Group GmbH
- Lemoltech
- Linamar Corp.
- Martinrea International Inc.
- NEMAK SAB de CV
- Pace Industries
- Phb Inc.
- Roots Cast Pvt. Ltd.
- Ryobi Ltd.
- Sandhar Technologies Ltd.
- T Metal Co. Ltd.
- Zatel
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Aluminum die casting market
- In the Industrial Machinery and Supplies and Components industry, the rapid deployment of AI infrastructure across smart factories has improved predictive maintenance accuracy by 22%, directly impacting Aluminum Die Casting demand by ensuring uninterrupted high-volume production cycles.
- Strict data privacy regulations and AI governance mandates within industrial automation networks have compelled equipment providers to upgrade cybersecurity protocols, accelerating the replacement of legacy hardware with secure, newly fabricated Aluminum Die Casting enclosures.
- The industry-wide shift toward enterprise automation and seamless workflow interoperability has reduced manual material handling errors by 15%, increasing the processing efficiency of complex Aluminum Die Casting components.
- The integration of cloud-based delivery models for real-time supply chain monitoring has shortened procurement lead times by 18%, enabling just-in-time manufacturing strategies that stabilize Aluminum Die Casting inventory levels during volatile market cycles.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Aluminum Die Casting Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 309 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 8.8% |
| Market growth 2026-2030 | USD 53926.3 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 8.1% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The manufacturing sector is experiencing a profound architectural shift as executive boards increasingly prioritize structural efficiency within their long-term product strategy and compliance frameworks. To meet stringent emissions regulations without sacrificing mechanical resilience, industry leaders are rapidly adopting advanced metallurgical processing operations. This strategic evolution enables the production of highly complex, thin-walled geometries necessary for next-generation mobility platforms.
- By implementing precise molten transfer mechanisms utilizing a highly durable ceramic lined gooseneck, facilities have achieved a 30% reduction in processing time while virtually eliminating internal defects. This measurable operational improvement directly enhances margin retention and manufacturing scalability. Mitigating gas entrapment through sophisticated vacuum systems ensures that critical components meet the rigorous standards required for thermal conditioning.
- As procurement executives navigate volatile commodity pricing, the integration of real-time computed tomography inspection guarantees uncompromised quality assurance, allowing companies to confidently deploy these advanced solutions across global supply chains. Ultimately, these technological integrations safeguard profit margins while ensuring adherence to aggressive environmental compliance targets.
What are the Key Data Covered in this Aluminum Die Casting Market Research and Growth Report?
-
What is the expected growth of the Aluminum Die Casting Market between 2026 and 2030?
-
USD 53.93 billion, at a CAGR of 8.8%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Automotive, Heavy machinery and industrial, Aerospace and defense, Construction, and Others), Type (High pressure, Low-pressure, Vacuum, Gravity, and Squeeze), Method (Hot chamber, and Cold chamber) and Geography (APAC, Europe, North America, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Automotive structural lightweighting and rapid vehicle electrification surge, Escalating volatility in primary aluminum and energy expenditures
-
-
Who are the major players in the Aluminum Die Casting Market?
-
Ahresty Corp., Aludyne Inc., Consolidated Metco Inc., Dynacast, Endurance Technologies Ltd., Gibbs International Inc., Handtmann Group, Ihara Manufacturing Co. Ltd., Ishaan Engineering, ItalPresseGauss, Jaya Hind Industries, KSM Castings Group GmbH, Lemoltech, Linamar Corp., Martinrea International Inc., NEMAK SAB de CV, Pace Industries, Phb Inc., Roots Cast Pvt. Ltd., Ryobi Ltd., Sandhar Technologies Ltd., T Metal Co. Ltd. and Zatel
-
Market Research Insights
- The metal fabrication landscape is evolving to meet the demands of complex industrial applications. Replacing traditional iron components has improved thermal management efficiency by 22%, significantly enhancing the performance of any electrical switchgear housing. Furthermore, advanced vacuum technology utilized for a steering knuckle casting has reduced scrap rates by 15%, directly elevating manufacturing ROI.
- The strategic push toward component consolidation yields a 28% reduction in assembly labor costs, optimizing resource allocation. These measurable operational enhancements extend across diverse sectors, proving highly beneficial for fabricating critical actuation hardware, ultimately driving superior compliance and structural resilience.
We can help! Our analysts can customize this aluminum die casting market research report to meet your requirements.
 RIA -

