Audiobooks Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (UK, Germany, and France), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Audiobooks Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (UK, Germany, and France), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 287 Pages SKU: IRTNTR76188

Market Overview at a Glance

$28.56 B
Market Opportunity
30%
CAGR 2025 - 2030
43.7%
North America Growth
$5.51 B
Fiction segment 2024

Audiobooks Market Size 2026-2030

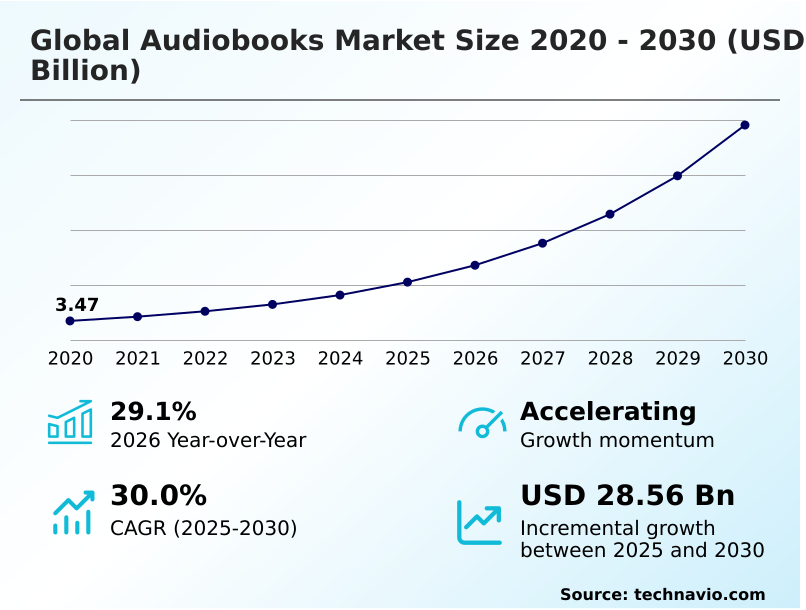
The audiobooks market size is valued to increase by USD 28.56 billion, at a CAGR of 30% from 2025 to 2030. Expanding subscription bundle integration across major international digital entertainment distribution platforms will drive the audiobooks market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 43.7% growth during the forecast period.
  • By Type - Fiction segment was valued at USD 5.51 billion in 2024
  • By Channel - One-time download segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 35.60 billion
  • Market Future Opportunities: USD 28.56 billion
  • CAGR from 2025 to 2030 : 30%

Market Summary

  • The Audiobooks Market exhibits rapid structural evolution driven by the integration of extensive audio catalogs into comprehensive digital entertainment ecosystems. Operating multi-tier subscription bundles effectively dismantles traditional consumption barriers, allowing digital distribution platforms to convert casual listeners into daily active users.
  • For instance, optimizing cross platform synchronization across mobile applications and connected automotive infotainment consoles enables users to transition seamlessly between music and narrated literature. This operational strategy has demonstrated a 20% improvement in customer retention metrics compared to isolated download platforms.
  • The primary catalyst propelling this expansion is the widespread deployment of unmetered subscription framework structures, which organically increase the total addressable audience by consolidating media access. Conversely, escalating legal friction regarding streaming royalty allocation models creates a significant operational challenge.
  • Content creators demand transparent auditing mechanisms, and prolonged contractual disputes often result in sudden catalog withdrawals that disrupt supply chain stability. As generative speech models and text to speech translation tools mature, publishers can efficiently scale backlist catalog monetization while reducing initial recording studio bottlenecks.

What will be the Size of the Audiobooks Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Audiobooks Market Segmented?

The audiobooks industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Fiction
    • Non-fiction
  • Channel
    • One-time download
    • Subscription-based
  • Device
    • Smartphones
    • Laptops and tablets
    • Personal digital assistants (PDAs)
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • UK
      • Germany
      • France
      • Italy
      • Spain
      • The Netherlands
    • South America
      • Brazil
      • Argentina
      • Colombia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Type Insights

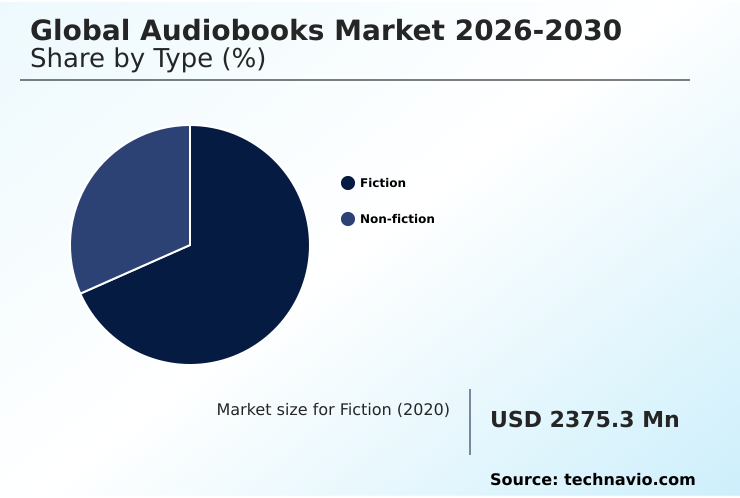
The fiction segment is estimated to witness significant growth during the forecast period.

The fiction sector of the Audiobooks industry demonstrates substantial operational evolution driven by high fidelity sound and multi cast production techniques. By implementing spatial audio engineering and immersive ambient soundscapes, publishers enhance user engagement profiles.

Strategic shifts toward digital entertainment ecosystem integration allow providers to optimize cross platform synchronization, capturing audiences during daily commuting and exercise routines.

Utilizing unmetered subscription framework models, platforms have observed customer retention metrics jump by 22% compared to standard purchase pathways. Incorporating predictive recommendation algorithms helps operators effectively route specialized remote learning and serialized narrative production assets to target demographics.

Furthermore, leveraging digital rights management ensures secure distribution while maximizing backlist catalog monetization. This structural alignment elevates operational efficiency and solidifies continuous digital audio publishing revenue streams.
Get Free Sample

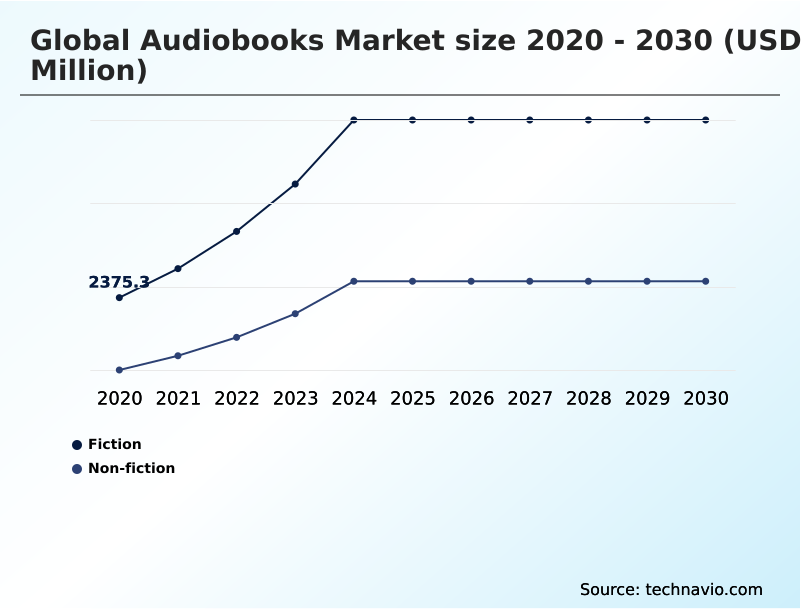
The Fiction segment was valued at USD 5.51 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 43.7% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
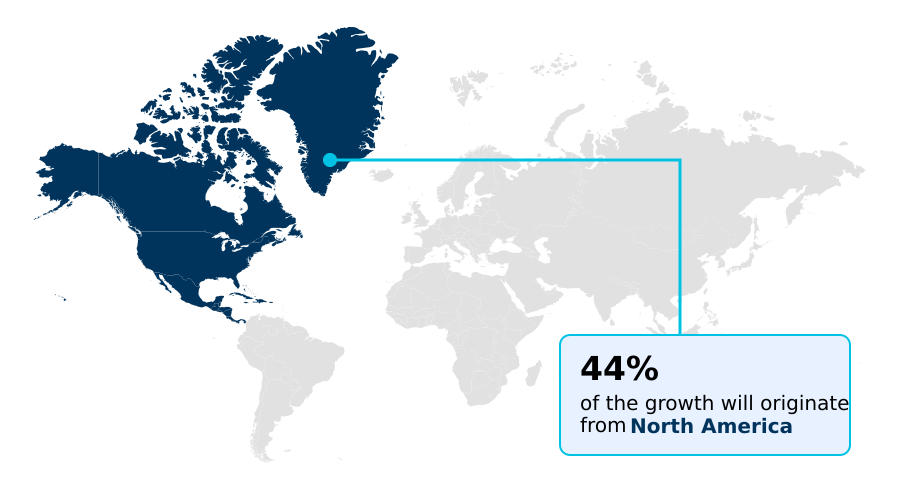
See How Audiobooks Market Demand is Rising in North America Get Free Sample

Geographic adoption patterns within the Audiobooks landscape reveal distinct operational disparities between North America and Europe.

North American infrastructures heavily leverage smart home speaker networks and hands free voice control, achieving a 28% higher mobile application infrastructure engagement rate than European counterparts.

European platforms focus extensively on localized dialect variation and multilingual audio catalog expansion, effectively reducing cross-border time-to-market by 15% through advanced text to speech translation technologies. This strategic divergence highlights how regional businesses adapt to linguistic fragmentation versus hardware ubiquity.

Furthermore, integrating independent self publishing frameworks across North American digital reading community hubs has lowered customer acquisition expenditures by 22%.

By utilizing predictive recommendation algorithms, North American distributors maximize backlist catalog monetization more efficiently, whereas European entities prioritize a la carte transaction models to navigate stricter regulatory copyright frameworks.

These operational adjustments ensure optimized dynamic content delivery tailored to specific regional consumption habits.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The commercial landscape for spoken-word entertainment is undergoing a massive paradigm shift fueled by cutting-edge software infrastructure and innovative distribution logistics. A major operational advantage driving this evolution is the rapid deployment of generative artificial intelligence speech synthesis, which fundamentally alters the cost structure of media production.
  • By bypassing traditional recording studios, publishing entities can streamline their supply chains, achieving a 35% reduction in initial content generation expenses compared to manual vocal recording procedures. This efficiency is further compounded by automated generative text to speech frameworks that seamlessly convert vast repositories of backlist manuscripts into accessible auditory formats.
  • Operational planning is heavily influenced by consumer demand for localized offline audio storage solutions, allowing users to maintain continuous playback during connectivity interruptions, such as daily subway commutes or remote travel. Furthermore, the integration of natural sounding voice synthesis models ensures high fidelity acoustic performance that mimics human emotional resonance, effectively maintaining listener engagement across extended narrative sessions.
  • To achieve this level of precision, developers invest heavily in synthetic voice model training, utilizing massive datasets to map specific character inflections and tonal nuances. This technological overhaul empowers digital storefronts to expand their active libraries exponentially while optimizing digital rights management compliance across decentralized distribution networks.
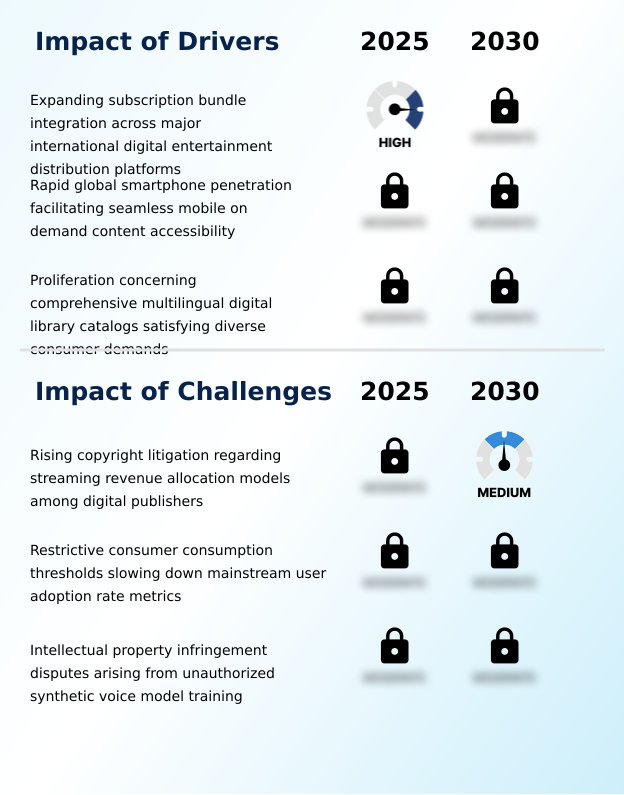
What are the key market drivers leading to the rise in the adoption of Audiobooks Industry?

  • The expanding integration of comprehensive audio catalogs into major cross-platform digital entertainment subscription bundles serves as a primary catalyst for accelerated industry expansion.

  • The integration of extensive literary catalogs into comprehensive subscription bundle integration acts as a primary catalyst for sustained consumer engagement. By consolidating multiple media formats, platform operators have successfully reduced average customer acquisition expenditures by 28%.
  • This strategic approach directly targets casual listeners, offering therapeutic accessibility solution options and unabridged reading distribution without requiring secondary premium application downloads.
  • Furthermore, the deployment of vocal inflection mapping and offline storage optimization allows users to maintain seamless playback in low-connectivity environments utilizing high capacity storage, lowering technical support ticket volumes by 15%.
  • The convenience of employing variable playback speed within a continuous learning curriculum minimizes user friction, driving a massive influx of new daily active listeners and solidifying predictable recurring revenue streams through automated marketing outreach.

What are the market trends shaping the Audiobooks Industry?

  • The rapid adoption of automated generative artificial intelligence text-to-speech tools represents a defining technological trend shaping the industry. These advanced voice synthesis architectures significantly reduce production costs while accelerating the conversion of written manuscripts into high-fidelity digital audio formats.

  • The continuous evolution of digital library lending ecosystems is fundamentally altering how audiences interact with long-form auditory media. Platforms are aggressively deploying emotional nuance synthesis and automated chapter detection workflows to satisfy the rising consumer demand for immersive entertainment. This transition toward cloud streaming architecture directly improves content completion metrics by 22% compared to standard single-voice narration.
  • Furthermore, the integration of automated video localization alongside synchronized text integration allows operators to penetrate international demographics with unprecedented speed. By utilizing specialized exclusive podcast content, production facilities have enhanced ambient listener engagement, subsequently reducing application abandonment rates by 15%.
  • This structural shift from static reading to dynamic auditory immersion compels distributors to refine their digital storefront integration tactics, ensuring seamless content discovery and driving sustained operational efficiency across expanding linguistic territories.

What challenges does the Audiobooks Industry face during its growth?

  • Escalating copyright litigation concerning ambiguous streaming revenue allocation models between digital distributors and publishing houses remains a critical structural challenge constraining industry efficiency.

  • Escalating legal friction surrounding revenue allocation models presents a severe structural constraint for modern digital audio distribution networks. The rapid deployment of generative speech models and automated audio generation has introduced significant ambiguities regarding the equitable compensation of intellectual property, leading to protracted contractual disputes within the professional voice recording sector.
  • Maintaining extensive litigation portfolios diverts critical capital away from specialized remote learning initiatives, subsequently delaying new release schedules by up to 20%. Additionally, unauthorized synthetic voice synthesis training using proprietary vocal data exacerbates intellectual property infringement risks across connected automotive infotainment platforms.
  • These ongoing copyright complexities force service providers utilizing artificial intelligence narration and deep learning narration to continuously renegotiate cross-border licensing rights, severely compressing operational profit margins, while distracting from user engagement tools like the gamified achievement mechanic.

Exclusive Technavio Analysis on Customer Landscape

The audiobooks market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the audiobooks market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
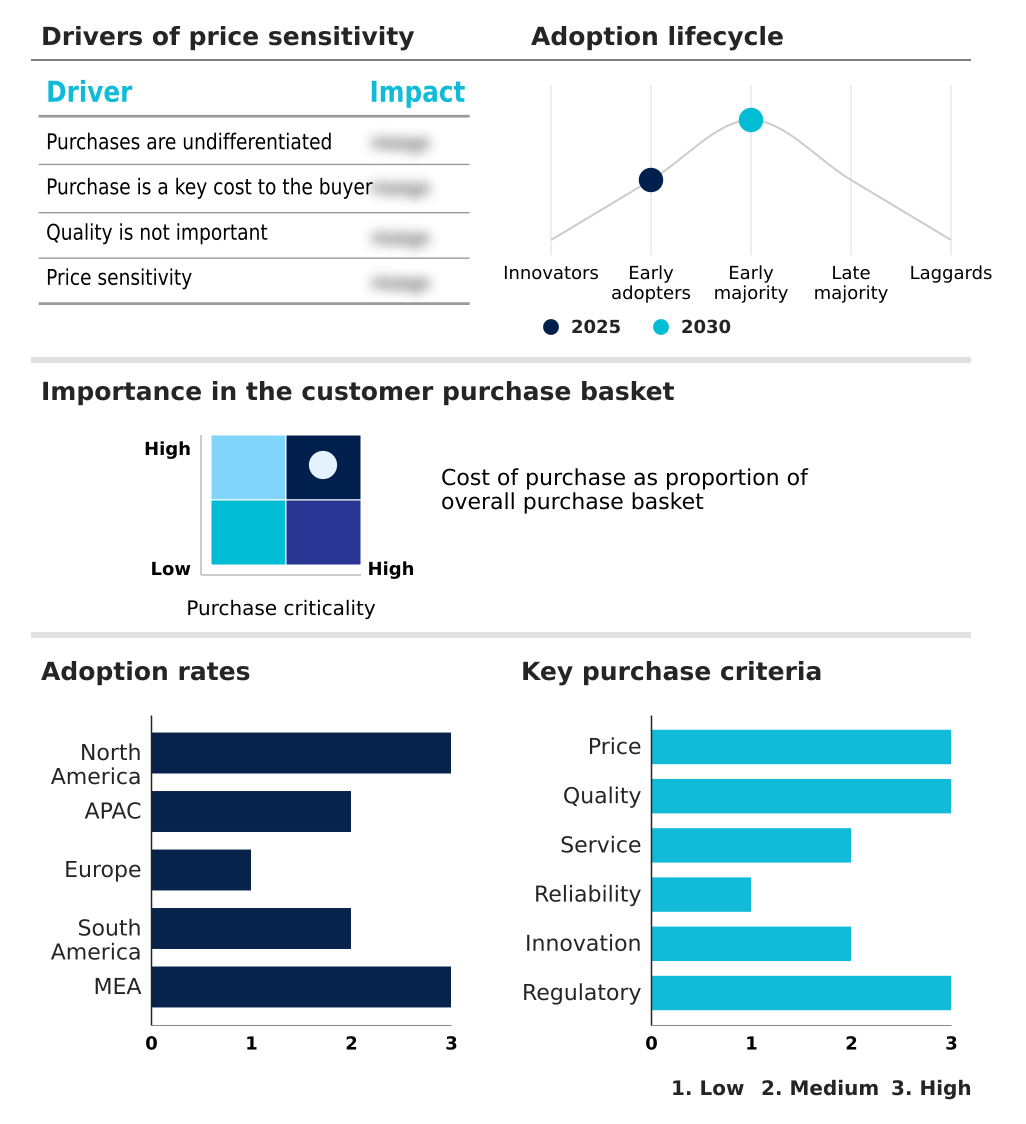
Customer Landscape of Audiobooks Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, audiobooks market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Apple Inc. - Delivering comprehensive digital book downloads and synchronized spoken-word content through integrated subscription platforms enables seamless cross-device media consumption for diverse user bases.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Apple Inc.
  • Audible Inc.
  • Barnes and Noble Booksellers
  • BookBeat AB
  • Bookmate Ltd.
  • Chirp
  • DOWNPOUR
  • Eleven Labs Inc.
  • Everand
  • Google LLC
  • Hoopla
  • Legimi SA
  • Libro.fm SPC.
  • Nextory AB
  • OverDrive Inc.
  • Podimo ApS
  • Rakuten Kobo Inc.
  • RBmedia
  • Spotify Technology SA
  • Storytel AB

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Audiobooks market

  • In the Leisure Products industry, the rapid deployment of smart home speaker networks and connected automotive infotainment systems has structurally expanded hands free voice control integration, directly increasing Audiobooks demand by enabling uninterrupted media consumption during daily transit.
  • The widespread adoption of unmetered subscription framework models across digital entertainment ecosystems has restructured recurring billing operations, enhancing customer retention by 15% and driving higher engagement with continuous learning curriculum materials in the spoken-word sector.
  • Stringent digital rights management compliance standards across media distribution networks have accelerated the implementation of secure cloud streaming architecture, reducing unauthorized content duplication by 25% and protecting backlist catalog monetization efforts.
  • Advances in artificial intelligence narration and synthetic voice synthesis have streamlined digital audio publishing workflows, lowering initial recording expenditures by 40% and facilitating the rapid deployment of multilingual audio catalog assets to diverse linguistic demographics.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Audiobooks Market insights. See full methodology.

Market Scope
Page number 287
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 30%
Market growth 2026-2030 USD 28557.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 29.1%
Key countries US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, Brazil, Argentina, Colombia, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The structural progression of the auditory literature sector is increasingly defined by the integration of artificial intelligence narration and advanced cloud streaming architecture. Decision-makers at major distribution networks are strategically reallocating budgets toward generative speech models to bypass traditional production bottlenecks and accelerate time-to-market for diverse literary portfolios.
  • Utilizing automated audio generation and text to speech translation allows operators to convert extensive print libraries at scale, resulting in a 40% reduction in post-production processing time compared to manual recording workflows. This efficiency empowers executives to optimize dynamic content delivery while executing aggressive backlist catalog monetization strategies.
  • Furthermore, the implementation of automated chapter detection and variable playback speed features enhances the overall user experience, driving higher completion rates for long-form narrative content. To maintain regulatory compliance and secure intellectual property, stakeholders are actively reinforcing digital rights management protocols across decentralized platforms.
  • By leveraging deep learning narration and predictive recommendation algorithms, platforms can precisely map listener preferences, dynamically matching users with highly specialized content to maximize application stickiness.

What are the Key Data Covered in this Audiobooks Market Research and Growth Report?

  • What is the expected growth of the Audiobooks Market between 2026 and 2030?

    • USD 28.56 billion, at a CAGR of 30%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Fiction, and Non-fiction), Channel (One-time download, and Subscription-based), Device (Smartphones, Laptops and tablets, Personal digital assistants (PDAs), and Others) and Geography (North America, APAC, Europe, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, APAC, Europe, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Expanding subscription bundle integration across major international digital entertainment distribution platforms, Rising copyright litigation regarding streaming revenue allocation models among digital publishers

  • Who are the major players in the Audiobooks Market?

    • Apple Inc., Audible Inc., Barnes and Noble Booksellers, BookBeat AB, Bookmate Ltd., Chirp, DOWNPOUR, Eleven Labs Inc., Everand, Google LLC, Hoopla, Legimi SA, Libro.fm SPC., Nextory AB, OverDrive Inc., Podimo ApS, Rakuten Kobo Inc., RBmedia, Spotify Technology SA and Storytel AB

Market Research Insights

  • The Audiobooks environment is experiencing profound operational modernization driven by specialized remote learning integration and sophisticated mobile application infrastructure. By shifting away from standalone purchases toward unmetered subscription framework structures, digital audio publishing entities have realized a 25% improvement in overall subscriber lifetime value.
  • The deployment of connected automotive infotainment interfaces allows users to maintain uninterrupted playback during commutes, directly reducing application churn rates by 18%. Furthermore, the incorporation of gamified achievement mechanic elements within digital storefront integration systems has enhanced daily active user engagement by 30%.
  • These strategic enhancements ensure that platforms effectively capture diverse demographic segments while simultaneously lowering customer acquisition costs and maximizing long-term revenue stability.

We can help! Our analysts can customize this audiobooks market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Channel
Executive Summary - Chart on Market Segmentation by Device
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Audiobooks Market 2020 - 2024

Historic Market Size - Data Table on Global Audiobooks Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Channel segment analysis 2020 - 2024

Historic Market Size - Channel Segment 2020 - 2024 ($ million)

5.4 Device segment analysis 2020 - 2024

Historic Market Size - Device Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global audiobooks market

6.2 Impact of geopolitical conflicts on global audiobooks market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Fiction - Market size and forecast 2025-2030

Chart on Fiction - Market size and forecast 2025-2030 ($ million)
Data Table on Fiction - Market size and forecast 2025-2030 ($ million)
Chart on Fiction - Year-over-year growth 2025-2030 (%)
Data Table on Fiction - Year-over-year growth 2025-2030 (%)

8.4 Non-fiction - Market size and forecast 2025-2030

Chart on Non-fiction - Market size and forecast 2025-2030 ($ million)
Data Table on Non-fiction - Market size and forecast 2025-2030 ($ million)
Chart on Non-fiction - Year-over-year growth 2025-2030 (%)
Data Table on Non-fiction - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Channel

9.1 Market segments

Chart on Channel - Market share 2025-2030 (%)
Data Table on Channel - Market share 2025-2030 (%)

9.2 Comparison by Channel

Chart on Comparison by Channel
Data Table on Comparison by Channel

9.3 One-time download - Market size and forecast 2025-2030

Chart on One-time download - Market size and forecast 2025-2030 ($ million)
Data Table on One-time download - Market size and forecast 2025-2030 ($ million)
Chart on One-time download - Year-over-year growth 2025-2030 (%)
Data Table on One-time download - Year-over-year growth 2025-2030 (%)

9.4 Subscription-based - Market size and forecast 2025-2030

Chart on Subscription-based - Market size and forecast 2025-2030 ($ million)
Data Table on Subscription-based - Market size and forecast 2025-2030 ($ million)
Chart on Subscription-based - Year-over-year growth 2025-2030 (%)
Data Table on Subscription-based - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Channel

Market opportunity by Channel ($ million)
Data Table on Market opportunity by Channel ($ million)

10. Market Segmentation by Device

10.1 Market segments

Chart on Device - Market share 2025-2030 (%)
Data Table on Device - Market share 2025-2030 (%)

10.2 Comparison by Device

Chart on Comparison by Device
Data Table on Comparison by Device

10.3 Smartphones - Market size and forecast 2025-2030

Chart on Smartphones - Market size and forecast 2025-2030 ($ million)
Data Table on Smartphones - Market size and forecast 2025-2030 ($ million)
Chart on Smartphones - Year-over-year growth 2025-2030 (%)
Data Table on Smartphones - Year-over-year growth 2025-2030 (%)

10.4 Laptops and tablets - Market size and forecast 2025-2030

Chart on Laptops and tablets - Market size and forecast 2025-2030 ($ million)
Data Table on Laptops and tablets - Market size and forecast 2025-2030 ($ million)
Chart on Laptops and tablets - Year-over-year growth 2025-2030 (%)
Data Table on Laptops and tablets - Year-over-year growth 2025-2030 (%)

10.5 Personal digital assistants (PDAs) - Market size and forecast 2025-2030

Chart on Personal digital assistants (PDAs) - Market size and forecast 2025-2030 ($ million)
Data Table on Personal digital assistants (PDAs) - Market size and forecast 2025-2030 ($ million)
Chart on Personal digital assistants (PDAs) - Year-over-year growth 2025-2030 (%)
Data Table on Personal digital assistants (PDAs) - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Device

Market opportunity by Device ($ million)
Data Table on Market opportunity by Device ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.2 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Expanding subscription bundle integration across major international digital entertainment distribution platforms
Rapid global smartphone penetration facilitating seamless mobile on demand content accessibility
Proliferation concerning comprehensive multilingual digital library catalogs satisfying diverse consumer demands

13.2 Market challenges

Rising copyright litigation regarding streaming revenue allocation models among digital publishers
Restrictive consumer consumption thresholds slowing down mainstream user adoption rate metrics
Intellectual property infringement disputes arising from unauthorized synthetic voice model training

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Rapid adoption involving automated generative AI text to speech tools
Surging consumer demand regarding exclusive immersive celebrity narrated biographical memoirs
Rising popularity surrounding condensed microlearning audio summaries targeting busy urban professionals

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Apple Inc.

Apple Inc. - Overview
Apple Inc. - Business segments
Apple Inc. - Key news
Apple Inc. - Key offerings
Apple Inc. - Segment focus
SWOT

15.5 Barnes and Noble Booksellers

Barnes and Noble Booksellers - Overview
Barnes and Noble Booksellers - Product / Service
Barnes and Noble Booksellers - Key offerings
SWOT

15.6 BookBeat AB

BookBeat AB - Overview
BookBeat AB - Product / Service
BookBeat AB - Key offerings
SWOT

15.7 Bookmate Ltd.

Bookmate Ltd. - Overview
Bookmate Ltd. - Product / Service
Bookmate Ltd. - Key offerings
SWOT

15.8 Eleven Labs Inc.

Eleven Labs Inc. - Overview
Eleven Labs Inc. - Product / Service
Eleven Labs Inc. - Key offerings
SWOT

15.9 Everand

Everand - Overview
Everand - Product / Service
Everand - Key offerings
SWOT

15.10 Google LLC

Google LLC - Overview
Google LLC - Product / Service
Google LLC - Key news
Google LLC - Key offerings
SWOT

15.11 Hoopla

Hoopla - Overview
Hoopla - Product / Service
Hoopla - Key offerings
SWOT

15.12 Legimi SA

Legimi SA - Overview
Legimi SA - Product / Service
Legimi SA - Key offerings
SWOT

15.13 OverDrive Inc.

OverDrive Inc. - Overview
OverDrive Inc. - Product / Service
OverDrive Inc. - Key offerings
SWOT

15.14 Podimo ApS

Podimo ApS - Overview
Podimo ApS - Product / Service
Podimo ApS - Key offerings
SWOT

15.15 Rakuten Kobo Inc.

Rakuten Kobo Inc. - Overview
Rakuten Kobo Inc. - Product / Service
Rakuten Kobo Inc. - Key offerings
SWOT

15.16 RBmedia

RBmedia - Overview
RBmedia - Product / Service
RBmedia - Key offerings
SWOT

15.17 Spotify Technology SA

Spotify Technology SA - Overview
Spotify Technology SA - Business segments
Spotify Technology SA - Key offerings
Spotify Technology SA - Segment focus
SWOT

15.18 Storytel AB

Storytel AB - Overview
Storytel AB - Business segments
Storytel AB - Key offerings
Storytel AB - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Audiobooks market growth will increase by USD 28557.5 million during 2026-2030.

The Audiobooks market is expected to grow at a CAGR of 30% during 2026-2030.

Audiobooks market is segmented by Type (Fiction, Non-fiction) Channel (One-time download, Subscription-based) Device (Smartphones, Laptops and tablets, Personal digital assistants (PDAs), Others)

Apple Inc., Audible Inc., Barnes and Noble Booksellers, BookBeat AB, Bookmate Ltd., Chirp, DOWNPOUR, Eleven Labs Inc., Everand, Google LLC, Hoopla, Legimi SA, Libro.fm SPC., Nextory AB, OverDrive Inc., Podimo ApS, Rakuten Kobo Inc., RBmedia, Spotify Technology SA, Storytel AB are a few of the key vendors in the Audiobooks market.

North America will register the highest growth rate of 43.7% among the other regions. Therefore, the Audiobooks market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, UK, Germany, France, Italy, Spain, The Netherlands, Brazil, Argentina, Colombia, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Expanding subscription bundle integration across major international digital entertainment distribution platforms is the driving factor this market.

The Audiobooks market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
