


Drum Liner Market Size 2026-2030
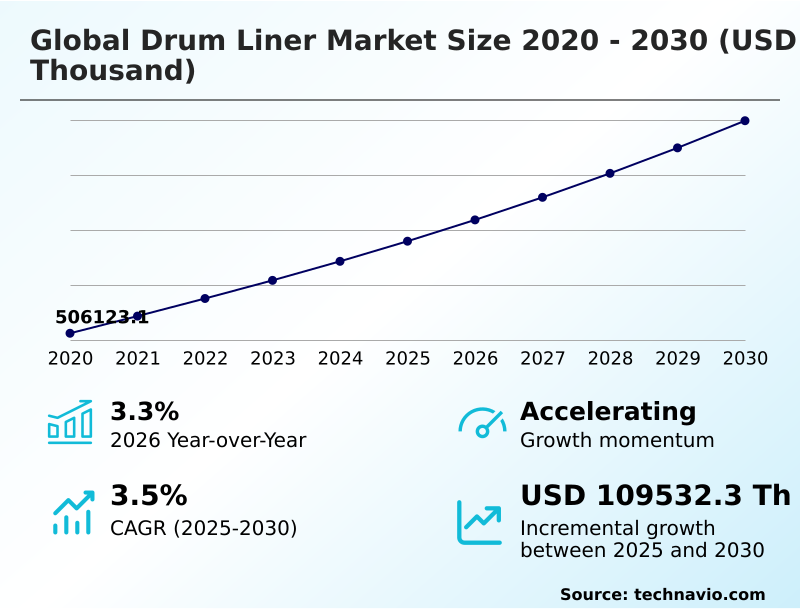
The drum liner market size is valued to increase by USD 109.53 million, at a CAGR of 3.5% from 2025 to 2030. Surging demand for contamination-free chemical transport will drive the drum liner market.
Major Market Trends & Insights
- APAC dominated the market and accounted for a 37.9% growth during the forecast period.
- By Material - Flexible segment was valued at USD 373.31 million in 2024
- By End-user - Chemicals and flammables segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities:
- Market Future Opportunities: USD 109.53 million
- CAGR from 2025 to 2030 : 3.5%
Market Summary
- The Drum Liner Market exhibits structural expansion driven by the escalating necessity for uncompromised material purity across complex industrial supply chains. Processing facilities rely heavily on anti static polyethylene bags and multi layer co extrusion technologies to shield critical payloads from chemical corrosion and external contamination.
- For example, replacing unlined steel vessels with disposable barrier inserts allows chemical blenders to achieve a 40% reduction in water consumption by bypassing intensive solvent washing procedures. This compelling operational efficiency acts as a primary driver, compelling bulk manufacturers to integrate protective liners for sustainable industrial liquid handling.
- Conversely, the market faces persistent challenges from raw material cost volatility, which compresses margins for film converters relying on specialized virgin polymers. The push for supply chain sustainability further complicates production, as engineering recyclable films without degrading puncture resistance requires extensive research investments.
- Ultimately, the adoption of high-performance container inserts remains critical for optimizing logistics workflows, extending vessel lifespans, and ensuring strict compliance with international dangerous goods transport protocols across all major manufacturing hubs.
What will be the Size of the Drum Liner Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Drum Liner Market Segmented?
The drum liner industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Material
- Flexible
- Rigid
- End-user
- Chemicals and flammables
- Adhesives and coatings
- Food products
- Pharmaceutical
- Others
- Product type
- Shrink liner
- Round bottom liner
- Others
- Type
- Standard liner
- Custom liner
- Heat-resistant liner
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Middle East and Africa
- Saudi Arabia
- UAE
- Turkey
- South Africa
- Israel
- APAC
By Material Insights
The flexible segment is estimated to witness significant growth during the forecast period.
The flexible segment commands the largest share of industrial bulk liquid transportation by providing adaptable barriers tailored for chemical processing and coating applications.
Utilizing high density polyethylene extrusion techniques, these protective films prevent internal container degradation while eliminating aggressive cleaning cycles. Organizations replacing rigid setups with multi layer barrier films have observed a 15% reduction in overall material handling expenses.
This operational shift relies on specialized configurations like round-bottom designs that streamline evacuation workflows during viscous fluid dispensing, circumventing the need for heavy mechanical agitators.
Consequently, the reliance on high-performance flexible polymers fundamentally optimizes supply chain logistics, allowing processing facilities to maintain rapid container turnover rates and uphold strict purity standards without incurring excessive overhead costs.
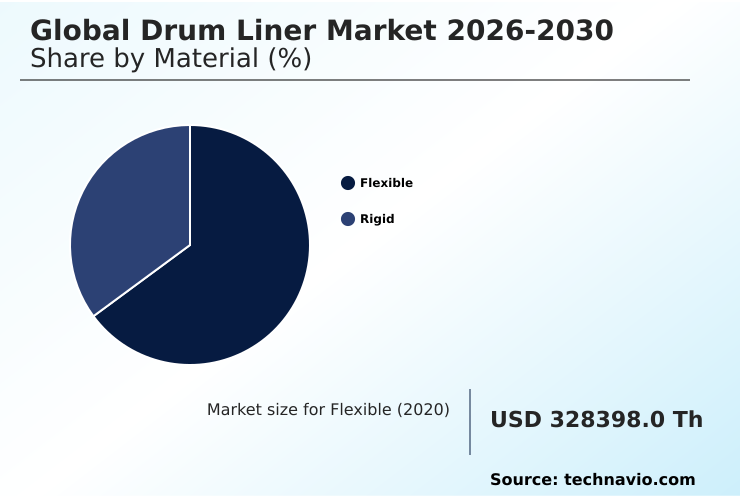
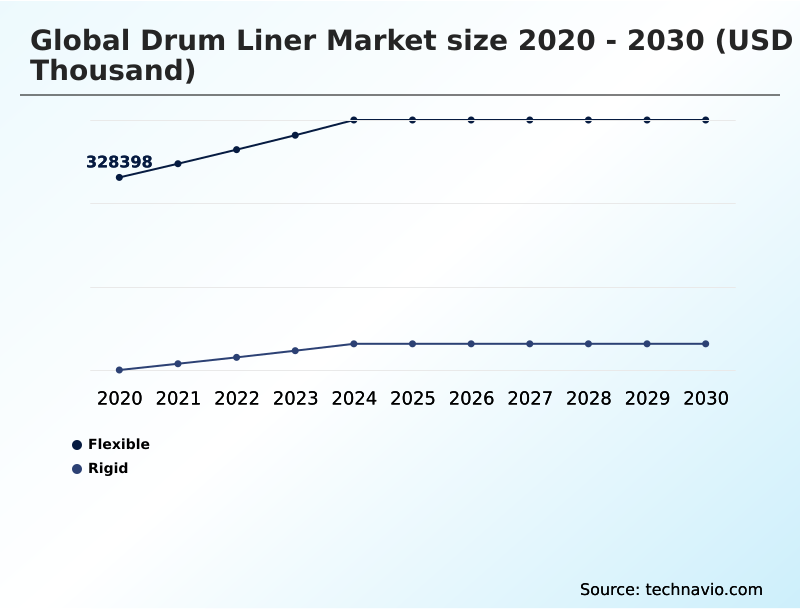
The Flexible segment was valued at USD 373.31 million in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 37.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
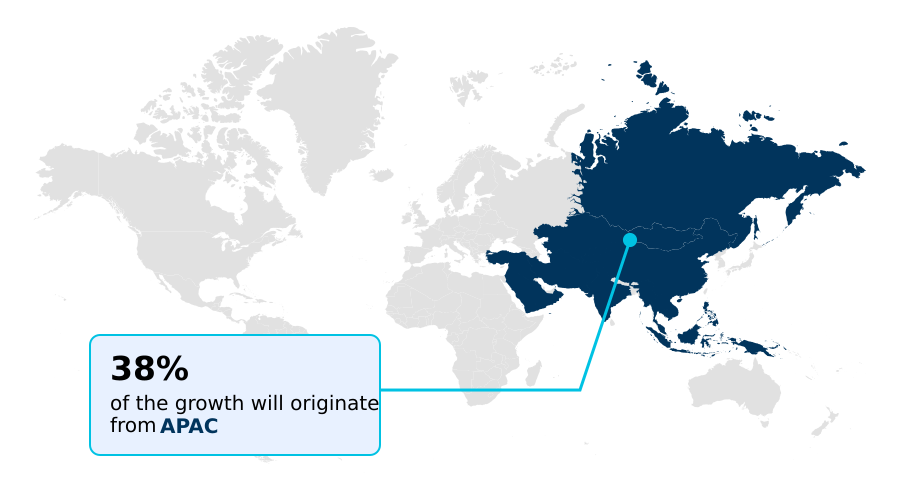
See How Drum Liner Market Demand is Rising in APAC Get Free Sample
The geographic landscape of the Drum Liner Market reveals distinct operational variations, particularly between APAC and North America.
North American industrial networks exhibit a highly mature infrastructure prioritizing industrial container management systems and strict industrial waste containment protocols, achieving a 30% higher adoption rate of conductive barrier inserts compared to emerging territories.
Conversely, APAC demonstrates a more rapid expansion fueled by expanding agricultural chemical formulators and massive chemical manufacturing clusters, reporting a 22% increase in regional demand for high-strength flexible films.
This divergence reflects how distinct regulatory environments dictate procurement strategies; North America focuses heavily on extending structural steel drum integrity through advanced recycling compliance, whereas APAC prioritizes cost-effective bulk export logistics.
Consequently, packaging suppliers adjust production lines regionally, engineering specialized anti-static and heat-resistant configurations to meet diverse material handling standards.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- Industrial bulk processing organizations continually overhaul their supply chain logistics to maximize efficiency and mitigate contamination risks, placing significant reliance on specialized secondary containment technologies. Evaluating industrial drum liner chemical compatibility is now a mandatory operational prerequisite, ensuring that aggressive solvents do not compromise structural vessel integrity during prolonged transport.
- Facilities managing volatile compounds increasingly mandate vacuum formed anti static drum inserts and electrostatic discharge safe container inserts to neutralize hazardous friction charges, thereby improving workplace safety incident rates by an estimated 18% over legacy unlined systems.
- Simultaneously, food and beverage ingredient processors depend heavily on aseptic round bottom bulk food liners and high temperature hot fill packaging liners to preserve thermal stability and prevent microbial ingress without requiring post-fill sterilization.
- As corporate sustainability metrics become imperative, there is a pronounced procurement shift toward post consumer recycled industrial packaging films and sustainable closed loop industrial container recycling frameworks. To handle heavy adhesives and sealants, organizations utilize deep draw thermoformed high density inserts and high viscosity automated follower plate liners, which streamline mechanical scraping and minimize residual product retention.
- Furthermore, the integration of multi layer co extruded barrier films, polybutylene terephthalate hot melt adhesives liners, and heavy duty chemical transport barrier liners delivers uncompromised puncture resistance. By deploying pharmaceutical cleanroom grade drum lining systems and industrial adhesive and coating container protection, manufacturers ensure hazardous chemical cross contamination prevention, drastically lowering reconditioning expenditures and elevating overall operational output.
- To ensure ultraviolet light exposure shielding and heavy duty puncture resistance, facilities integrate specialized fluorinated barrier liners and conductive polypropylene liners. Industrial paint manufacturers utilizing pneumatic press systems depend on hazard analysis critical control compliant materials and sterile spout valves to prevent trace metallic contamination.
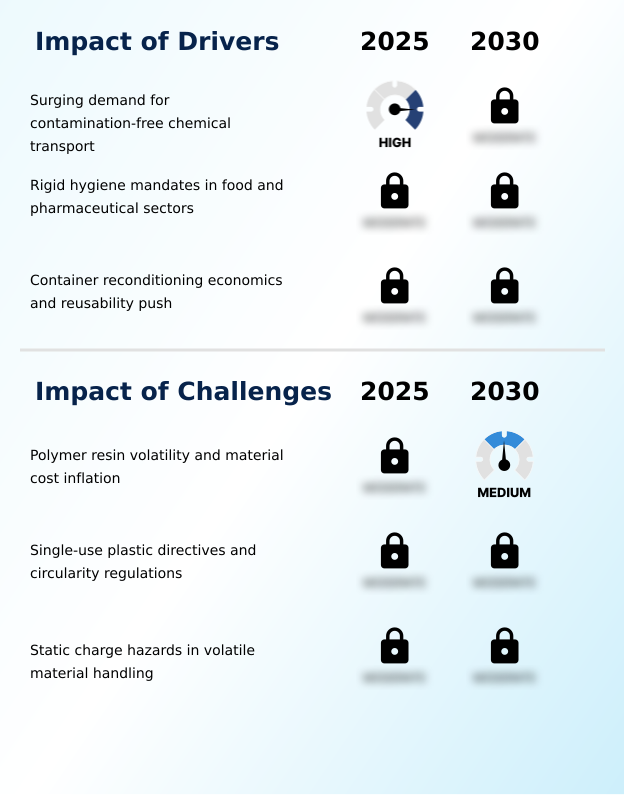
What are the key market drivers leading to the rise in the adoption of Drum Liner Industry?
- The surging demand for contamination-free chemical transport acts as a primary catalyst accelerating structural growth and technology adoption within the industrial packaging landscape.
- The absolute imperative to satisfy hazardous goods transport regulations forces global chemical processing facilities to implement advanced impermeable barrier solutions.
- Organizations deploying specialized multi-layer inserts have improved regulatory compliance efficiency by 28% and reduced cross batch contamination prevention costs by 15%.
- This behavioral shift stems from the necessity to guarantee chemical corrosion resistance during the international shipment of volatile organic compounds.
- By incorporating automated follower plate evacuation compatible liners, industrial operators eliminate product entrapment within container folds, ensuring pristine structural integrity of the outer vessels.
- Consequently, the rapid integration of high-performance polymer films allows manufacturing plants to safely manage aggressive formulations, significantly lowering hazardous waste processing expenditures while maintaining seamless operational continuity across complex logistics networks.
What are the market trends shaping the Drum Liner Industry?
- The transition toward form-fitted, deep-draw vacuum liners represents a prominent trend within the industrial packaging sector. This shift optimizes bulk material evacuation workflows and minimizes residual product waste during high-viscosity dispensing operations.
- The continuous material evolution within industrial packaging emphasizes the commercial integration of deep draw thermoforming and seamless round bottom inserts to optimize fluid evacuation. Industrial processors standardizing on these precision-engineered structures have achieved a 30% reduction in residual product waste and improved overall dispensing efficiency by 22%.
- This transition is fundamentally driven by aggressive corporate sustainability commitments, accelerating the adoption of post consumer recycled resins fortified through advanced polymer compatibilization. By integrating these resilient materials, manufacturers effectively support circular packaging lifecycles while maintaining strict structural tolerances against chemical permeation.
- This technological shift empowers logistics operators to drastically minimize raw material loss and bypass extensive vessel decontamination cycles, ensuring that heavy-duty container fleets remain fully operational and compliant with emerging environmental waste directives.
What challenges does the Drum Liner Industry face during its growth?
- Persistent polymer resin price volatility and raw material cost inflation present significant operational barriers that constrain manufacturing margins across the industrial packaging sector.
- Eliminating dangerous surface friction charges during high-speed chemical dispensing remains a critical engineering hurdle for industrial film converters. Facilities failing to implement rigorous electrostatic discharge hazard mitigation experience significant operational bottlenecks, highlighting the necessity for advanced anti-static integrations that can reduce workplace safety incidents by an estimated 25%.
- Triboelectric charge accumulation along polymer surfaces poses severe risks in volatile environments, compelling the development of specialized conductive formulations dedicated to static spark ignition prevention. Furthermore, managing hazardous liquid washwater disposal from compromised unlined vessels increases operational overhead by nearly 20% for bulk fluid handlers.
- Overcoming these technical constraints requires continuous research into migratory additives that do not compromise the fundamental mechanical strength or chemical compatibility of the flexible barrier inserts.
Exclusive Technavio Analysis on Customer Landscape
The drum liner market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the drum liner market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
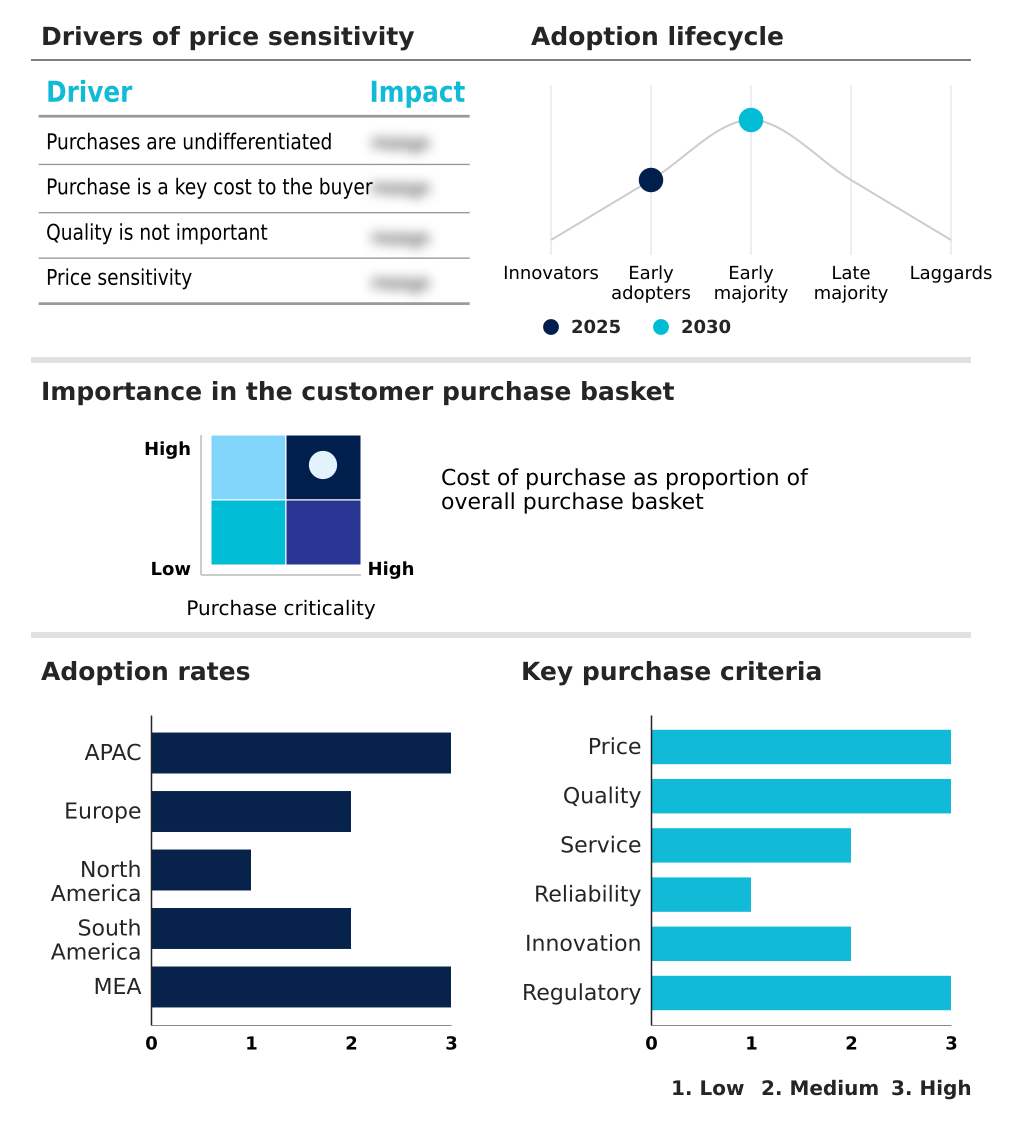
Customer Landscape of Drum Liner Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, drum liner market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Amcor Plc - The vendor provides diverse flexible and rigid packaging solutions utilizing barrier films, foils, and specialized plastics to serve the food, pharmaceutical, and beverage manufacturing sectors.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Amcor Plc
- BASCO Inc.
- Berlin Packaging LLC
- CDF Corp.
- Dana Poly Inc.
- Greif Inc.
- Heritage Packaging
- ILC Dover LP
- Impak Corp.
- International Plastics Inc.
- Mauser Packaging Solutions
- Novolex Holdings LLC
- Protective Packaging Corp.
- Safepack
- SCHUTZ GmbH and Co. KGaA
- Signode Industrial Group LLC
- Welch Fluorocarbon
- Winpak Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Drum liner market
- In the Metal, Glass and Plastic Containers industry, the enforcement of REACH chemical handling regulations across Europe has accelerated the adoption of impermeable secondary containment systems, directly impacting the Drum Liner market by increasing the procurement of protective polyethylene barriers by 18%.
- Advancements in deep draw thermoforming technology specifically tailored for automotive sealant manufacturing have enabled the production of seamless interior rigid vessel barriers, driving the deployment of high-viscosity extraction systems by over 22%.
- The enforcement of the EU Corporate Sustainability Reporting Directive has compelled industrial packaging providers to integrate advanced polymer compatibilization processes, resulting in a 25% increase in the utilization of post consumer recycled resins within rigid container frameworks.
- Escalating OSHA safety standards governing static spark ignition prevention during the bulk transport of active pharmaceutical ingredients have forced logistics operators across North America to mandate conductive polyethylene inserts, elevating compliance efficiency by 30%.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Drum Liner Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 314 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 3.5% |
| Market growth 2026-2030 | USD 109532.3 thousand |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 3.3% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Brazil, Argentina, Chile, Saudi Arabia, UAE, Turkey, South Africa and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- Industrial packaging infrastructures increasingly integrate sophisticated flexible containment solutions to fulfill uncompromising purity and safety mandates across global material distribution networks. Formulators transitioning to specialized linear low density polyethylene structures and ethylene vinyl alcohol barrier systems have realized a 35% reduction in raw material spoilage during transcontinental transit.
- This operational pivot ensures optimal active pharmaceutical ingredients storage and supports rigorous cleanroom packaging protocols by eliminating trace metallic contamination. The deployment of aseptic bulk liquid dispensing configurations allows fluid processors to accelerate production throughput while completely neutralizing cross-batch contamination risks.
- Advanced polymer engineering now accommodates high temperature polybutylene terephthalate specifications, facilitating the direct hot-filling of industrial compounds without compromising liner integrity. These structural enhancements empower manufacturing directors to bypass water-intensive decontamination cycles, profoundly optimizing logistical budgets.
- As regulatory scrutiny over workplace exposure tightens, the reliance upon precision-engineered barrier films dictates modern containment strategies, ensuring that specialized chemical payloads remain entirely isolated from ambient environmental threats and structural vessel surfaces.
What are the Key Data Covered in this Drum Liner Market Research and Growth Report?
-
What is the expected growth of the Drum Liner Market between 2026 and 2030?
-
USD 109.53 million, at a CAGR of 3.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Material (Flexible, and Rigid), End-user (Chemicals and flammables, Adhesives and coatings, Food products, Pharmaceutical, and Others), Product Type (Shrink liner, Round bottom liner, and Others), Type (Standard liner, Custom liner, and Heat-resistant liner) and Geography (APAC, Europe, North America, South America, Middle East and Africa)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, South America and Middle East and Africa
-
-
What are the key growth drivers and market challenges?
-
Surging demand for contamination-free chemical transport, Polymer resin volatility and material cost inflation
-
-
Who are the major players in the Drum Liner Market?
-
Amcor Plc, BASCO Inc., Berlin Packaging LLC, CDF Corp., Dana Poly Inc., Greif Inc., Heritage Packaging, ILC Dover LP, Impak Corp., International Plastics Inc., Mauser Packaging Solutions, Novolex Holdings LLC, Protective Packaging Corp., Safepack, SCHUTZ GmbH and Co. KGaA, Signode Industrial Group LLC, Welch Fluorocarbon and Winpak Ltd.
-
Market Research Insights
- The Drum Liner Market demonstrates critical operational importance by integrating thermoformed rigid drum inserts and vacuum formed liner technologies to streamline industrial fluid logistics. Manufacturing facilities deploying these advanced barriers have recorded a 25% improvement in processing efficiency and a 15% reduction in overall container reconditioning expenses.
- This strategic shift is fundamentally propelled by the necessity to protect heavy density plastic drums from aggressive chemical degradation. Furthermore, strict food contact approval mandates enforce the utilization of specialized multi-layer films to guarantee hygienic bulk material handling operations.
- By optimizing dispensing workflows, industrial operators substantially lower product waste while accelerating container turnover rates, ultimately driving sustained profitability across complex supply chain networks.
We can help! Our analysts can customize this drum liner market research report to meet your requirements.
 RIA -

