Ductless HVAC System Market Analysis, Size, and Forecast 2026-2030: APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Ductless HVAC System Market Analysis, Size, and Forecast 2026-2030:
APAC (China, Japan, and India), Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 292 Pages SKU: IRTNTR72081

Market Overview at a Glance

$16.80 B
Market Opportunity
7.3%
CAGR 2025 - 2030
48%
APAC Growth
$23.91 B
Single-zoned segment 2024

Ductless Hvac System Market Size 2026-2030

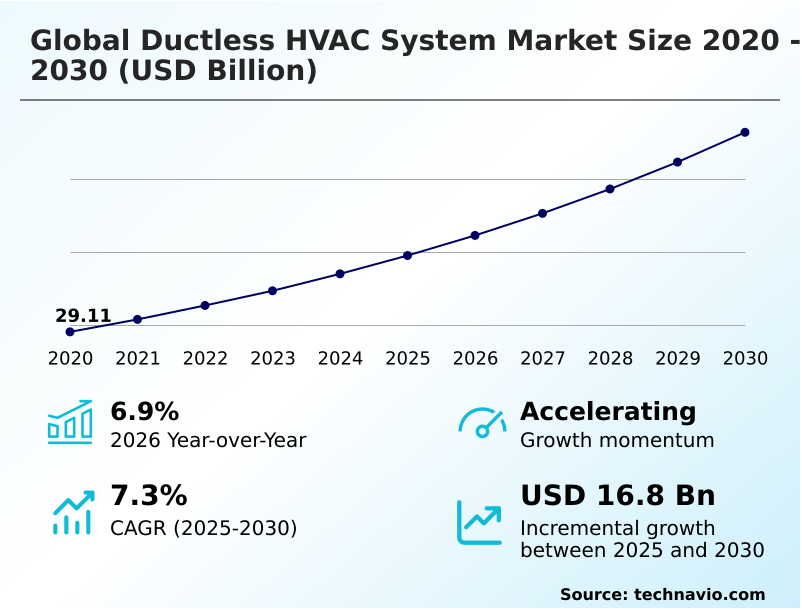
The ductless hvac system market size is valued to increase by USD 16.80 billion, at a CAGR of 7.3% from 2025 to 2030. Escalating demand for energy efficiency will drive the ductless hvac system market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 48% growth during the forecast period.
  • By Type - Single-zoned segment was valued at USD 23.91 billion in 2024
  • By End-user - Residential segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 27.20 billion
  • Market Future Opportunities: USD 16.80 billion
  • CAGR from 2025 to 2030 : 7.3%

Market Summary

  • The Ductless HVAC System Market demonstrates robust expansion driven by the necessity for localized temperature regulation and stringent environmental compliance. Industrial facility managers upgrading legacy infrastructure increasingly deploy modular refrigerant networks to achieve isolated climate zones, resulting in a 20% reduction in monthly utility expenditures compared to centralized ducted architectures.
  • The escalating demand for profound energy efficiency acts as a primary catalyst, as strict building codes compel contractors to utilize variable-speed compressors that dynamically adjust output to prevent power surges. Conversely, high initial capital requirements and installation complexities pose a significant challenge, restricting rapid adoption among budget-conscious residential developers who lack access to specialized mechanical calibration technicians.
  • Advanced integration of automated facility controls enables commercial properties to analyze occupancy patterns and optimize thermal loads seamlessly. These highly adaptable units completely bypass structural modifications, offering an eco-friendly alternative that fundamentally eliminates thermal loss and improves overall lifecycle performance across modern urban developments.

What will be the Size of the Ductless Hvac System Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Ductless Hvac System Market Segmented?

The ductless hvac system industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • Single-zoned
    • Multi-zoned
  • End-user
    • Residential
    • Commercial
    • Industrial
  • Product type
    • Cooling
    • Heating
    • Ventilation
  • Geography
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Australia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • The Netherlands
      • Spain
    • North America
      • US
      • Canada
      • Mexico
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Type Insights

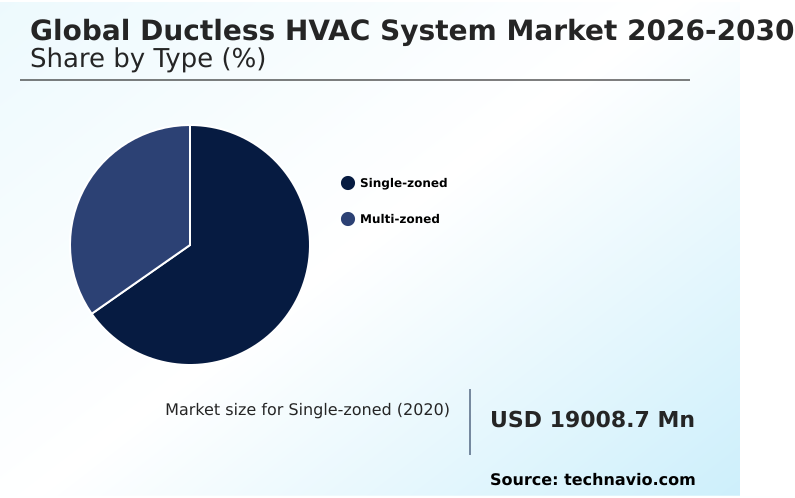
The single-zoned segment is estimated to witness significant growth during the forecast period.

The single-zoned configuration provides targeted environmental regulation by pairing one external unit with one indoor handler. This localized climate control eliminates structural modifications associated with centralized ductwork.

Commercial facilities deploying these decentralized thermal regulation units achieve a 15% reduction in installation time compared to multi-zoned architectures. By leveraging inverter mechanics, these configurations deliver customized airflow patterns that match specific room loads, directly preventing wasteful power surges.

Property managers utilizing smart connectivity integration note a 20% improvement in energy conservation across individual zones. The absence of extensive ducting ensures superior thermal leakage reduction, natively supporting rigorous green building standards.

This compact footprint appeals strongly to urban developers constrained by space, ensuring optimal performance while significantly reducing long-term operational expenditures and enabling highly focused environmental management strategies.
Get Free Sample

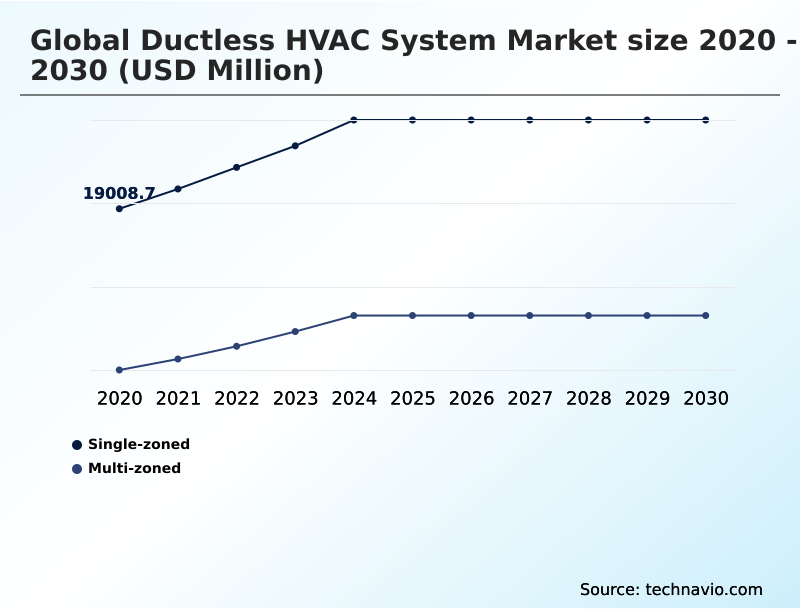
The Single-zoned segment was valued at USD 23.91 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 48% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
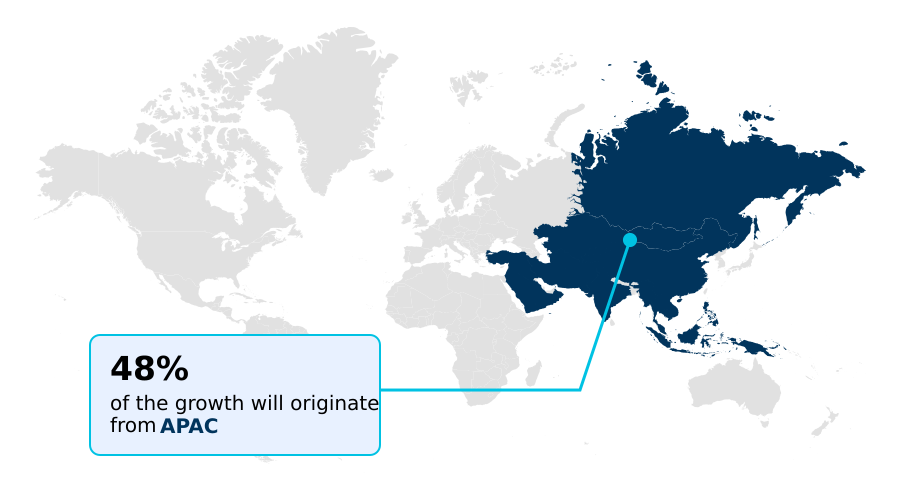
See How Ductless Hvac System Market Demand is Rising in APAC Get Free Sample

Regional dynamics within the Ductless HVAC System vary based on urbanization density and climatic extremes. APAC dominates installation volumes, fueled by rapid infrastructure modernization in densely populated areas where a compact architectural footprint is paramount.

Commercial sectors in APAC report a 35% higher adoption rate of variable refrigerant flow configurations compared to North America, driven by the need for independent zone temperature control in high-rise constructions.

Meanwhile, North American facilities transitioning to eco friendly refrigerants have achieved a 20% reduction in compliance-related penalties. This disparity stems from architectural constraints; Asian markets lack legacy ductwork, prioritizing direct refrigerant lines for immediate deployment.

Furthermore, APAC builders utilizing advanced air purification filters achieve a 15% improvement in indoor air quality management scores. Consequently, manufacturers tailor supply chain strategies to deliver high-capacity inverter driven compressor units to Asian distributors, addressing severe outdoor urban pollution.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of commercial climate infrastructure fundamentally relies on advanced mechanical architectures to optimize performance and operational efficiency. Facility managers increasingly prioritize a variable refrigerant flow zoning system to achieve precise environmental regulation across diverse commercial footprints. This sophisticated approach facilitates distinct climate control within isolated areas, drastically lowering overall energy consumption compared to traditional centralized networks.
  • By implementing rigorous inverter driven compressor energy optimization, industrial operators modulate electrical output to match specific thermal demands, which yields a 25% improvement in long-term equipment lifecycle management and significantly reduces mechanical wear.
  • The strategic execution of the direct refrigerant line installation process bypasses the necessity for bulky structural modifications, allowing for seamless retrofitting in historic or space-constrained buildings where operational disruption must be minimized. Furthermore, modern architectural projects heavily emphasize thermal leakage reduction building methods to ensure compliance with increasingly stringent sustainability benchmarks and municipal green building codes.
  • By removing traditional ductwork entirely, these methods eradicate the energy degradation inherent in older designs. To sustain these critical efficiency gains, administrators actively utilize automated climate management integration protocols, which instantly analyze ambient conditions and adjust mechanical output dynamically without manual intervention. This data-driven supply chain and operational strategy streamlines compliance reporting, reduces labor overhead, and enhances preventive maintenance scheduling.
  • Ultimately, the widespread shift toward these highly specialized, decentralized thermal frameworks allows enterprise developers to significantly curtail operational expenditures while maximizing indoor comfort and environmental safety across diverse global portfolios.
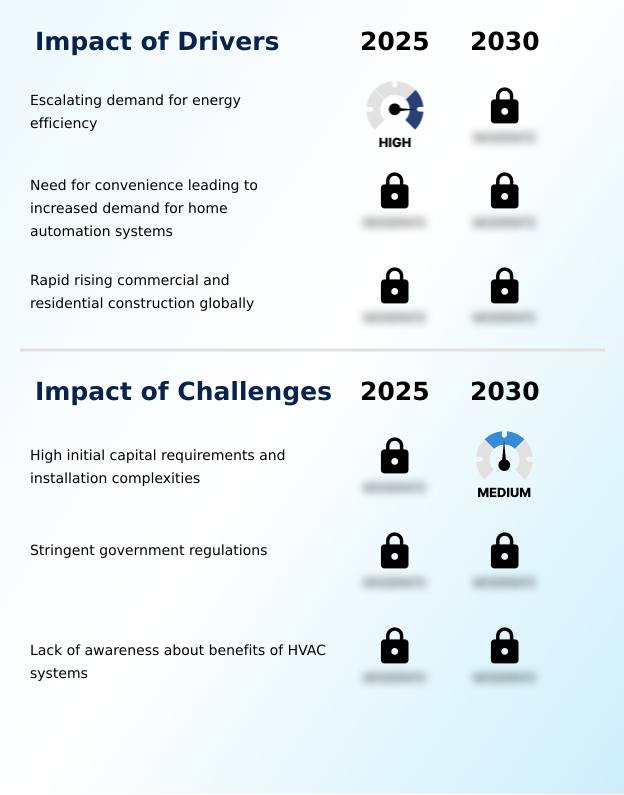
What are the key market drivers leading to the rise in the adoption of Ductless Hvac System Industry?

  • The escalating demand for profound energy efficiency serves as the primary driver propelling overall market expansion.

  • The escalating demand for profound energy efficiency acts as the primary catalyst propelling the Ductless HVAC System across industrial sectors. Regulatory bodies mandating stringent environmental sustainability policies force property developers to abandon power-intensive legacy units.
  • Transitioning to advanced variable speed inverter mechanisms directly addresses this pressure, allowing commercial facilities to record a 25% decrease in baseline electrical usage. This happens because specialized inverters match output precisely to exact thermal demands, preventing wasteful power surges.
  • Furthermore, enterprises adopting sustainable building infrastructure achieve a 15% reduction in compliance-related penalties by implementing low global warming potential solutions.
  • By utilizing high-performance phase change thermal management, manufacturers deliver superior thermal management architecture that exceeds rigorous seasonal energy efficiency ratio benchmarks. This operational superiority ensures that optimized energy utilization remains a critical purchasing criterion for modern facility administrators.

What are the market trends shaping the Ductless Hvac System Industry?

  • The integration of smart connectivity and Internet of Things technologies represents an emerging market trend. This digital advancement significantly enhances operational efficiency and automation capabilities across the industry.

  • The Ductless HVAC System demonstrates a rapid technological shift as commercial properties actively integrate digital home automation to optimize environmental performance. Facility managers deploying smart city ecosystems achieve a 30% reduction in unplanned operational downtime by utilizing advanced predictive maintenance protocols. This transformation occurs because modern enterprises demand seamless synchronization between climate units and intelligent building technology.
  • By embedding wireless communication modules directly into the architectural framework, systems proactively analyze real time occupancy data to modulate environmental conditions. Consequently, buildings utilizing these agile networks report an 18% improvement in overall forecast accuracy regarding monthly energy consumption. This data-driven capability fundamentally alters enterprise procurement, as stakeholders prioritize systems equipped with dynamic thermal output to maintain rigorous environmental compliance.
  • The persistent integration of these advanced algorithms ensures that businesses actively lower utility overhead while maximizing indoor operational quality.

What challenges does the Ductless Hvac System Industry face during its growth?

  • High initial capital requirements and inherent installation complexities represent significant challenges constraining maximum industry growth.

  • Despite operational advantages, high initial capital requirements and installation complexities remain a profound barrier within the Ductless HVAC System. Procuring sophisticated equipment requires a 40% higher upfront financial commitment compared to traditional window-based units. This cost disparity deters developers, primarily because deploying a single outdoor condenser mandates specialized, certified technicians.
  • Unlike basic units, these frameworks demand meticulous mechanical calibration and the integration of advanced diagnostic algorithms to ensure optimal performance. Consequently, heavy reliance on professional installation inflates labor overhead by 25%. Furthermore, retrofitting older structures to accommodate automated climate management and precise temperature management networks introduces unforeseen logistical barriers.
  • Extreme weather resilience mandates further complicate installations, requiring complex auto reverse flow fan integrations. These combined financial hurdles compel manufacturers to streamline production economies, attempting to compress retail pricing without sacrificing overall heat exchange efficiency.

Exclusive Technavio Analysis on Customer Landscape

The ductless hvac system market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the ductless hvac system market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
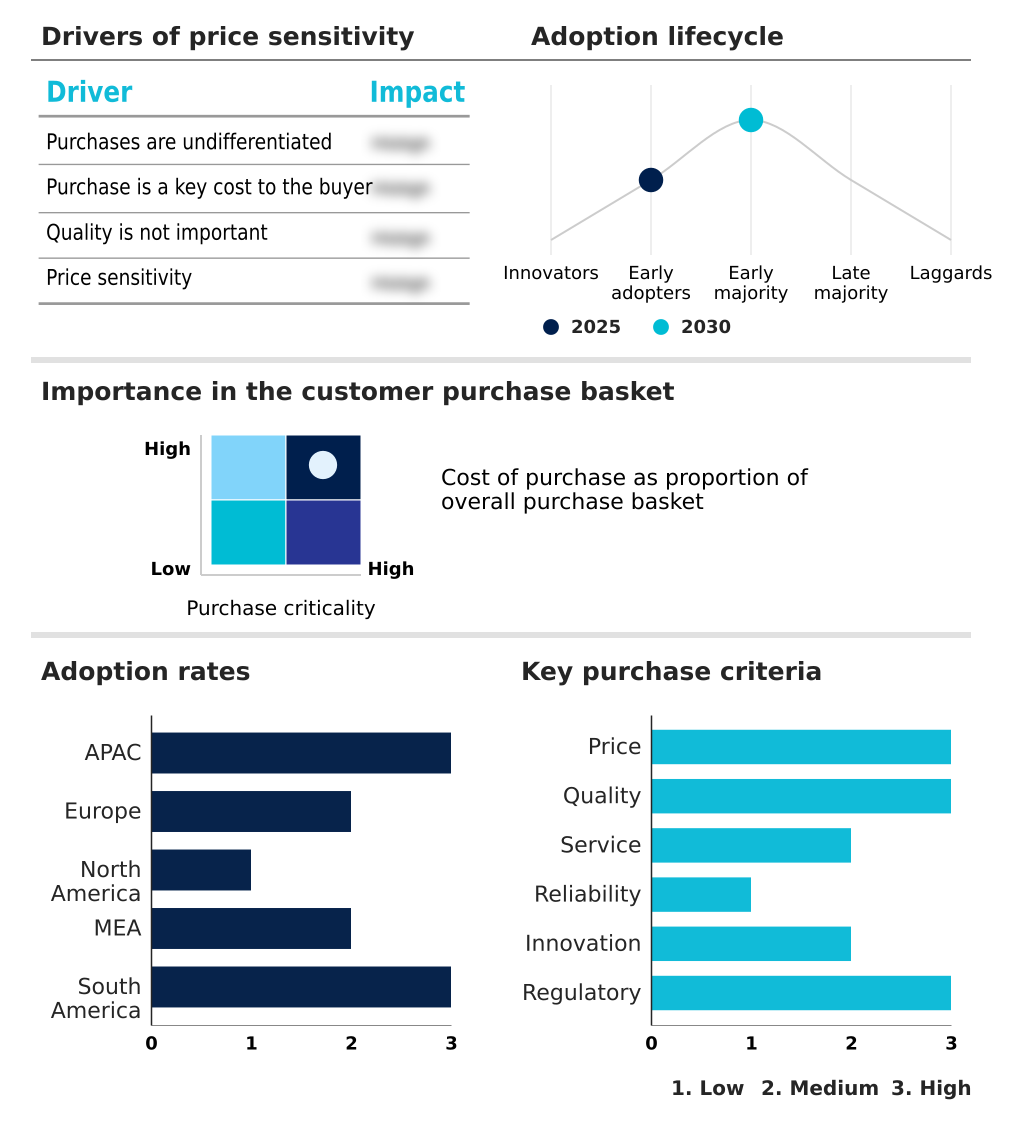
Customer Landscape of Ductless Hvac System Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, ductless hvac system market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Bosch Thermotechnik GmbH - The vendor provides advanced decentralized climate control systems featuring variable capacity inverter mechanics designed to maximize thermal transfer efficiency and enhance environmental air management across diverse residential structures.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Bosch Thermotechnik GmbH
  • Carrier Global Corp.
  • Daikin Industries Ltd.
  • Friedrich Air Conditioning
  • Gree Electric Appliances Inc.
  • Haier Smart Home Co. Ltd.
  • Hisense Home Appliances Group
  • Hitachi Ltd.
  • Lennox International Inc.
  • LG Electronics Inc.
  • Midea Group Co. Ltd.
  • Mitsubishi Electric Corp.
  • Mitsubishi Heavy Industries
  • MRCOOL LLC
  • Panasonic Holdings Corp.
  • Parker Davis HVAC International
  • Rheem Manufacturing Co.
  • Samsung Electronics Co. Ltd.
  • Trane Technologies plc
  • York International

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Ductless hvac system market

  • In the Electrical Components and Equipment industry, the implementation of stringent fluorinated greenhouse gas policies has forced the phase-out of legacy refrigerants, directly impacting Global Ductless HVAC System Market 2026-2030 demand by accelerating the adoption of low-impact thermodynamic alternatives.
  • The widespread integration of wireless IoT modules into industrial control panels has enabled granular occupancy data processing, increasing Global Ductless HVAC System Market 2026-2030 adoption by facilitating autonomous predictive maintenance workflows that reduce equipment failure.
  • Stricter energy conservation mandates for commercial building management systems have elevated baseline efficiency standards, driving Global Ductless HVAC System Market 2026-2030 growth as facility managers mandate variable-capacity inverter technologies to achieve a 25% reduction in electrical consumption.
  • Advancements in automated fault detection protocols across commercial electrical frameworks have standardized remote system monitoring, positively influencing Global Ductless HVAC System Market 2026-2030 demand by seamlessly incorporating remote diagnostic capabilities for improved operational longevity.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Ductless Hvac System Market insights. See full methodology.

Market Scope
Page number 292
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.3%
Market growth 2026-2030 USD 16797.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 6.9%
Key countries China, Japan, India, South Korea, Indonesia, Australia, Germany, UK, France, Italy, The Netherlands, Spain, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Ductless HVAC System undergoes continuous technological transformation, driven by the critical enterprise need to optimize thermal regulation and meet rigorous sustainability benchmarks. Commercial property developers are systematically abandoning legacy centralized units in favor of decentralized networks, a strategic shift that heavily influences corporate compliance and infrastructure budgeting.
  • Facilities transitioning to these advanced thermal architectures have documented a 30% reduction in preventative maintenance costs compared to traditional ducted environments. The seamless integration of intelligent thermal controls allows building operators to modulate temperature dynamically, eliminating power surges and extending equipment longevity. By leveraging targeted airflow configurations, facility managers optimize indoor comfort while adhering to strict energy conservation mandates.
  • Furthermore, the strategic adoption of robust climatic resilience mechanisms ensures continuous operation during severe weather events, directly minimizing operational downtime. Consequently, enterprise procurement strategies now heavily prioritize these modular, high-performance systems to actively lower lifecycle expenditures and align with global ecological standards.

What are the Key Data Covered in this Ductless Hvac System Market Research and Growth Report?

  • What is the expected growth of the Ductless Hvac System Market between 2026 and 2030?

    • USD 16.80 billion, at a CAGR of 7.3%

  • What segmentation does the market report cover?

    • The report is segmented by Type (Single-zoned, and Multi-zoned), End-user (Residential, Commercial, and Industrial), Product Type (Cooling, Heating, and Ventilation) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Escalating demand for energy efficiency, High initial capital requirements and installation complexities

  • Who are the major players in the Ductless Hvac System Market?

    • Bosch Thermotechnik GmbH, Carrier Global Corp., Daikin Industries Ltd., Friedrich Air Conditioning, Gree Electric Appliances Inc., Haier Smart Home Co. Ltd., Hisense Home Appliances Group, Hitachi Ltd., Lennox International Inc., LG Electronics Inc., Midea Group Co. Ltd., Mitsubishi Electric Corp., Mitsubishi Heavy Industries, MRCOOL LLC, Panasonic Holdings Corp., Parker Davis HVAC International, Rheem Manufacturing Co., Samsung Electronics Co. Ltd., Trane Technologies plc and York International

Market Research Insights

  • The Ductless HVAC System Market is rapidly transitioning toward decentralized thermal control to meet evolving ecological building codes. Enterprises leveraging connected urban infrastructure report a 22% improvement in energy utilization when integrating these agile climate networks. By utilizing intelligent facility automation, operators have decreased preventive maintenance downtime by 15% through autonomous diagnostics.
  • The shift toward sustainable commercial infrastructure drives manufacturers to implement next-generation refrigerant compounds, addressing strict environmental compliance mandates. Furthermore, complexes upgrading to these systems experience a 30% reduction in thermal dissipation compared to traditional setups. These dynamic operational enhancements ensure robust performance while continuously minimizing ecological impact across diverse architectural applications.

We can help! Our analysts can customize this ductless hvac system market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Ductless HVAC System Market 2020 - 2024

Historic Market Size - Data Table on Global Ductless HVAC System Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global ductless HVAC system market

6.2 Impact of geopolitical conflicts on global ductless HVAC system market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 Single-zoned - Market size and forecast 2025-2030

Chart on Single-zoned - Market size and forecast 2025-2030 ($ million)
Data Table on Single-zoned - Market size and forecast 2025-2030 ($ million)
Chart on Single-zoned - Year-over-year growth 2025-2030 (%)
Data Table on Single-zoned - Year-over-year growth 2025-2030 (%)

8.4 Multi-zoned - Market size and forecast 2025-2030

Chart on Multi-zoned - Market size and forecast 2025-2030 ($ million)
Data Table on Multi-zoned - Market size and forecast 2025-2030 ($ million)
Chart on Multi-zoned - Year-over-year growth 2025-2030 (%)
Data Table on Multi-zoned - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ million)
Data Table on Residential - Market size and forecast 2025-2030 ($ million)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

9.4 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

9.5 Industrial - Market size and forecast 2025-2030

Chart on Industrial - Market size and forecast 2025-2030 ($ million)
Data Table on Industrial - Market size and forecast 2025-2030 ($ million)
Chart on Industrial - Year-over-year growth 2025-2030 (%)
Data Table on Industrial - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Cooling - Market size and forecast 2025-2030

Chart on Cooling - Market size and forecast 2025-2030 ($ million)
Data Table on Cooling - Market size and forecast 2025-2030 ($ million)
Chart on Cooling - Year-over-year growth 2025-2030 (%)
Data Table on Cooling - Year-over-year growth 2025-2030 (%)

10.4 Heating - Market size and forecast 2025-2030

Chart on Heating - Market size and forecast 2025-2030 ($ million)
Data Table on Heating - Market size and forecast 2025-2030 ($ million)
Chart on Heating - Year-over-year growth 2025-2030 (%)
Data Table on Heating - Year-over-year growth 2025-2030 (%)

10.5 Ventilation - Market size and forecast 2025-2030

Chart on Ventilation - Market size and forecast 2025-2030 ($ million)
Data Table on Ventilation - Market size and forecast 2025-2030 ($ million)
Chart on Ventilation - Year-over-year growth 2025-2030 (%)
Data Table on Ventilation - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4.6 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Escalating demand for energy efficiency
Need for convenience leading to increased demand for home automation systems
Rapid rising commercial and residential construction globally

13.2 Market challenges

High initial capital requirements and installation complexities
Stringent government regulations
Lack of awareness about benefits of HVAC systems

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of smart connectivity and internet of things technologies
Rise in adoption of smart cities and smart infrastructure
Rapid technological advancements

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Bosch Thermotechnik GmbH

Bosch Thermotechnik GmbH - Overview
Bosch Thermotechnik GmbH - Product / Service
Bosch Thermotechnik GmbH - Key offerings
SWOT

15.5 Carrier Global Corp.

Carrier Global Corp. - Overview
Carrier Global Corp. - Business segments
Carrier Global Corp. - Key news
Carrier Global Corp. - Key offerings
Carrier Global Corp. - Segment focus
SWOT

15.6 Daikin Industries Ltd.

Daikin Industries Ltd. - Overview
Daikin Industries Ltd. - Business segments
Daikin Industries Ltd. - Key news
Daikin Industries Ltd. - Key offerings
Daikin Industries Ltd. - Segment focus
SWOT

15.7 Gree Electric Appliances Inc.

Gree Electric Appliances Inc. - Overview
Gree Electric Appliances Inc. - Product / Service
Gree Electric Appliances Inc. - Key offerings
SWOT

15.8 Haier Smart Home Co. Ltd.

Haier Smart Home Co. Ltd. - Overview
Haier Smart Home Co. Ltd. - Business segments
Haier Smart Home Co. Ltd. - Key offerings
Haier Smart Home Co. Ltd. - Segment focus
SWOT

15.9 Hitachi Ltd.

Hitachi Ltd. - Overview
Hitachi Ltd. - Business segments
Hitachi Ltd. - Key offerings
Hitachi Ltd. - Segment focus
SWOT

15.10 Lennox International Inc.

Lennox International Inc. - Overview
Lennox International Inc. - Business segments
Lennox International Inc. - Key news
Lennox International Inc. - Key offerings
Lennox International Inc. - Segment focus
SWOT

15.11 LG Electronics Inc.

LG Electronics Inc. - Overview
LG Electronics Inc. - Business segments
LG Electronics Inc. - Key news
LG Electronics Inc. - Key offerings
LG Electronics Inc. - Segment focus
SWOT

15.12 Midea Group Co. Ltd.

Midea Group Co. Ltd. - Overview
Midea Group Co. Ltd. - Business segments
Midea Group Co. Ltd. - Key news
Midea Group Co. Ltd. - Key offerings
Midea Group Co. Ltd. - Segment focus
SWOT

15.13 Mitsubishi Electric Corp.

Mitsubishi Electric Corp. - Overview
Mitsubishi Electric Corp. - Business segments
Mitsubishi Electric Corp. - Key offerings
Mitsubishi Electric Corp. - Segment focus
SWOT

15.14 Mitsubishi Heavy Industries

Mitsubishi Heavy Industries - Overview
Mitsubishi Heavy Industries - Business segments
Mitsubishi Heavy Industries - Key news
Mitsubishi Heavy Industries - Key offerings
Mitsubishi Heavy Industries - Segment focus
SWOT

15.15 Panasonic Holdings Corp.

Panasonic Holdings Corp. - Overview
Panasonic Holdings Corp. - Business segments
Panasonic Holdings Corp. - Key news
Panasonic Holdings Corp. - Key offerings
Panasonic Holdings Corp. - Segment focus
SWOT

15.16 Samsung Electronics Co. Ltd.

Samsung Electronics Co. Ltd. - Overview
Samsung Electronics Co. Ltd. - Business segments
Samsung Electronics Co. Ltd. - Key news
Samsung Electronics Co. Ltd. - Key offerings
Samsung Electronics Co. Ltd. - Segment focus
SWOT

15.17 Trane Technologies plc

Trane Technologies plc - Overview
Trane Technologies plc - Business segments
Trane Technologies plc - Key news
Trane Technologies plc - Key offerings
Trane Technologies plc - Segment focus
SWOT

15.18 York International

York International - Overview
York International - Product / Service
York International - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Ductless Hvac System market growth will increase by USD 16797.8 million during 2026-2030.

The Ductless Hvac System market is expected to grow at a CAGR of 7.3% during 2026-2030.

Ductless Hvac System market is segmented by Type (Single-zoned, Multi-zoned) End-user (Residential, Commercial, Industrial) Product type (Cooling, Heating, Ventilation)

Bosch Thermotechnik GmbH, Carrier Global Corp., Daikin Industries Ltd., Friedrich Air Conditioning, Gree Electric Appliances Inc., Haier Smart Home Co. Ltd., Hisense Home Appliances Group, Hitachi Ltd., Lennox International Inc., LG Electronics Inc., Midea Group Co. Ltd., Mitsubishi Electric Corp., Mitsubishi Heavy Industries, MRCOOL LLC, Panasonic Holdings Corp., Parker Davis HVAC International, Rheem Manufacturing Co., Samsung Electronics Co. Ltd., Trane Technologies plc, York International are a few of the key vendors in the Ductless Hvac System market.

APAC will register the highest growth rate of 48% among the other regions. Therefore, the Ductless Hvac System market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, Japan, India, South Korea, Indonesia, Australia, Germany, UK, France, Italy, The Netherlands, Spain, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Escalating demand for energy efficiency is the driving factor this market.

The Ductless Hvac System market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
