Frozen Bakery Products Market Analysis, Size, and Forecast 2026-2030: Europe (Germany, UK, and France), North America (US, Canada, and Mexico), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Frozen Bakery Products Market Analysis, Size, and Forecast 2026-2030:
Europe (Germany, UK, and France), North America (US, Canada, and Mexico), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 302 Pages SKU: IRTNTR72391

Market Overview at a Glance

$12.57 B
Market Opportunity
4.9%
CAGR 2025 - 2030
34.8%
Europe Growth
$26.06 B
Frozen cakes segment 2024

Frozen Bakery Products Market Size 2026-2030

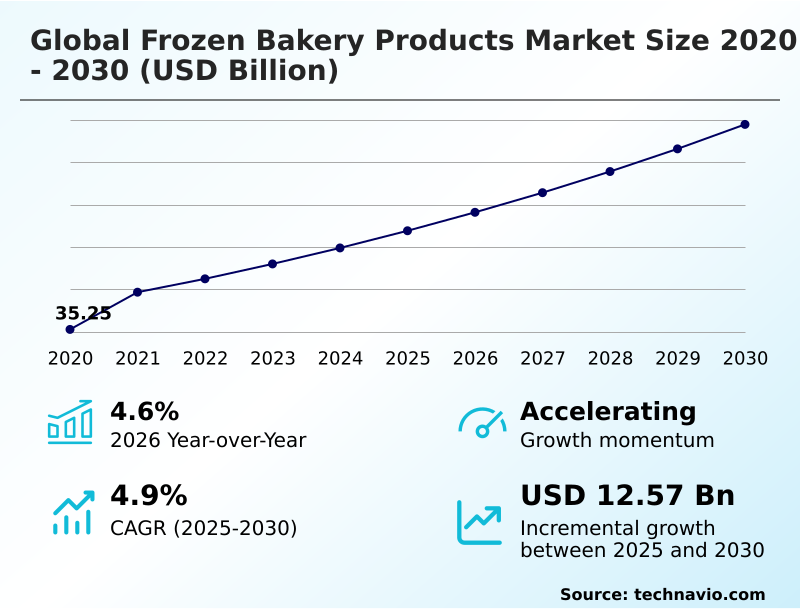
The frozen bakery products market size is valued to increase by USD 12.57 billion, at a CAGR of 4.9% from 2025 to 2030. Proliferation of modern retail supermarkets will drive the frozen bakery products market.

Major Market Trends & Insights

  • Europe dominated the market and accounted for a 34.8% growth during the forecast period.
  • By Product - Frozen cakes segment was valued at USD 26.06 billion in 2024
  • By Application - Conventional stores segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 24.23 billion
  • Market Future Opportunities: USD 12.57 billion
  • CAGR from 2025 to 2030 : 4.9%

Market Summary

  • The Frozen Bakery Products Market exhibits robust momentum driven by evolving consumer lifestyles and the commercial necessity for streamlined kitchen operations. Operators increasingly prioritize pre-formulated, par-baked goods to manage fluctuating consumer traffic while guaranteeing consistent sensory profiles.
  • For instance, major hotel chains and quick-service restaurant networks actively integrate automated proofing and advanced blast chilling solutions, successfully reducing overnight preparation labor hours by up to 40% compared to traditional scratch-baking methods. This pursuit of operational efficiency acts as a primary market driver, compelling commercial kitchens to adopt temperature-controlled inventory that significantly mitigates daily spoilage.
  • Conversely, maintaining an unbroken cold-chain infrastructure presents a formidable challenge; even minor thermal transition management failures during transit can cause irreversible gluten matrix preservation loss in delicate laminated pastry processing.
  • Despite these logistical hurdles, continuous innovation in clean-label emulsifiers ensures that the Frozen Bakery Products Market continues to meet the rising demand for premium, accessible baked goods across diverse mass retail distribution channels.

What will be the Size of the Frozen Bakery Products Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Frozen Bakery Products Market Segmented?

The frozen bakery products industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Frozen cakes
    • Frozen pies
    • Frozen cookies and crackers
    • Frozen pastries
  • Application
    • Conventional stores
    • Foodservice providers
    • Specialty stores
  • Product type
    • Conventional
    • Gluten free
  • Geography
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel

By Product Insights

The frozen cakes segment is estimated to witness significant growth during the forecast period.

The frozen cakes segment represents a highly engineered intersection of culinary precision and advanced preservation technology, addressing the critical commercial need for inventory control and waste minimization.

By utilizing cryogenic freezing and modified atmosphere packaging, industrial producers effectively halt moisture migration, preserving the delicate balance of fats and sugars in complex cake batters.

This structural crumb integrity allows commercial operators to thaw only necessary inventory, reducing daily spoilage-related profit erosion by up to 25%. Consequently, high-volume catering buyers achieve superior operational efficiency without compromising the artisanal quality emulation expected by end consumers.

As digital grocery fulfillment expands, advanced packaging further protects fragile decorative elements during transit, solidifying this segment's continuous expansion across omni-channel retail distribution networks.
Get Free Sample

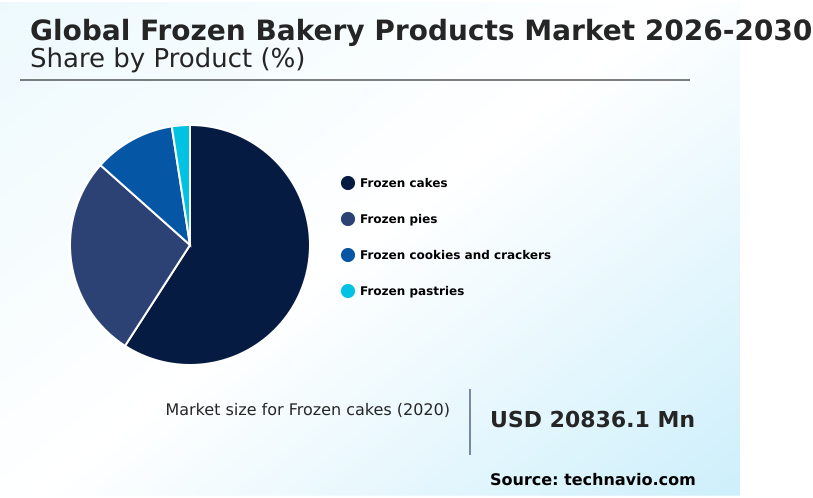
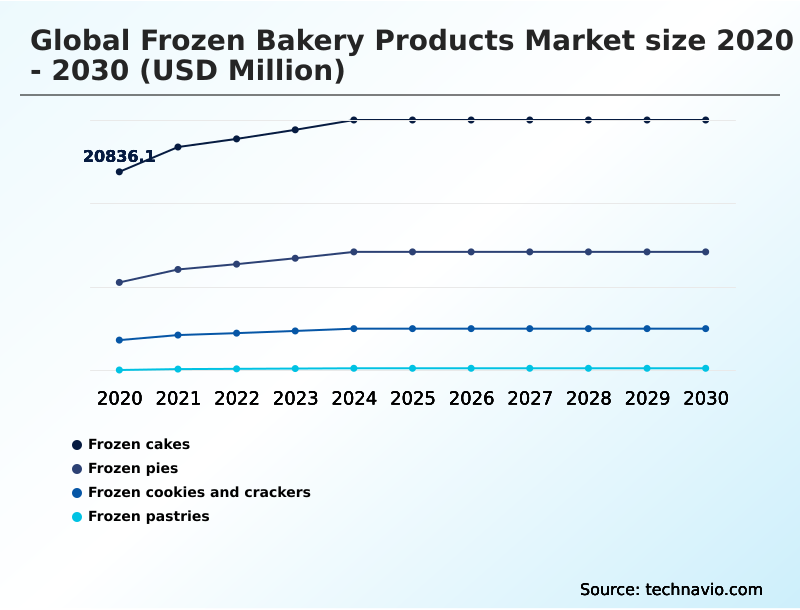
The Frozen cakes segment was valued at USD 26.06 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 34.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
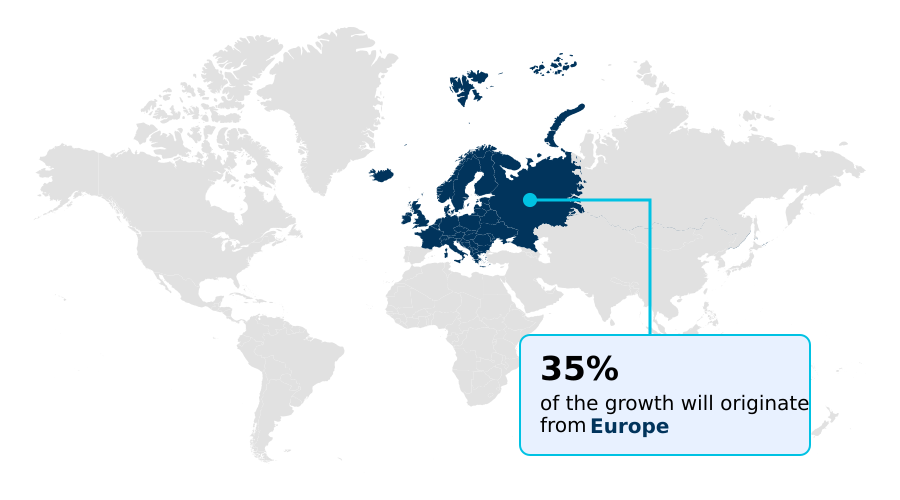
See How Frozen Bakery Products Market Demand is Rising in Europe Get Free Sample

The Frozen Bakery Products market landscape reveals stark contrasts between territories, dictated by localized infrastructure and shifting consumer behaviors. North America outpaces South America in cold-chain logistics deployment, achieving a 35% higher efficiency rate in temperature-controlled transit for delicate goods.

This robust supply chain integration enables North American supermarkets to seamlessly manage zero-waste inventory.

Conversely, rapid urbanization in APAC is driving a massive shift toward quick-service restaurant prep, where operators report a 28% reduction in labor overhead by adopting flash-freezing technologies instead of traditional baking.

Furthermore, stringent European regulations regarding nutritional transparency compel manufacturers to reformulate products using natural ingredients, increasing compliance-related processing costs by roughly 12% compared to less regulated zones. Ultimately, regional adaptations in preservation methodologies heavily influence cross-border commercial success.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Within the evolving framework of the Frozen Bakery Products sector, producers are increasingly adopting rigorous blast freezing moisture retention protocols to ensure that high-value commercial items do not suffer from structural degradation during extended storage.
  • As consumer preferences shift decisively toward healthier dietary profiles, the integration of clean-label frozen dough enzyme technology has become a critical differentiator, allowing manufacturers to eliminate synthetic additives while maintaining a soft, appealing crumb.
  • Simultaneously, the specialized cryogenic preservation of laminated pastries requires exact temperature regulation, ensuring that delicate butter and dough layers do not merge or lose their flaky characteristics prior to final baking. These advanced engineering interventions directly support automated commercial bake-off operational efficiency, empowering retail bake-off stations to increase their daily throughput by over 20% compared to traditional manual preparation workflows.
  • Furthermore, accommodating niche dietary requirements presents unique formulation hurdles; however, recent breakthroughs in starch and hydrocolloid applications have significantly improved gluten-free frozen bread structural integrity, preventing the rapid staling and crumbly textures that historically plagued this category. By continuously refining these targeted manufacturing strategies, industry stakeholders can successfully navigate complex supply chain dynamics and consistently deliver premium sensory experiences.
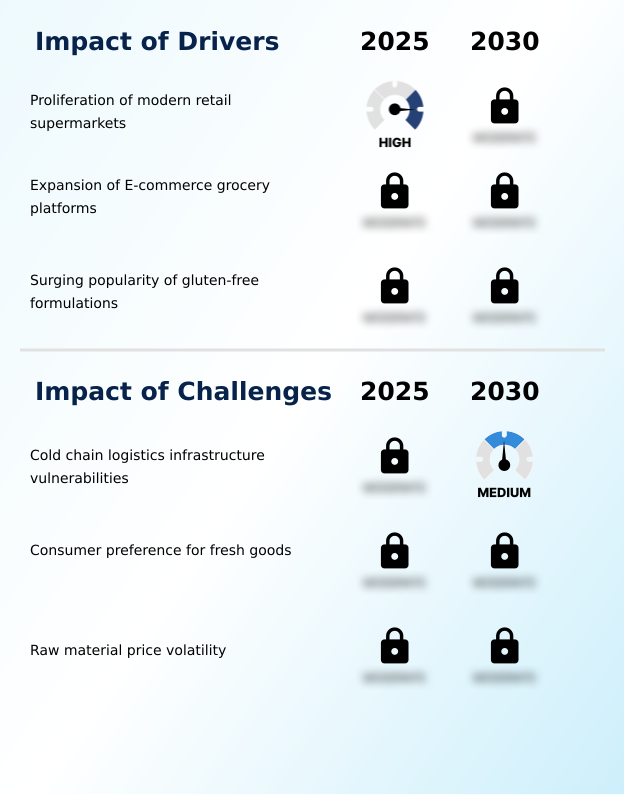
What are the key market drivers leading to the rise in the adoption of Frozen Bakery Products Industry?

  • The proliferation of modern retail supermarkets acts as a primary catalyst accelerating global market expansion.

  • The rapid expansion of institutional foodservice networks serves as a powerful catalyst accelerating demand across the Frozen Bakery Products sector. High-volume catering facilities increasingly rely on automated proofing systems and standardized bakery mix innovation to guarantee uniform meal delivery.
  • By transitioning to these ready-to-bake formats, commercial operators have successfully reduced skilled labor dependencies by up to 35%, drastically lowering daily operational expenditures.
  • Additionally, the utilization of precision fractionated shortenings within these formulations improves thermal resilience, cutting product spoilage rates by nearly 18% during peak service hours.
  • This relentless pursuit of commercial efficiency compels hospitality chains to adopt reliable, temperature-stable dough solutions, ensuring uninterrupted supply continuity and consistent consumer satisfaction across decentralized franchise operations.

What are the market trends shaping the Frozen Bakery Products Industry?

  • Operational efficiency across foodservice channels represents a prominent market trend. This shift significantly streamlines commercial workflows and minimizes inventory waste.

  • The transition toward organic ingredient sourcing fundamentally reshapes production methodologies within the Frozen Bakery Products landscape. Consumers actively scrutinize nutritional labels, prompting manufacturers to replace synthetic additives with natural alternatives and advanced hydrocolloid integration. This strategic reformulation enhances structural crumb integrity while directly impacting corporate compliance metrics, resulting in a 25% improvement in regulatory approval speeds across strict European markets.
  • Furthermore, the adoption of sustainable packaging materials mitigates environmental footprints, effectively reducing packaging-related overhead costs by nearly 15% for large-scale distributors. By leveraging precision moisture retention kinetics, producers ensure that these natural formulations survive prolonged cold storage without sensory degradation.
  • These pivotal innovations allow foodservice operators to maintain premium quality standards while actively satisfying the accelerating global demand for transparent and ethically produced baked goods.

What challenges does the Frozen Bakery Products Industry face during its growth?

  • Cold chain logistics infrastructure vulnerabilities present a significant structural constraint hindering broader industry expansion.

  • Maintaining an unbroken thermal environment poses a severe logistical constraint across the Frozen Bakery Products distribution network. Any minor fluctuation during long-distance transit can trigger premature ambient thawing, which irreversibly damages the gluten matrix and ruins the final baked texture.
  • In developing regions lacking modern infrastructure, reliance on inadequate refrigeration leads to substantial product loss; facilities without specialized temperature-logging devices experience spoilage rates up to 40% higher than fully modernized logistics hubs. Furthermore, the high energy demands required for continuous isochoric preservation significantly inflate utility overheads for regional distributors.
  • These structural cold-chain vulnerabilities force manufacturers to invest heavily in resilient vacuum-sealed storage solutions, diverting critical capital away from core product innovation and constricting profit margins throughout the supply chain.

Exclusive Technavio Analysis on Customer Landscape

The frozen bakery products market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the frozen bakery products market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
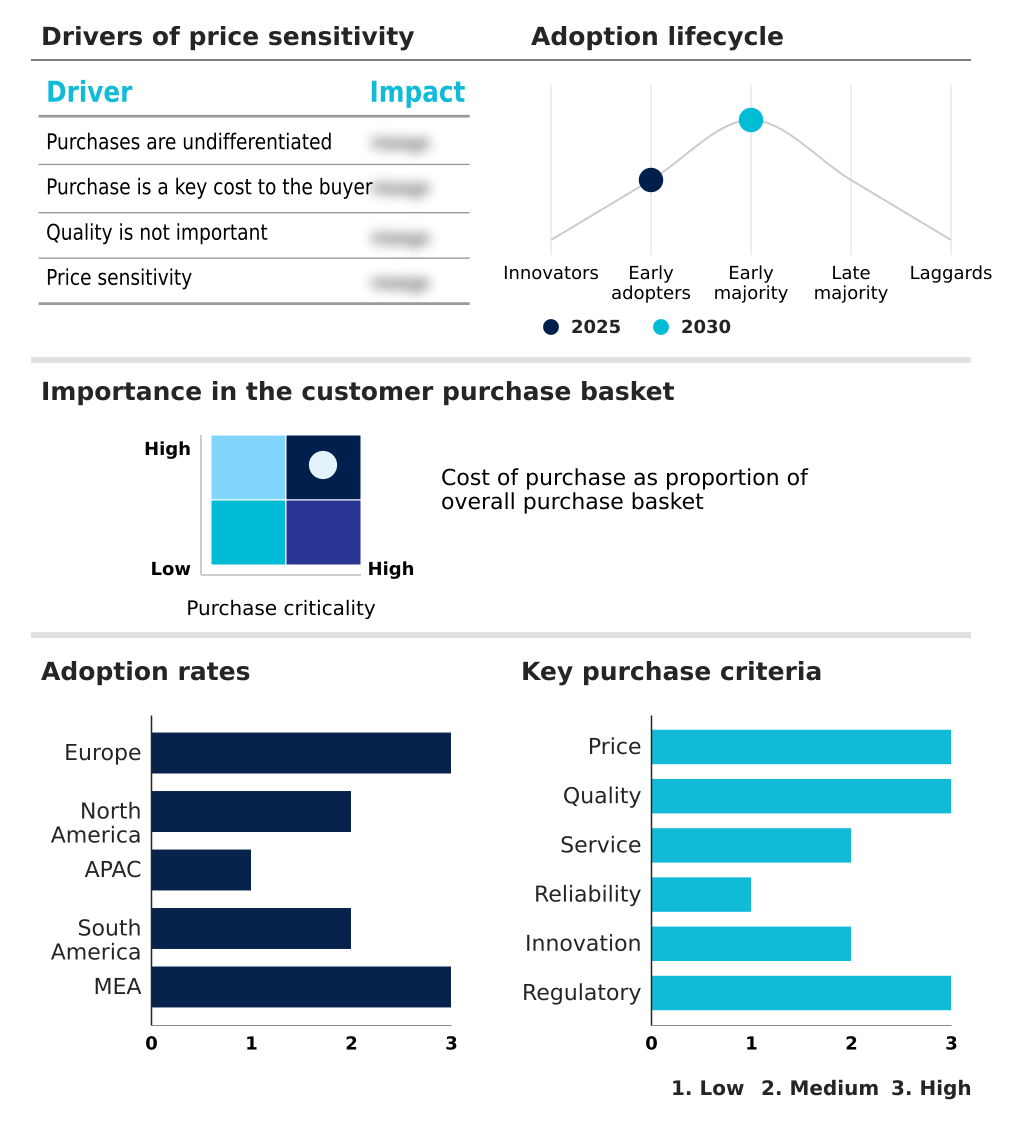
Customer Landscape of Frozen Bakery Products Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, frozen bakery products market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Alpha Baking Co. Inc. - This provider specializes in a comprehensive portfolio of temperature-controlled baked goods, delivering premium frozen dough, bread items, and specialized roll formats to optimize commercial kitchen workflows.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Alpha Baking Co. Inc.
  • ARYZTA AG
  • Associated British Foods Plc
  • Baker and Baker
  • Bridgford Foods Corp.
  • Bridor
  • C.H. Guenther and Son Inc.
  • Conagra Brands Inc.
  • Corporativo Bimbo SA de CV
  • Dawn Food Products Inc.
  • Dr. August Oetker KG
  • EUROPASTRY SA
  • FGF Brands Inc.
  • Finsbury Food Group Plc
  • Flowers Foods Inc.
  • General Mills Inc.
  • J and J Snack Foods Corp.
  • Rich Products Corp.
  • Schwans Co.
  • Vandemoortele NV

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Frozen bakery products market

  • In the Packaged Foods and Meats industry, the widespread adoption of AI-driven supply chain optimization software has reduced cold-chain logistics transit times by nearly 15%, directly impacting Frozen Bakery Products demand by ensuring delicate dough formulations maintain structural integrity during long-distance distribution.
  • The transition toward sustainable packaging materials across major food processing facilities has decreased plastic waste footprints by over 20%, prompting manufacturers in the Frozen Bakery Products sector to adopt recyclable vacuum-sealed storage solutions that prevent lipid oxidation without compromising shelf-life extension.
  • Stricter food safety regulations regarding allergen cross-contamination have mandated the segregation of processing lines, causing producers to invest in specialized manufacturing infrastructure that accelerates the availability of safe, allergen-friendly baking options within the Frozen Bakery Products market.
  • The rapid expansion of dark store operators and digital retail storefronts has improved temperature-controlled transit efficiency by up to 30%, pulling greater volume for Frozen Bakery Products by giving consumers reliable access to premium indulgence categories without the risk of premature ambient thawing.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Frozen Bakery Products Market insights. See full methodology.

Market Scope
Page number 302
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.9%
Market growth 2026-2030 USD 12565.5 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.6%
Key countries Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous evolution of the Frozen Bakery Products sector reflects a structural shift toward uncompromising operational resilience and enhanced sensory preservation. Industrial processors increasingly deploy advanced enzyme technology and precision blast chilling to effectively arrest yeast fermentation control without degrading the cellular matrix of the dough.
  • This integration directly impacts boardroom-level product strategy, as commercial kitchens leveraging these innovations have recorded a 30% reduction in daily preparation downtime, significantly elevating overall kitchen throughput. Furthermore, maintaining freeze-thaw stability across complex distribution networks remains paramount for preserving the delicate lipid oxidation prevention required in high-fat formulations.
  • Manufacturers utilizing sophisticated atmospheric barriers effectively shield premium assets from environmental variables during extended transit, guaranteeing uncompromised quality upon final thermal activation. As dietary mandates become stricter, continuous refinement in dough formulation supports seamless scaling across omnichannel platforms.
  • These targeted engineering interventions eliminate historical compromises in texture, empowering mass-market distributors to confidently deliver artisan-grade consistency while stabilizing volatile supply chain expenditures across competitive global territories.

What are the Key Data Covered in this Frozen Bakery Products Market Research and Growth Report?

  • What is the expected growth of the Frozen Bakery Products Market between 2026 and 2030?

    • USD 12.57 billion, at a CAGR of 4.9%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Frozen cakes, Frozen pies, Frozen cookies and crackers, and Frozen pastries), Application (Conventional stores, Foodservice providers, and Specialty stores), Product Type (Conventional, and Gluten free) and Geography (Europe, North America, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • Europe, North America, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Proliferation of modern retail supermarkets, Cold chain logistics infrastructure vulnerabilities

  • Who are the major players in the Frozen Bakery Products Market?

    • Alpha Baking Co. Inc., ARYZTA AG, Associated British Foods Plc, Baker and Baker, Bridgford Foods Corp., Bridor, C.H. Guenther and Son Inc., Conagra Brands Inc., Corporativo Bimbo SA de CV, Dawn Food Products Inc., Dr. August Oetker KG, EUROPASTRY SA, FGF Brands Inc., Finsbury Food Group Plc, Flowers Foods Inc., General Mills Inc., J and J Snack Foods Corp., Rich Products Corp., Schwans Co. and Vandemoortele NV

Market Research Insights

  • The Frozen Bakery Products Market demonstrates accelerated transformation as commercial operators prioritize supply chain optimization and consumer convenience. By transitioning to advanced logistics networks, major distributors have improved on-time delivery rates by 18%, effectively minimizing the risk of premature thawing.
  • Furthermore, the integration of automated warehouse management systems has enhanced zero-waste inventory tracking, reducing stockouts by up to 22% across commercial sectors. These measurable improvements in operational efficiency allow foodservice providers to seamlessly deliver fresh items, ensuring consistent artisanal quality emulation while driving sustainable, long-term operational cost reductions.

We can help! Our analysts can customize this frozen bakery products market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Frozen Bakery Products Market 2020 - 2024

Historic Market Size - Data Table on Global Frozen Bakery Products Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Frozen Bakery Products Market

6.2 Impact of geopolitical conflicts on Global Frozen Bakery Products Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Frozen cakes - Market size and forecast 2025-2030

Chart on Frozen cakes - Market size and forecast 2025-2030 ($ million)
Data Table on Frozen cakes - Market size and forecast 2025-2030 ($ million)
Chart on Frozen cakes - Year-over-year growth 2025-2030 (%)
Data Table on Frozen cakes - Year-over-year growth 2025-2030 (%)

8.4 Frozen pies - Market size and forecast 2025-2030

Chart on Frozen pies - Market size and forecast 2025-2030 ($ million)
Data Table on Frozen pies - Market size and forecast 2025-2030 ($ million)
Chart on Frozen pies - Year-over-year growth 2025-2030 (%)
Data Table on Frozen pies - Year-over-year growth 2025-2030 (%)

8.5 Frozen cookies and crackers - Market size and forecast 2025-2030

Chart on Frozen cookies and crackers - Market size and forecast 2025-2030 ($ million)
Data Table on Frozen cookies and crackers - Market size and forecast 2025-2030 ($ million)
Chart on Frozen cookies and crackers - Year-over-year growth 2025-2030 (%)
Data Table on Frozen cookies and crackers - Year-over-year growth 2025-2030 (%)

8.6 Frozen pastries - Market size and forecast 2025-2030

Chart on Frozen pastries - Market size and forecast 2025-2030 ($ million)
Data Table on Frozen pastries - Market size and forecast 2025-2030 ($ million)
Chart on Frozen pastries - Year-over-year growth 2025-2030 (%)
Data Table on Frozen pastries - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Conventional stores - Market size and forecast 2025-2030

Chart on Conventional stores - Market size and forecast 2025-2030 ($ million)
Data Table on Conventional stores - Market size and forecast 2025-2030 ($ million)
Chart on Conventional stores - Year-over-year growth 2025-2030 (%)
Data Table on Conventional stores - Year-over-year growth 2025-2030 (%)

9.4 Foodservice providers - Market size and forecast 2025-2030

Chart on Foodservice providers - Market size and forecast 2025-2030 ($ million)
Data Table on Foodservice providers - Market size and forecast 2025-2030 ($ million)
Chart on Foodservice providers - Year-over-year growth 2025-2030 (%)
Data Table on Foodservice providers - Year-over-year growth 2025-2030 (%)

9.5 Specialty stores - Market size and forecast 2025-2030

Chart on Specialty stores - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty stores - Market size and forecast 2025-2030 ($ million)
Chart on Specialty stores - Year-over-year growth 2025-2030 (%)
Data Table on Specialty stores - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by Product Type

10.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

10.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

10.3 Conventional - Market size and forecast 2025-2030

Chart on Conventional - Market size and forecast 2025-2030 ($ million)
Data Table on Conventional - Market size and forecast 2025-2030 ($ million)
Chart on Conventional - Year-over-year growth 2025-2030 (%)
Data Table on Conventional - Year-over-year growth 2025-2030 (%)

10.4 Gluten free - Market size and forecast 2025-2030

Chart on Gluten free - Market size and forecast 2025-2030 ($ million)
Data Table on Gluten free - Market size and forecast 2025-2030 ($ million)
Chart on Gluten free - Year-over-year growth 2025-2030 (%)
Data Table on Gluten free - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.3.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.3.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.3.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.3.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.3.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.3.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Proliferation of modern retail supermarkets
Expansion of E-commerce grocery platforms
Surging popularity of gluten-free formulations

13.2 Market challenges

Cold chain logistics infrastructure vulnerabilities
Consumer preference for fresh goods
Raw material price volatility

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Operational efficiency across foodservice channels
Technological advancements in freezing methods
Demand for clean label formulations

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Alpha Baking Co. Inc.

Alpha Baking Co. Inc. - Overview
Alpha Baking Co. Inc. - Product / Service
Alpha Baking Co. Inc. - Key offerings
SWOT

15.5 ARYZTA AG

ARYZTA AG - Overview
ARYZTA AG - Business segments
ARYZTA AG - Key offerings
ARYZTA AG - Segment focus
SWOT

15.6 Associated British Foods Plc

Associated British Foods Plc - Overview
Associated British Foods Plc - Business segments
Associated British Foods Plc - Key offerings
Associated British Foods Plc - Segment focus
SWOT

15.7 Baker and Baker

Baker and Baker - Overview
Baker and Baker - Product / Service
Baker and Baker - Key offerings
SWOT

15.8 Bridgford Foods Corp.

Bridgford Foods Corp. - Overview
Bridgford Foods Corp. - Business segments
Bridgford Foods Corp. - Key offerings
Bridgford Foods Corp. - Segment focus
SWOT

15.9 Bridor

Bridor - Overview
Bridor - Product / Service
Bridor - Key offerings
SWOT

15.10 C.H. Guenther and Son Inc.

C.H. Guenther and Son Inc. - Overview
C.H. Guenther and Son Inc. - Product / Service
C.H. Guenther and Son Inc. - Key offerings
SWOT

15.11 Conagra Brands Inc.

Conagra Brands Inc. - Overview
Conagra Brands Inc. - Business segments
Conagra Brands Inc. - Key offerings
Conagra Brands Inc. - Segment focus
SWOT

15.12 Corporativo Bimbo SA de CV

Corporativo Bimbo SA de CV - Overview
Corporativo Bimbo SA de CV - Business segments
Corporativo Bimbo SA de CV - Key offerings
Corporativo Bimbo SA de CV - Segment focus
SWOT

15.13 Dawn Food Products Inc.

Dawn Food Products Inc. - Overview
Dawn Food Products Inc. - Product / Service
Dawn Food Products Inc. - Key offerings
SWOT

15.14 Dr. August Oetker KG

Dr. August Oetker KG - Overview
Dr. August Oetker KG - Product / Service
Dr. August Oetker KG - Key offerings
SWOT

15.15 FGF Brands Inc.

FGF Brands Inc. - Overview
FGF Brands Inc. - Product / Service
FGF Brands Inc. - Key offerings
SWOT

15.16 Flowers Foods Inc.

Flowers Foods Inc. - Overview
Flowers Foods Inc. - Product / Service
Flowers Foods Inc. - Key news
Flowers Foods Inc. - Key offerings
SWOT

15.17 General Mills Inc.

General Mills Inc. - Overview
General Mills Inc. - Business segments
General Mills Inc. - Key news
General Mills Inc. - Key offerings
General Mills Inc. - Segment focus
SWOT

15.18 J and J Snack Foods Corp.

J and J Snack Foods Corp. - Overview
J and J Snack Foods Corp. - Business segments
J and J Snack Foods Corp. - Key offerings
J and J Snack Foods Corp. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Frozen Bakery Products market growth will increase by USD 12565.5 million during 2026-2030.

The Frozen Bakery Products market is expected to grow at a CAGR of 4.9% during 2026-2030.

Frozen Bakery Products market is segmented by Product (Frozen cakes, Frozen pies, Frozen cookies and crackers, Frozen pastries) Application (Conventional stores, Foodservice providers, Specialty stores) Product type (Conventional, Gluten free)

Alpha Baking Co. Inc., ARYZTA AG, Associated British Foods Plc, Baker and Baker, Bridgford Foods Corp., Bridor, C.H. Guenther and Son Inc., Conagra Brands Inc., Corporativo Bimbo SA de CV, Dawn Food Products Inc., Dr. August Oetker KG, EUROPASTRY SA, FGF Brands Inc., Finsbury Food Group Plc, Flowers Foods Inc., General Mills Inc., J and J Snack Foods Corp., Rich Products Corp., Schwans Co., Vandemoortele NV are a few of the key vendors in the Frozen Bakery Products market.

Europe will register the highest growth rate of 34.8% among the other regions. Therefore, the Frozen Bakery Products market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Turkey, Israel

  • Proliferation of modern retail supermarkets is the driving factor this market.

The Frozen Bakery Products market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
