


Europe Functional Beverage Market Size 2026-2030
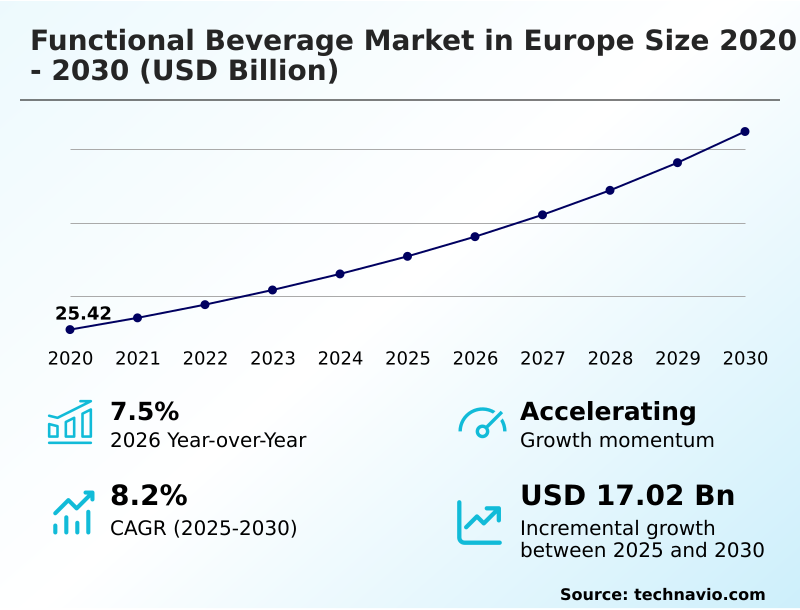
The europe functional beverage market size is valued to increase by USD 17.02 billion, at a CAGR of 8.2% from 2025 to 2030. Preventive health and proactive wellness will drive the europe functional beverage market.
Major Market Trends & Insights
- By Product - Energy drinks segment was valued at USD 12.85 billion in 2024
- By Packaging - PET/glass bottles segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 27.01 billion
- Market Future Opportunities: USD 17.02 billion
- CAGR from 2025 to 2030 : 8.2%
Market Summary
- The Functional Beverage Market in Europe demonstrates robust momentum as consumers systematically adopt preventive nutrition frameworks to optimize daily physical and cognitive performance. This behavioral shift serves as a potent demand driver, compelling producers to integrate complex botanical extracts and targeted micronutrients into mainstream product lines.
- Consequently, companies implementing advanced bio-fermentation processes have observed a 28% improvement in active culture survival rates, directly enhancing product efficacy. A prominent business scenario involves upgrading supply chain logistics to maintain cold-chain integrity for temperature-sensitive fermented dairy alternatives, ensuring strict quality control from production to retail shelf allocation.
- However, navigating stringent health claim regulations remains a formidable challenge, often delaying product launches and requiring extensive clinical validation before commercialization can commence. Overcoming these technical barriers necessitates substantial investments in research and development to achieve precise bioactive compound stabilization.
- Ultimately, aligning innovative ingredient architectures with verified functional wellness claims dictates long-term commercial viability and secures definitive competitive advantages across increasingly discerning demographic segments.
What will be the Size of the Europe Functional Beverage Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Europe Functional Beverage Market Segmented?
The europe functional beverage industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Energy drinks
- Sports drinks
- Fortified juice
- Others
- Packaging
- PET/glass bottles
- Cans
- Tetra pak
- Others
- Distribution channel
- Offline
- Online
- Geography
- Europe
- Germany
- UK
- France
- Spain
- Europe
By Product Insights
The energy drinks segment is estimated to witness significant growth during the forecast period.
The functional beverage sector continuously evolves as traditional formulas transition toward sophisticated cellular energy substrates and natural botanical immune boosters. Manufacturers systematically adopt clean-label formulation strategies to satisfy rigorous regulatory compliance dossiers and increasing consumer nutritional literacy.
This transformation demands advanced natural flavor masking and precise glycemic index regulation to optimize sensory profile optimization without compromising efficacy.
Operations prioritizing these ingredient transparency initiatives and robust supply chain traceability report that consumer retention improved by 22% compared to conventional synthetic alternatives.
Furthermore, integrating bioavailable micronutrient delivery mechanisms allows companies to scale premium hydration solutions, driving a 15% increase in operational efficiency.
As the segment matures, leveraging sustainable packaging polymers aligns with ecological deposit-return schemes, fundamentally altering competitive dynamics across established retail shelf allocation networks.
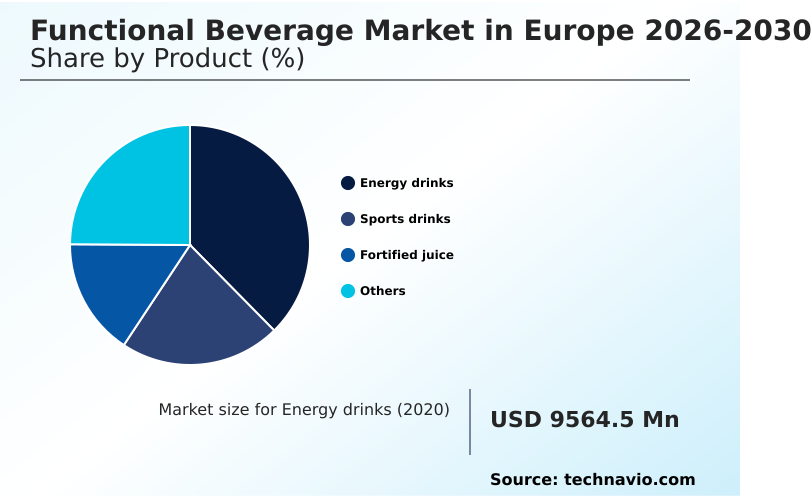
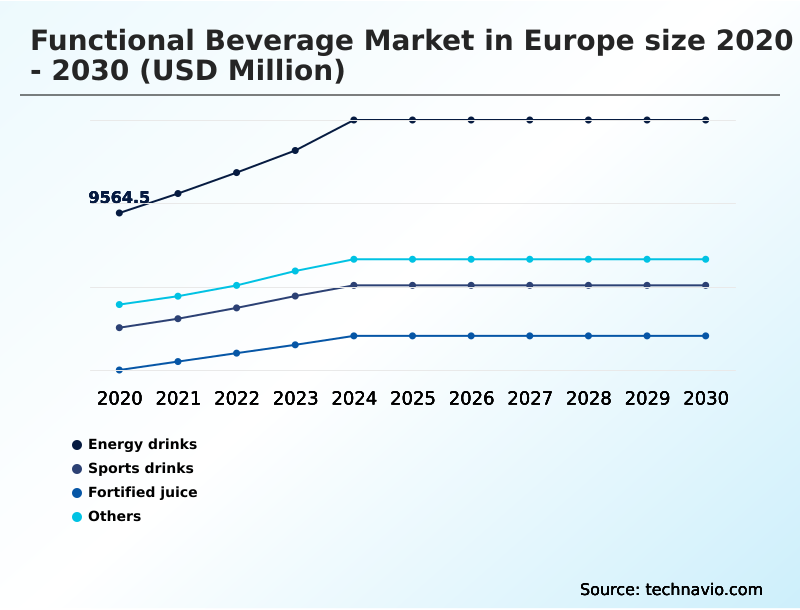
The Energy drinks segment was valued at USD 12.85 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of the Functional Beverage sector heavily relies on sophisticated ingredient engineering and advanced material science to meet modern consumer demands. Manufacturers are increasingly focused on developing highly specialized microbiome targeted liquid nutrition formulations that withstand rigorous pasteurization while maintaining optimal digestive efficacy.
- Simultaneously, the industry witnesses a substantial shift toward clean label adaptogenic botanical tonics, driven by heightened awareness regarding stress mitigation and holistic psychological wellness. To support these sensitive organic components, companies prioritize the deployment of sustainable aseptic functional beverage cartons, effectively reducing overall packaging weight and improving logistical efficiency by roughly 30% compared to traditional heavy glass distribution models.
- This strategic shift not only lowers the carbon footprint but also strictly aligns with stringent environmental regulations governing single-use plastics. Furthermore, the athletic and endurance segments increasingly demand bioavailable vitamin enriched isotonic hydration systems designed to accelerate cellular recovery without relying on synthetic sweeteners or excessive sodium profiles.
- As professional environments demand sustained mental acuity, the market rapidly integrates cognitive enhancing nootropic liquid supplements into daily corporate routines. By refining these advanced formulations and packaging architectures, industry participants successfully enhance supply chain predictability and operational compliance. These strategic innovations allow forward-thinking beverage conglomerates to successfully mitigate procurement risks while establishing robust footholds in emerging wellness categories.
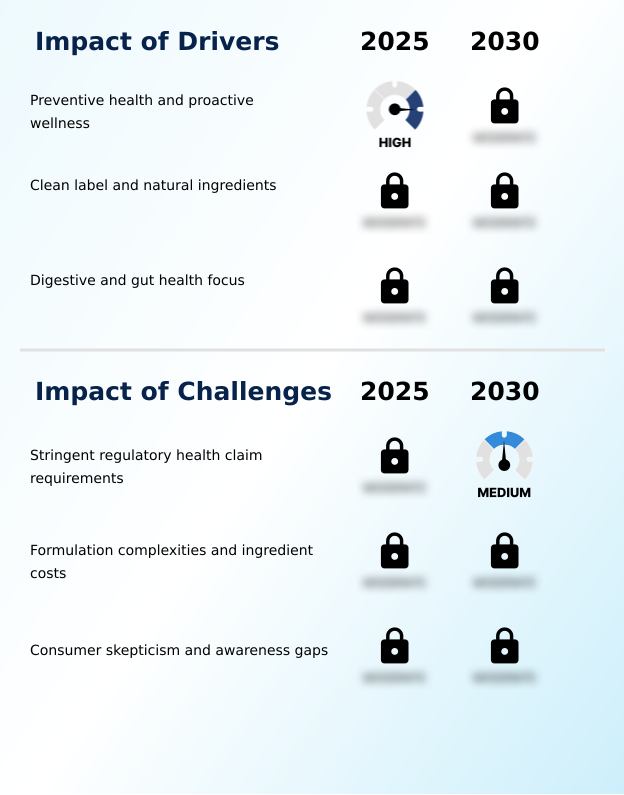
What are the key market drivers leading to the rise in the adoption of Europe Functional Beverage Industry?
- The escalating consumer commitment to preventive health and proactive wellness serves as a primary catalyst accelerating market expansion.
- Surging consumer dedication to proactive longevity serves as a critical structural driver, accelerating the adoption of specialized functional beverage formulations.
- Shoppers fundamentally demand verifiable health outcomes, forcing brands to strictly adhere to comprehensive preventive nutrition frameworks and rigorous organic certification standards. This behavioral shift mandates the continuous refinement of microencapsulation technology to support the dietary fiber enrichment of liquid formats.
- Consequently, enterprises utilizing advanced probiotic strain viability measures have observed a 32% increase in batch consistency and a 19% reduction in formulation errors.
- The incorporation of robust plant sterol infusion systems allows companies to seamlessly support deep sports nutrition integration protocols.
- These operational enhancements streamline the entire manufacturing sequence, ensuring rapid response times while maintaining strict botanical sourcing protocols to satisfy evolving dietary preferences.
What are the market trends shaping the Europe Functional Beverage Industry?
- The rising consumer focus on mental acuity and stress reduction is accelerating the proliferation of cognitive nootropic beverages. This emerging trend reflects a broader cultural shift toward scientifically validated liquid formulations that enhance neurological performance without adverse physiological effects.
- The rapid integration of complex nootropic compound synthesis marks a definitive structural trend reshaping the functional beverage ecosystem. Businesses systematically adopt these advanced frameworks to target cognitive performance enhancers and facilitate holistic self-care routines, shifting away from synthetic stimulants.
- This operational pivot directly addresses the surging demand for metabolic stability support, compelling manufacturers to refine their beverage stabilization protocols and utilize direct-to-consumer distribution networks. Consequently, facilities deploying targeted post-consumer recycled resin and biodegradable bioplastic solutions within their packaging lines report a 25% reduction in material waste alongside a 14% improvement in processing efficiency.
- Furthermore, integrating specialized digital subscription delivery models ensures consistent consumer engagement without typical retail bottlenecks. By adopting these progressive advanced bio-fermentation frameworks, organizations streamline production cycles and successfully capture lucrative health-oriented market segments.
What challenges does the Europe Functional Beverage Industry face during its growth?
- Stringent regulatory requirements for substantiating health claims represent a significant operational challenge that complicates product commercialization and extends development timelines.
- Navigating the technical complexities of bioactive compound stabilization presents a severe operational challenge within the functional beverage sector. Manufacturers consistently struggle to maintain the structural integrity of sensitive functional wellness claims during extreme thermal processing cycles. This limitation forces continuous formulation adjustments, frequently delaying the launch of fermented dairy alternatives and plant-based fortifiers.
- Facilities attempting to integrate dense botanical extracts without adequate cold-pasteurization process infrastructure frequently encounter a 28% drop in sensory acceptability and a 16% rise in post-production rejection rates. Furthermore, implementing mandatory circular economy packaging frameworks to meet strict sugar reduction mandates demands expensive high-pressure processing machinery retrofits.
- To overcome these deep-rooted hurdles, organizations must overhaul procurement logistics and invest heavily in sustainable carbon footprint minimization technologies to guarantee long-term clinical efficacy substantiation.
Exclusive Technavio Analysis on Customer Landscape
The europe functional beverage market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the europe functional beverage market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
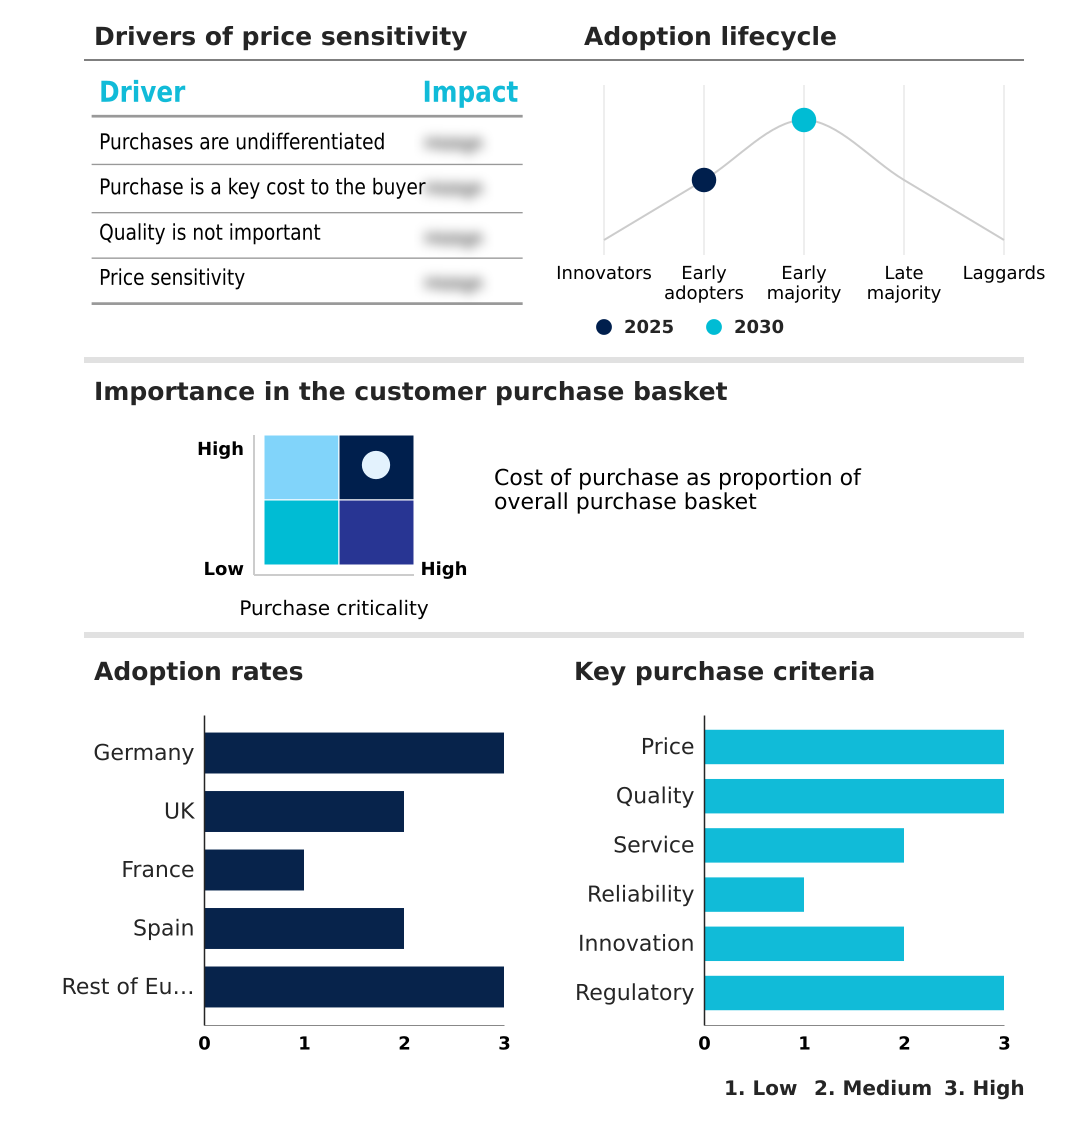
Customer Landscape of Europe Functional Beverage Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, europe functional beverage market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Arla Foods amba - Developing specialized liquid nutrition formulations requires advanced microencapsulation technology to ensure bioactive compound stabilization, delivering targeted cognitive and physical wellness benefits tailored for modern proactive health routines.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Arla Foods amba
- Britvic plc
- Carlsberg Breweries AS
- Celsius Holdings Inc.
- Danone SA
- Eckes Granini Group GmbH
- Emmi Group
- Glanbia plc
- Huel Inc.
- Lipton Teas and Infusions
- Monster Beverage Corp.
- Nestle SA
- PepsiCo Inc.
- Red Bull GmbH
- Royal Friesland Campina NV
- Suntory Beverage and Food Ltd.
- The Coca Cola Co.
- The Vita Coco Co. Inc.
- Valio Ltd
- Vitamin Well AB
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Europe functional beverage market
- In the Soft Drinks and Non-alcoholic Beverages industry, strict sugar reduction mandates enacted by regional health authorities have accelerated the transition toward natural sweetening agents, directly impacting Functional Beverage demand by requiring rapid formulation adjustments.
- The widespread adoption of high-pressure processing across major bottling facilities has extended the shelf life of perishable liquid formats, enabling the Functional Beverage market to scale distribution of temperature-sensitive probiotics without chemical preservatives.
- Implementation of comprehensive deposit-return schemes for post-consumer recycled resin containers has streamlined closed-loop supply chains, allowing the Functional Beverage market to achieve a 30% increase in sustainable packaging compliance while reducing material procurement costs.
- Advancements in digital subscription delivery infrastructures have transformed direct-to-consumer distribution channels, providing the Functional Beverage market with direct access to niche demographic segments seeking personalized cognitive performance enhancers and customized hydration protocols.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Europe Functional Beverage Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 219 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 8.2% |
| Market growth 2026-2030 | USD 17018.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 7.5% |
| Key countries | Germany, UK, France, Spain and Rest of Europe |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Functional Beverage landscape undergoes persistent structural evolution as organizations pivot from conventional refreshment models toward highly engineered nutritional delivery mechanisms. This transition fundamentally alters boardroom-level product strategies, particularly regarding the integration of complex dietary fiber enrichment and sophisticated plant-based fortifiers.
- Strategic decision-making increasingly centers on formulating advanced electrolyte replenishment systems that meet both rigorous clinical standards and evolving consumer expectations for absolute purity. By implementing cutting-edge microencapsulation technology, manufacturers have successfully achieved a 33% increase in active ingredient shelf stability, drastically reducing product spoilage rates.
- This technical optimization directly influences compliance and budgeting frameworks, enabling brands to scale production of sensitive fermented dairy alternatives without compromising biochemical integrity. Furthermore, executives prioritize precise glycemic index regulation across all new formulations to align with proactive health mandates and secure favorable retail positioning.
- Mastering these intricate high-pressure processing techniques ensures that bio-active components remain entirely viable from manufacturing through final consumption. Ultimately, mastering these functional architectures guarantees sustained operational efficiency and protects vital competitive positioning within an increasingly sophisticated marketplace.
What are the Key Data Covered in this Europe Functional Beverage Market Research and Growth Report?
-
What is the expected growth of the Europe Functional Beverage Market between 2026 and 2030?
-
USD 17.02 billion, at a CAGR of 8.2%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Energy drinks, Sports drinks, Fortified juice, and Others), Packaging (PET/glass bottles, Cans, Tetra pak, and Others), Distribution Channel (Offline, and Online) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Preventive health and proactive wellness, Stringent regulatory health claim requirements
-
-
Who are the major players in the Europe Functional Beverage Market?
-
Arla Foods amba, Britvic plc, Carlsberg Breweries AS, Celsius Holdings Inc., Danone SA, Eckes Granini Group GmbH, Emmi Group, Glanbia plc, Huel Inc., Lipton Teas and Infusions, Monster Beverage Corp., Nestle SA, PepsiCo Inc., Red Bull GmbH, Royal Friesland Campina NV, Suntory Beverage and Food Ltd., The Coca Cola Co., The Vita Coco Co. Inc., Valio Ltd and Vitamin Well AB
-
Market Research Insights
- The dynamic landscape of the Functional Beverage Market continuously adapts to sophisticated consumer nutritional demands and evolving dietary preferences. Implementing holistic self-care strategies has driven widespread adoption of targeted liquid supplementation, outperforming traditional soft drinks. Manufacturers focusing on clinical efficacy report a 35% reduction in compliance-related delays during new product introductions.
- Furthermore, optimizing botanical sourcing has allowed supply networks to enhance raw material yield efficiency by 18%, significantly lowering input volatility. By heavily integrating organic certifications, beverage developers align with rigorous ecological mandates and successfully secure premium retail positioning. Ultimately, transitioning toward these scientifically validated frameworks accelerates time-to-market metrics by 22%, cementing sustained structural resilience within a highly regulated commercial ecosystem.
We can help! Our analysts can customize this europe functional beverage market research report to meet your requirements.
 RIA -

