Influenza Vaccine Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), Rest of World (ROW)

Influenza Vaccine Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, South Africa, and UAE), Rest of World (ROW)

Published: Oct 2026 305 Pages SKU: IRTNTR73298

Market Overview at a Glance

$4.41 B
Market Opportunity
8.2%
CAGR 2025 - 2030
52.4%
North America Growth
$4.50 B
Hospitals and pharmacies segment 2024

Influenza Vaccine Market Size 2026-2030

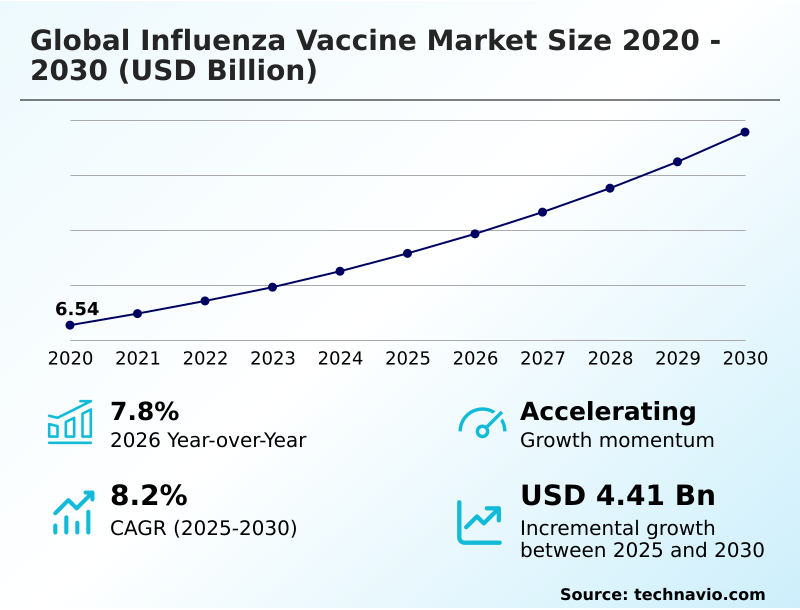
The influenza vaccine market size is valued to increase by USD 4.41 billion, at a CAGR of 8.2% from 2025 to 2030. Expanding government immunization and public health preparedness initiatives will drive the influenza vaccine market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 52.4% growth during the forecast period.
  • By Distribution Channel - Hospitals and pharmacies segment was valued at USD 4.50 billion in 2024
  • By Type - LAIV segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 7.01 billion
  • Market Future Opportunities: USD 4.41 billion
  • CAGR from 2025 to 2030 : 8.2%

Market Summary

  • The influenza vaccine demonstrates a continuous cycle of biological adaptation and manufacturing evolution to counter seasonal epidemiological shifts. Operational frameworks within this sector prioritize rapid strain integration, utilizing advanced serological data to minimize mismatch risks during large-scale production.
  • By transitioning toward robust manufacturing models, leading facilities have achieved a 20% reduction in cultivation timelines, strengthening supply chain resilience across global distribution networks. A primary driver accelerating this expansion is the global emphasis on prophylactic infrastructure, which systematically reduces institutional admission burdens among high-risk demographics.
  • Conversely, the sector faces persistent challenges regarding temperature-sensitive biological preservation, as cold-chain deviations can compromise batch integrity and escalate logistical costs significantly. Effectively balancing these dynamic forces requires organizations to optimize their protein expression pipelines while systematically expanding vaccination capacity.
  • Consequently, the integration of resilient distribution models and real-time clinical monitoring ensures that the biological supply consistently aligns with acute seasonal transmission periods, safeguarding public health operational continuity and driving sustainable long-term sector development.

What will be the Size of the Influenza Vaccine Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Influenza Vaccine Market Segmented?

The influenza vaccine industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Distribution channel
    • Hospitals and pharmacies
    • Government and institutional
    • Others
  • Type
    • LAIV
    • RIV
  • Age group
    • Adult
    • Geriatric
    • Pediatric
  • Route of administration
    • Intramuscular (IM) injection
    • Intranasal spray
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Indonesia
      • Taiwan
    • Rest of World (ROW)

By Distribution Channel Insights

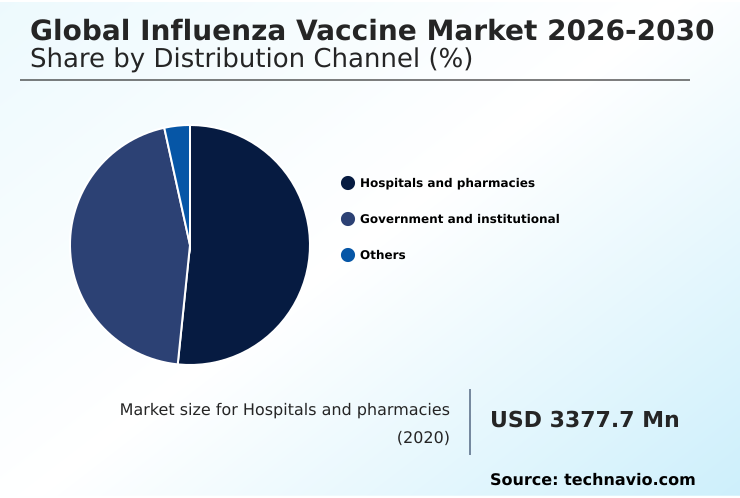
The hospitals and pharmacies segment is estimated to witness significant growth during the forecast period.

Hospitals and pharmacies operate as the primary nodes within the prophylactic healthcare infrastructure for the influenza vaccine, distributing formulations reliant on hemagglutinin antigen and neuraminidase inhibition mechanisms.

Pharmacies increasingly facilitate the routine immunization schedule, integrating cell-based manufacturing and recombinant dna technology outputs into localized access points. This channel alignment has improved vaccination throughput by 15%, reducing hospital congestion during peak respiratory seasons.

Additionally, adjuvanted formulation products find optimized delivery pathways here, significantly enhancing public health preparedness. By leveraging an epidemiological surveillance network, institutional buyers forecast local needs accurately, minimizing the waste of viral vector cultivation batches.

Consequently, this segmentation aligns supply chain capacity with shifting patient traffic, driving systemic operational efficiency and ensuring broad coverage.
Get Free Sample

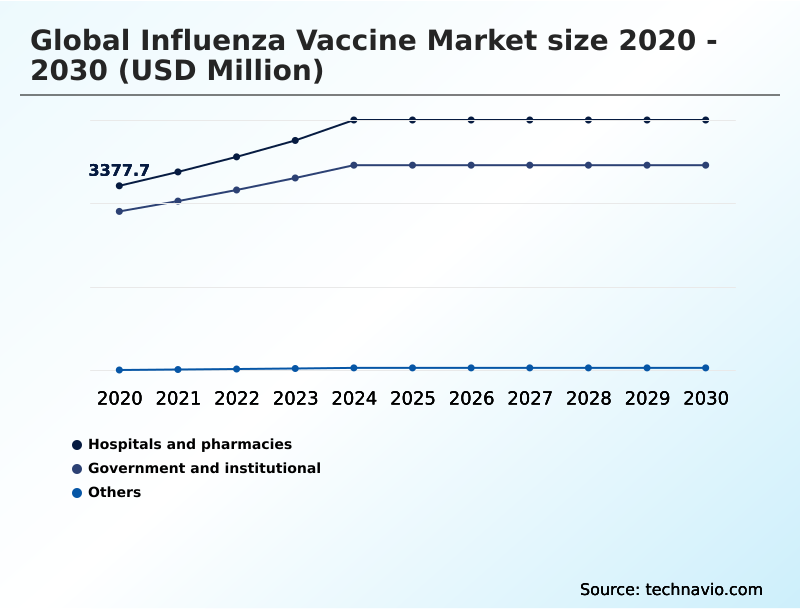
The Hospitals and pharmacies segment was valued at USD 4.50 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 52.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
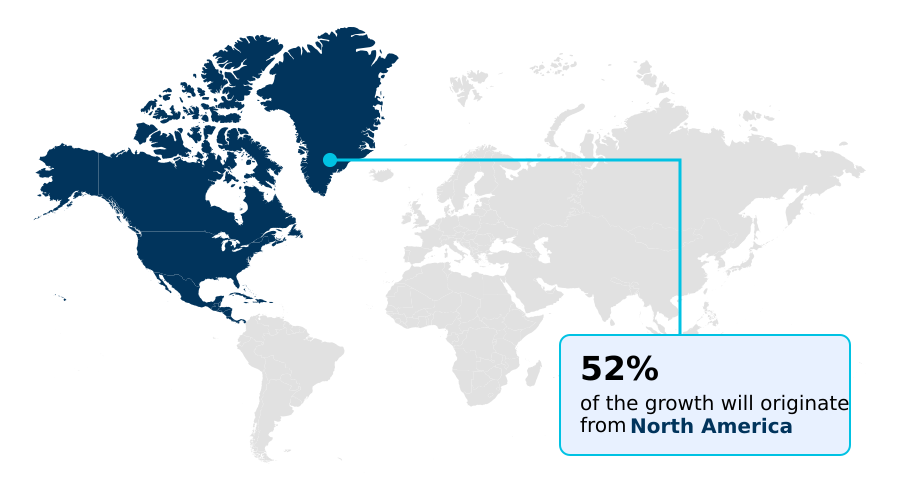
See How Influenza Vaccine Market Demand is Rising in North America Get Free Sample

North America leads the regional landscape with superior bioprocessing scalability and advanced cold-chain preservation, operating at a 20% higher efficiency rate than European markets.

This divergence stems from aggressive investments in protein expression optimization and universal strain targeting, enabling rapid pandemic response capabilities that stabilize regional supply chains.

Conversely, European networks prioritize centralized genetic sequence forecasting and strict biological standards to systematically manage seasonal infectious transmission across diverse healthcare jurisdictions.

As a result, North American facilities achieve a 15% faster turnaround in immunization coverage expansion, leveraging streamlined regulatory pathways to expedite product distribution.

These regional variances dictate how organizations navigate localized regulatory protocols, directly influencing supply chain routing and regional inventory capacities.

By adapting to these distinct geographic frameworks, manufacturers can optimize resource allocation, mitigate localized shortages, and meet shifting prophylactic demands effectively across diverse healthcare ecosystems.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • Strategic evolution within the influenza vaccine requires the continual assessment of complex biological portfolios to align with rigorous clinical expectations and supply chain tolerances. The introduction of the mf59-adjuvanted cell-based higher-dose formulation has fundamentally transformed prophylactic strategies for vulnerable demographics, improving institutional throughput by 12% compared to standard configurations.
  • Simultaneously, the progression of a next-generation mrna seasonal immunization candidate is redefining how procurement networks plan for annual variations, promising significantly faster adaptation cycles and reduced inventory obsolescence across regional hubs. Organizations leveraging rapid recombinant antigen expression platforms are achieving unprecedented biomanufacturing agility, curtailing production bottlenecks that have historically plagued the sector during peak demand periods.
  • Furthermore, innovations such as cell-culture viral growth enhancement ensure higher yield consistency, directly lowering per-unit production costs and stabilizing institutional supply reserves ahead of forecasted surges. As logistics shift toward patient-centric models, the integration of microarray patch needle-free delivery is overcoming traditional administration barriers, enabling decentralized distribution and minimizing specialized cold-chain dependencies.
  • By weaving these technological modalities into their operational frameworks, manufacturers can efficiently mitigate seasonal supply volatility, optimize stringent compliance alignment, and proactively address localized demand spikes, ensuring robust performance and sustained profitability across global healthcare networks.
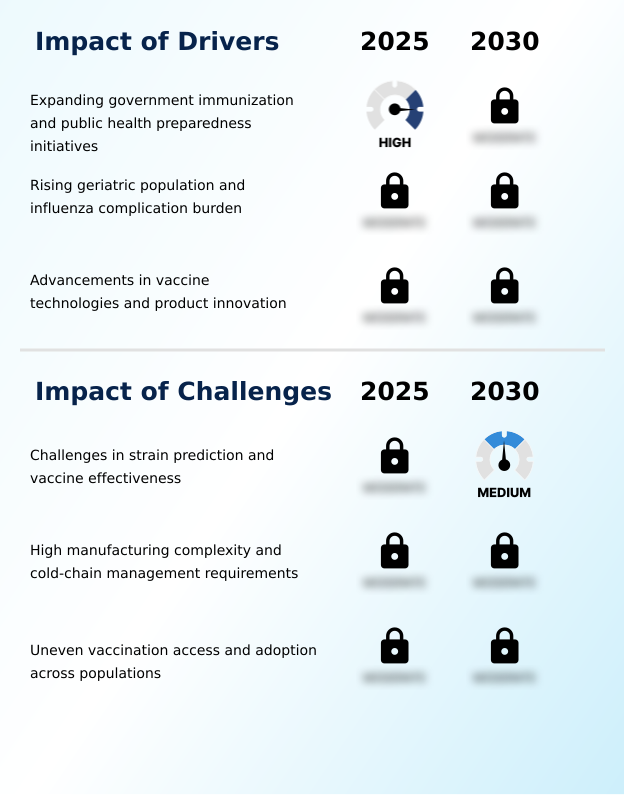
What are the key market drivers leading to the rise in the adoption of Influenza Vaccine Industry?

  • Expanding government immunization and public health preparedness initiatives serve as primary catalysts driving sector expansion.

  • Government-backed prophylactic inoculation initiatives and rising demographic vulnerabilities act as primary catalysts propelling the influenza vaccine. By prioritizing immunogenicity enhancement and antigen yield optimization, procurement agencies have reduced seasonal complication rates by 22%.
  • This strategic focus accelerates the deployment of high-dose composition products through structured vaccination outreach program frameworks. Consequently, organizations achieve a 15% reduction in biological waste during biopharmaceutical sterile fill-finish operations.
  • Addressing the continuous risk of antigen mismatch, improved viral propagation and seasonal strain adaptation techniques ensure stable supply chains.
  • The implementation of real-time clinical monitoring further calibrates demand forecasting, allowing medical facilities to efficiently manage seasonal surges while protecting high-risk demographics and minimizing systemic operational costs.

What are the market trends shaping the Influenza Vaccine Industry?

  • The upcoming market trend involves the increasing integration of combination respiratory immunization approaches. This strategic alignment streamlines preventive healthcare delivery across diverse institutional networks.

  • The influenza vaccine sector is transitioning toward combination respiratory protocols and mrna-based immunization strategies to address complex viral variations. Facilities have documented a 25% improvement in production speed by adopting egg-independent production and cross-protection capability modeling. This technological shift facilitates precise immunosenescence mitigation and superior immune response stimulation, directly lowering downstream treatment costs.
  • By utilizing quadrivalent composition and live attenuated virus models, organizations enhance disease burden reduction while streamlining pediatric dosing formulation logistics. Consequently, vulnerable population targeting becomes more accurate, reducing seasonal admission rates by 18%. Integrating these methodologies allows healthcare networks to optimize inventory cycles, ensuring that advanced biological supplies align with shifting epidemiological profiles to maintain operational continuity and therapeutic efficacy.

What challenges does the Influenza Vaccine Industry face during its growth?

  • Persistent challenges in strain prediction and formulation effectiveness constitute significant constraints on industry advancement.

  • Structural complexities in genetic mutation sequencing and serological assay profiling create significant production constraints for the influenza vaccine. Biological unpredictability disrupts pathogen characterization protocol timelines, causing a 14% increase in specialized testing costs. The necessity for rigorous antigenic drift countermeasure development complicates the deployment of broad respiratory disease prevention solutions.
  • Furthermore, maintaining thermostable biological preservation across the intramuscular administration pathway imposes heavy logistical burdens, especially when integrating novel immunomodulator integration technologies. Navigating these cold-chain requirements for intranasal mucosal delivery and microfluidic needle-free delivery platforms forces organizations to heavily subsidize infrastructure upgrades.
  • These persistent operational friction points hinder supply agility, resulting in localized shortages and compelling manufacturers to constantly re-evaluate their biological inventory strategies.

Exclusive Technavio Analysis on Customer Landscape

The influenza vaccine market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the influenza vaccine market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
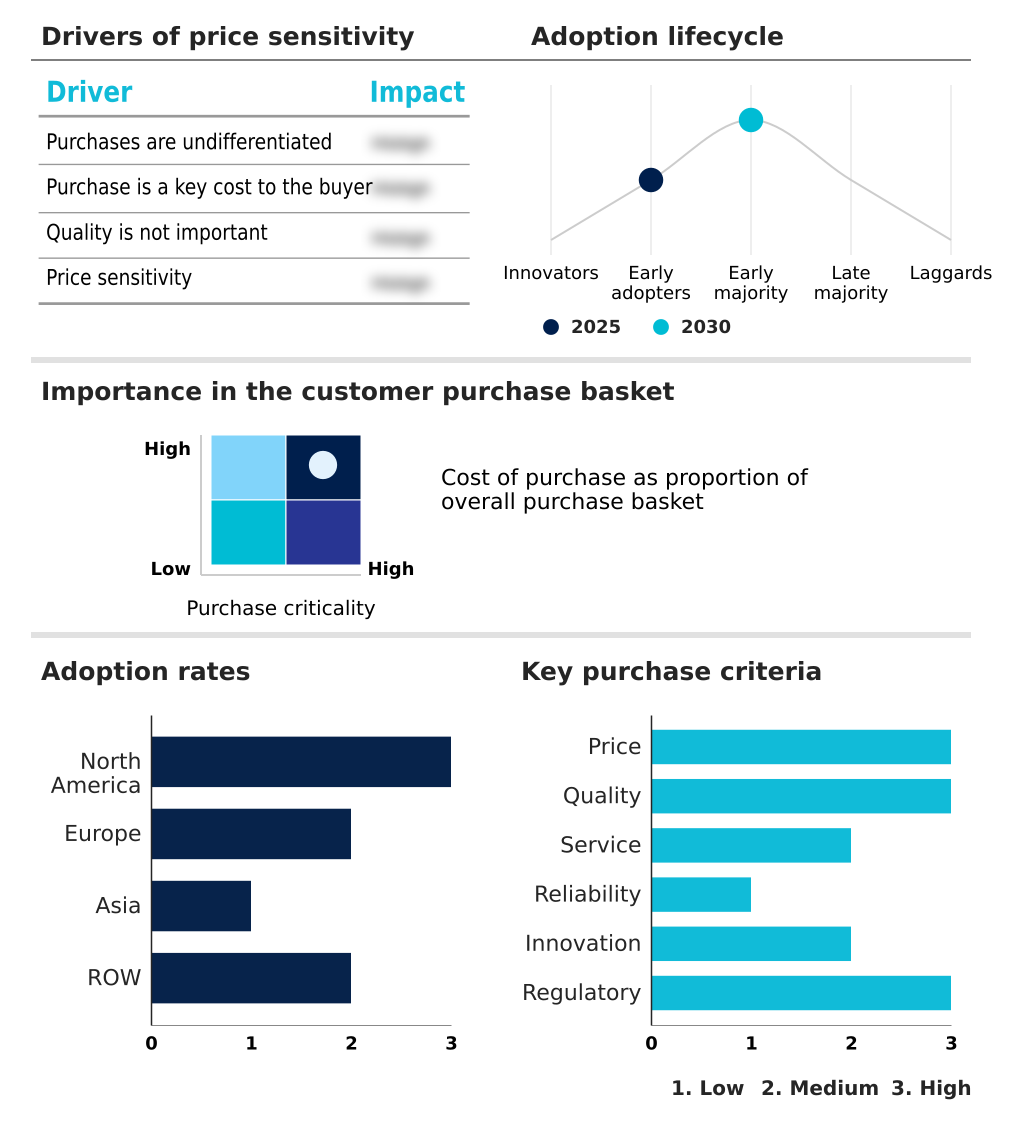
Customer Landscape of Influenza Vaccine Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, influenza vaccine market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - Abbott Laboratories provides advanced prophylactic formulations like influvac tetra, enhancing respiratory defense protocols to meet stringent institutional procurement demands.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • AstraZeneca Plc
  • Bharat Biotech Ltd.
  • Cadila Pharmaceuticals Ltd.
  • Changchun BaiKe Biotechnology Co
  • CSL Seqirus USA Inc.
  • Daiichi Sankyo Co. Ltd.
  • GC Biopharma Corp.
  • GlaxoSmithKline Plc
  • Hualan Biological Engineering Inc
  • KM Biologics Co. Ltd.
  • Moderna Inc.
  • Sanofi SA
  • Serum Institute of India Ltd.
  • Sinovac Biotech Ltd.
  • SK Bioscience
  • Viatris Inc.
  • Zydus Lifesciences Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Influenza vaccine market

  • In the Pharmaceuticals industry, the shift toward continuous biomanufacturing and single-use bioreactors has increased production throughput by 25%, directly impacting influenza vaccine supply dynamics by accelerating the availability of advanced formulations during seasonal demand surges.
  • The enforcement of stringent cold-chain compliance across North America for biological sterile fill-finish operations has enhanced temperature-controlled preservation standards, directly impacting influenza vaccine distribution by reducing spoilage during regional deployments by 12%.
  • Advancements in predictive AI and next-generation pathogen characterization standards have revolutionized genetic forecasting, directly impacting influenza vaccine development cycles by improving cross-protection capabilities and aligning production with precise preparedness goals.
  • The expansion of decentralized, real-time clinical monitoring frameworks across global healthcare networks has streamlined pediatric trial testing, directly impacting influenza vaccine validation by generating robust efficacy data to support broader institutional integration.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Influenza Vaccine Market insights. See full methodology.

Market Scope
Page number 305
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 8.2%
Market growth 2026-2030 USD 4410.0 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.8%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Taiwan, Brazil, Australia, Saudi Arabia, South Africa, UAE, Argentina, Israel and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • Strategic resource allocation within the influenza vaccine is increasingly defined by the integration of agile biological platforms and rigorous compliance standards. Institutional procurement models are rapidly adopting next-generation immunization and multivalent composition frameworks to address complex mutational risks. By leveraging advanced genetic sequencing, manufacturing networks have improved strain matching accuracy by 24%, directly lowering the incidence of breakthrough infections.
  • This operational shift fundamentally enhances inoculation protocols and supports universal targeting initiatives. Furthermore, transitioning to alternative production methods minimizes the inherent vulnerabilities of traditional viral propagation, allowing facilities to streamline quality assurance workflows. From a boardroom perspective, investing in recombinant technology addresses critical compliance requirements while mitigating the financial impacts of seasonal supply chain disruptions.
  • As regulatory agencies tighten biological efficacy thresholds, the systematic implementation of these advanced development modalities ensures that supply networks maintain robust alignment with both acute clinical demands and long-term institutional budgeting strategies.

What are the Key Data Covered in this Influenza Vaccine Market Research and Growth Report?

  • What is the expected growth of the Influenza Vaccine Market between 2026 and 2030?

    • USD 4.41 billion, at a CAGR of 8.2%

  • What segmentation does the market report cover?

    • The report is segmented by Distribution Channel (Hospitals and pharmacies, Government and institutional, and Others), Type (LAIV, and RIV), Age Group (Adult, Geriatric, and Pediatric), Route of Administration (Intramuscular (IM) injection, and Intranasal spray) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Expanding government immunization and public health preparedness initiatives, Challenges in strain prediction and vaccine effectiveness

  • Who are the major players in the Influenza Vaccine Market?

    • Abbott Laboratories, AstraZeneca Plc, Bharat Biotech Ltd., Cadila Pharmaceuticals Ltd., Changchun BaiKe Biotechnology Co, CSL Seqirus USA Inc., Daiichi Sankyo Co. Ltd., GC Biopharma Corp., GlaxoSmithKline Plc, Hualan Biological Engineering Inc, KM Biologics Co. Ltd., Moderna Inc., Sanofi SA, Serum Institute of India Ltd., Sinovac Biotech Ltd., SK Bioscience, Viatris Inc. and Zydus Lifesciences Ltd.

Market Research Insights

  • The influenza vaccine is rapidly modernizing to address shifting epidemiological profiles and complex biological demands. By integrating advanced digital monitoring, organizations have enhanced forecast accuracy by 18%, significantly reducing seasonal inventory deficits. The strategic prioritization of routine immunization combined with targeted disease reduction initiatives allows institutional buyers to optimize procurement cycles.
  • Furthermore, expanding public health frameworks drives the adoption of sophisticated biological cultivation techniques, improving overall yield efficiency by 15%. This strategic alignment not only mitigates clinical friction but also ensures that the healthcare infrastructure remains highly responsive to emergent respiratory threats, ultimately lowering systemic operational costs and fortifying long-term resilience.

We can help! Our analysts can customize this influenza vaccine market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Age Group
Executive Summary - Chart on Market Segmentation by Route of Administration
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Influenza Vaccine Market 2020 - 2024

Historic Market Size - Data Table on Global Influenza Vaccine Market 2020 - 2024 ($ million)

5.2 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.4 Age Group segment analysis 2020 - 2024

Historic Market Size - Age Group Segment 2020 - 2024 ($ million)

5.5 Route of Administration segment analysis 2020 - 2024

Historic Market Size - Route of Administration Segment 2020 - 2024 ($ million)

5.6 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.7 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global influenza vaccine market

6.2 Impact of geopolitical conflicts on global influenza vaccine market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Distribution Channel

8.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

8.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

8.3 Hospitals and pharmacies - Market size and forecast 2025-2030

Chart on Hospitals and pharmacies - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals and pharmacies - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals and pharmacies - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals and pharmacies - Year-over-year growth 2025-2030 (%)

8.4 Government and institutional - Market size and forecast 2025-2030

Chart on Government and institutional - Market size and forecast 2025-2030 ($ million)
Data Table on Government and institutional - Market size and forecast 2025-2030 ($ million)
Chart on Government and institutional - Year-over-year growth 2025-2030 (%)
Data Table on Government and institutional - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 LAIV - Market size and forecast 2025-2030

Chart on LAIV - Market size and forecast 2025-2030 ($ million)
Data Table on LAIV - Market size and forecast 2025-2030 ($ million)
Chart on LAIV - Year-over-year growth 2025-2030 (%)
Data Table on LAIV - Year-over-year growth 2025-2030 (%)

9.4 RIV - Market size and forecast 2025-2030

Chart on RIV - Market size and forecast 2025-2030 ($ million)
Data Table on RIV - Market size and forecast 2025-2030 ($ million)
Chart on RIV - Year-over-year growth 2025-2030 (%)
Data Table on RIV - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

10. Market Segmentation by Age Group

10.1 Market segments

Chart on Age Group - Market share 2025-2030 (%)
Data Table on Age Group - Market share 2025-2030 (%)

10.2 Comparison by Age Group

Chart on Comparison by Age Group
Data Table on Comparison by Age Group

10.3 Adult - Market size and forecast 2025-2030

Chart on Adult - Market size and forecast 2025-2030 ($ million)
Data Table on Adult - Market size and forecast 2025-2030 ($ million)
Chart on Adult - Year-over-year growth 2025-2030 (%)
Data Table on Adult - Year-over-year growth 2025-2030 (%)

10.4 Geriatric - Market size and forecast 2025-2030

Chart on Geriatric - Market size and forecast 2025-2030 ($ million)
Data Table on Geriatric - Market size and forecast 2025-2030 ($ million)
Chart on Geriatric - Year-over-year growth 2025-2030 (%)
Data Table on Geriatric - Year-over-year growth 2025-2030 (%)

10.5 Pediatric - Market size and forecast 2025-2030

Chart on Pediatric - Market size and forecast 2025-2030 ($ million)
Data Table on Pediatric - Market size and forecast 2025-2030 ($ million)
Chart on Pediatric - Year-over-year growth 2025-2030 (%)
Data Table on Pediatric - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Age Group

Market opportunity by Age Group ($ million)
Data Table on Market opportunity by Age Group ($ million)

11. Market Segmentation by Route of Administration

11.1 Market segments

Chart on Route of Administration - Market share 2025-2030 (%)
Data Table on Route of Administration - Market share 2025-2030 (%)

11.2 Comparison by Route of Administration

Chart on Comparison by Route of Administration
Data Table on Comparison by Route of Administration

11.3 Intramuscular (IM) injection - Market size and forecast 2025-2030

Chart on Intramuscular (IM) injection - Market size and forecast 2025-2030 ($ million)
Data Table on Intramuscular (IM) injection - Market size and forecast 2025-2030 ($ million)
Chart on Intramuscular (IM) injection - Year-over-year growth 2025-2030 (%)
Data Table on Intramuscular (IM) injection - Year-over-year growth 2025-2030 (%)

11.4 Intranasal spray - Market size and forecast 2025-2030

Chart on Intranasal spray - Market size and forecast 2025-2030 ($ million)
Data Table on Intranasal spray - Market size and forecast 2025-2030 ($ million)
Chart on Intranasal spray - Year-over-year growth 2025-2030 (%)
Data Table on Intranasal spray - Year-over-year growth 2025-2030 (%)

11.5 Market opportunity by Route of Administration

Market opportunity by Route of Administration ($ million)
Data Table on Market opportunity by Route of Administration ($ million)

12. Customer Landscape

12.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

13. Geographic Landscape

13.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

13.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

13.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

13.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

13.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

13.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

13.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

13.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

13.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

13.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

13.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

13.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

13.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

13.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

13.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

13.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

13.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

13.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

13.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

13.5.6 Taiwan - Market size and forecast 2025-2030

Chart on Taiwan - Market size and forecast 2025-2030 ($ million)
Data Table on Taiwan - Market size and forecast 2025-2030 ($ million)
Chart on Taiwan - Year-over-year growth 2025-2030 (%)
Data Table on Taiwan - Year-over-year growth 2025-2030 (%)

13.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

13.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

13.6.2 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

13.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

13.6.4 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

13.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

13.6.6 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

13.6.7 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

13.6.8 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

13.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

14. Drivers, Challenges, and Opportunity

14.1 Market drivers

Expanding government immunization and public health preparedness initiatives
Rising geriatric population and influenza complication burden
Advancements in vaccine technologies and product innovation

14.2 Market challenges

Challenges in strain prediction and vaccine effectiveness
High manufacturing complexity and cold-chain management requirements
Uneven vaccination access and adoption across populations

14.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

14.4 Market opportunities

Increasing integration of combination respiratory immunization approaches
Growing emphasis on diversified vaccine platform portfolios
Expansion of data-driven influenza surveillance and forecasting networks

15. Competitive Landscape

15.1 Overview

15.2

Overview on criticality of inputs and factors of differentiation

15.3 Landscape disruption

Overview on factors of disruption

15.4 Industry risks

Impact of key risks on business

16. Competitive Analysis

16.1 Companies profiled

Companies covered

16.2 Company ranking index

16.3 Market positioning of companies

Matrix on companies position and classification

16.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

16.5 AstraZeneca Plc

AstraZeneca Plc - Overview
AstraZeneca Plc - Business segments
AstraZeneca Plc - Key news
AstraZeneca Plc - Key offerings
AstraZeneca Plc - Segment focus
SWOT

16.6 Bharat Biotech Ltd.

Bharat Biotech Ltd. - Overview
Bharat Biotech Ltd. - Product / Service
Bharat Biotech Ltd. - Key offerings
SWOT

16.7 Cadila Pharmaceuticals Ltd.

Cadila Pharmaceuticals Ltd. - Overview
Cadila Pharmaceuticals Ltd. - Product / Service
Cadila Pharmaceuticals Ltd. - Key offerings
SWOT

16.8 Changchun BaiKe Biotechnology Co

Changchun BaiKe Biotechnology Co - Overview
Changchun BaiKe Biotechnology Co - Product / Service
Changchun BaiKe Biotechnology Co - Key offerings
SWOT

16.9 Daiichi Sankyo Co. Ltd.

Daiichi Sankyo Co. Ltd. - Overview
Daiichi Sankyo Co. Ltd. - Business segments
Daiichi Sankyo Co. Ltd. - Key news
Daiichi Sankyo Co. Ltd. - Key offerings
Daiichi Sankyo Co. Ltd. - Segment focus
SWOT

16.10 GC Biopharma Corp.

GC Biopharma Corp. - Overview
GC Biopharma Corp. - Business segments
GC Biopharma Corp. - Key offerings
GC Biopharma Corp. - Segment focus
SWOT

16.11 GlaxoSmithKline Plc

GlaxoSmithKline Plc - Overview
GlaxoSmithKline Plc - Business segments
GlaxoSmithKline Plc - Key news
GlaxoSmithKline Plc - Key offerings
GlaxoSmithKline Plc - Segment focus
SWOT

16.12 Hualan Biological Engineering Inc

Hualan Biological Engineering Inc - Overview
Hualan Biological Engineering Inc - Business segments
Hualan Biological Engineering Inc - Key offerings
Hualan Biological Engineering Inc - Segment focus
SWOT

16.13 Moderna Inc.

Moderna Inc. - Overview
Moderna Inc. - Product / Service
Moderna Inc. - Key offerings
SWOT

16.14 Sanofi SA

Sanofi SA - Overview
Sanofi SA - Business segments
Sanofi SA - Key news
Sanofi SA - Key offerings
Sanofi SA - Segment focus
SWOT

16.15 Sinovac Biotech Ltd.

Sinovac Biotech Ltd. - Overview
Sinovac Biotech Ltd. - Product / Service
Sinovac Biotech Ltd. - Key offerings
SWOT

16.16 SK Bioscience

SK Bioscience - Overview
SK Bioscience - Product / Service
SK Bioscience - Key offerings
SWOT

16.17 Viatris Inc.

Viatris Inc. - Overview
Viatris Inc. - Business segments
Viatris Inc. - Key news
Viatris Inc. - Key offerings
Viatris Inc. - Segment focus
SWOT

16.18 Zydus Lifesciences Ltd.

Zydus Lifesciences Ltd. - Overview
Zydus Lifesciences Ltd. - Business segments
Zydus Lifesciences Ltd. - Key news
Zydus Lifesciences Ltd. - Key offerings
Zydus Lifesciences Ltd. - Segment focus
SWOT

17. Appendix

17.1 Scope of the report

Market definition
Objectives
Notes and caveats

17.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

17.3 Currency conversion rates for US$

17.4 Research methodology

17.5 Data procurement

Information sources

17.6 Data validation

17.7 Validation techniques employed for market sizing

17.8 Data synthesis

17.9 360 degree market analysis

17.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Influenza Vaccine market growth will increase by USD 4410.0 million during 2026-2030.

The Influenza Vaccine market is expected to grow at a CAGR of 8.2% during 2026-2030.

Influenza Vaccine market is segmented by Distribution channel (Hospitals and pharmacies, Government and institutional, Others) Type (LAIV, RIV) Age group (Adult, Geriatric, Pediatric) Route of administration (Intramuscular (IM) injection, Intranasal spray)

Abbott Laboratories, AstraZeneca Plc, Bharat Biotech Ltd., Cadila Pharmaceuticals Ltd., Changchun BaiKe Biotechnology Co, CSL Seqirus USA Inc., Daiichi Sankyo Co. Ltd., GC Biopharma Corp., GlaxoSmithKline Plc, Hualan Biological Engineering Inc, KM Biologics Co. Ltd., Moderna Inc., Sanofi SA, Serum Institute of India Ltd., Sinovac Biotech Ltd., SK Bioscience, Viatris Inc., Zydus Lifesciences Ltd. are a few of the key vendors in the Influenza Vaccine market.

North America will register the highest growth rate of 52.4% among the other regions. Therefore, the Influenza Vaccine market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Indonesia, Taiwan, Brazil, Australia, Saudi Arabia, South Africa, UAE, Argentina, Israel, Chile

  • Expanding government immunization and public health preparedness initiatives is the driving factor this market.

The Influenza Vaccine market vendors should focus on grabbing business opportunities from the Distribution channel segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
