North America Financial Advisory Services Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico)

North America Financial Advisory Services Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico)

Published: May 2026 220 Pages SKU: IRTNTR77561

Market Overview at a Glance

$10.50 B
Market Opportunity
4.8%
CAGR 2025 - 2030
4.6%
YoY growth 2025-2026(%)
$10.93 B
Corporate finance segment 2024

North America Financial Advisory Services Market Size 2026-2030

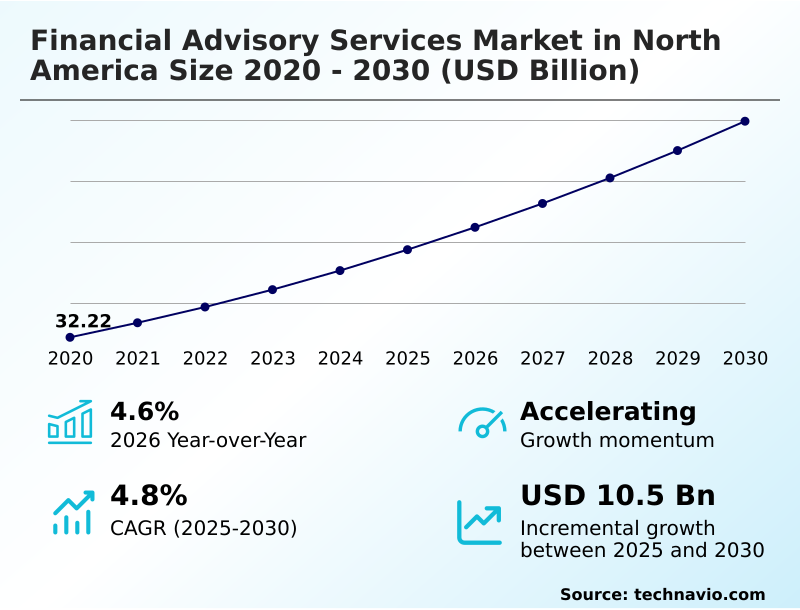
The north america financial advisory services market size is valued to increase by USD 10.50 billion, at a CAGR of 4.8% from 2025 to 2030. Rising complexity of global financial markets and cross-border transactions will drive the north america financial advisory services market.

Major Market Trends & Insights

  • By Service - Corporate finance segment was valued at USD 10.93 billion in 2024
  • By End-user - Large enterprises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 17.67 billion
  • Market Future Opportunities: USD 10.50 billion
  • CAGR from 2025 to 2030 : 4.8%

Market Summary

  • The Financial Advisory Services is driven by the escalating demand for highly sophisticated wealth preservation techniques and stringent fiduciary duty compliance. A core driver is the rising complexity of cross border taxation and regulatory environments, compelling multinational corporations to seek specialized counsel for continuous tax loss harvesting and strategic acquisitions.
  • For example, large enterprises optimizing their supply chain financing frequently engage advisors to restructure debt, which has led to a 20% reduction in capital carrying costs compared to traditional funding models. Conversely, the market faces significant challenges from sophisticated cyber threats targeting sensitive financial data, requiring substantial diversion of capital into defensive infrastructure.
  • As digital adoption accelerates, the integration of robo advisory platforms democratizes access to tailored investment strategies, yet traditional firms must balance this automation with high-touch human oversight to maintain trust and navigate complex compliance obligations effectively.

What will be the Size of the North America Financial Advisory Services Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the North America Financial Advisory Services Market Segmented?

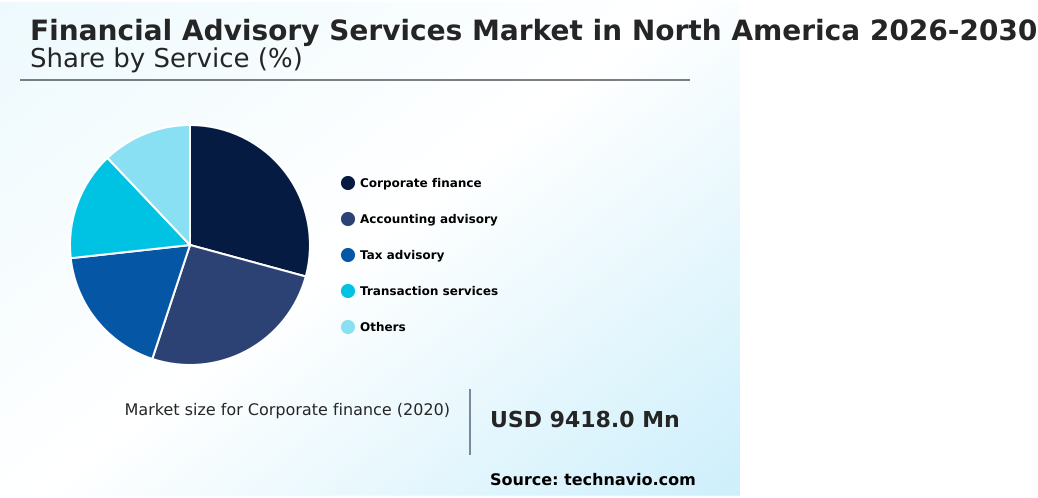
The north america financial advisory services industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Service
    • Corporate finance
    • Accounting advisory
    • Tax advisory
    • Transaction services
    • Others
  • End-user
    • Large enterprises
    • SMEs
  • Application
    • BFSI
    • IT and telecom
    • Manufacturing
    • Retail and e-commerce
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico

By Service Insights

The corporate finance segment is estimated to witness significant growth during the forecast period.

Corporate finance acts as the foundational segment within the Financial Advisory Services, structuring critical strategies for capital allocation modeling and mergers and acquisitions advisory. Advisors execute sophisticated transaction due diligence to optimize liquidity management protocols across complex organizational frameworks.

Large enterprises relying on these corporate restructuring strategies experience improved transaction outcomes, often realizing a 15% enhancement in post merger integration efficiency.

Firms orchestrating capital structure optimization utilize predictive financial modeling to navigate structured debt instruments and secure venture capital funding seamlessly.

This segment continually adapts to complex market demands, providing private equity allocations and institutional capital raising frameworks that ensure working capital analysis remains precise, driving sustained operational stability and maximizing shareholder value across diverse corporate portfolios.
Get Free Sample

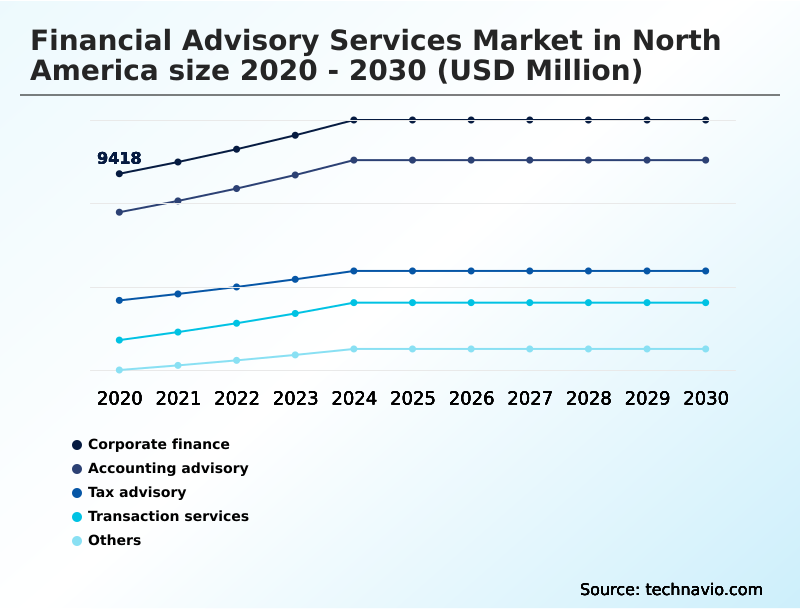
The Corporate finance segment was valued at USD 10.93 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The Financial Advisory Services operates as a highly intricate ecosystem demanding specialized expertise to navigate shifting economic paradigms and regulatory mandates. A primary focus for multinational organizations involves rigorous corporate finance capital structure optimization to ensure adequate liquidity while minimizing borrowing costs.
  • This optimization is critical when compared to legacy debt management, offering a marked 25% reduction in overall interest liabilities and strengthening enterprise resilience. Simultaneously, businesses expanding internationally heavily rely on sophisticated cross border tax advisory solutions to mitigate compliance risks and enhance global operational efficiency.
  • Furthermore, the mandatory implementation of fiduciary duty compliance audit protocols ensures that institutional and retail assets are managed with complete transparency, fundamentally altering how advisory practices structure their internal governance. For private clients, the deployment of intergenerational wealth transfer planning models is essential for preserving family legacies while adapting to the unique values and digital expectations of younger beneficiaries.
  • To meet these technological expectations, firms are accelerating their digital robo advisory platform integration, which enhances client accessibility and significantly lowers client acquisition costs. These interconnected services enable advisory organizations to offer a comprehensive, resilient, and forward-looking financial framework tailored to both complex corporate entities and high-net-worth individuals.
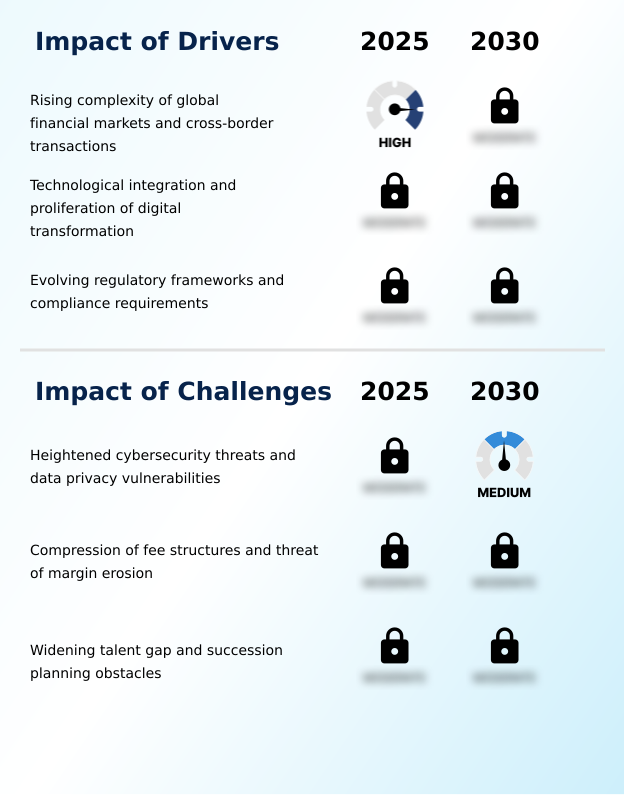
What are the key market drivers leading to the rise in the adoption of North America Financial Advisory Services Industry?

  • The escalating complexity of global financial markets and the proliferation of cross-border transactions serve as primary drivers for specialized advisory demand.

  • The escalating complexity of regulatory frameworks acts as a primary driver for the Financial Advisory Services.
  • As multinational enterprises expand operations, the intricate requirements of strict fiduciary standard adherence, fiduciary duty compliance, and new revenue recognition standards force companies to seek specialized counsel.
  • This reliance on expert advisory and regulatory compliance auditing has resulted in a 25% decrease in compliance-related penalties for large corporations.
  • Furthermore, the integration of AI-driven predictive financial modeling enables advisors to rapidly synthesize vast datasets, improving risk forecasting accuracy by 18%.
  • The need for precise quality of earnings analysis, asset liability management, alongside accurate purchase price allocation and goodwill impairment testing during corporate acquisitions, directly fuels the demand for transaction services.
  • Ultimately, these drivers ensure that organizations navigate fragmented legal landscapes efficiently while optimizing strategic capital deployments.

What are the market trends shaping the North America Financial Advisory Services Industry?

  • The great generational wealth transfer and shifting client demographics represent a defining trend reshaping the market. This unprecedented transition demands highly personalized advisory models to engage younger beneficiaries effectively.

  • A transformative trend defining the Financial Advisory Services is the rapid democratization of evergreen fund deployment and interval fund structures. This shift is caused by prolonged public market volatility, pushing investors toward alternative investment structuring with lower market correlation.
  • Consequently, firms are heavily investing in digital wealth management platforms, which has improved client access to private markets by 35%, accelerating broader private market integration. This integration allows mass-affluent investors to benefit from sophisticated portfolio diversification strategies and wealth preservation techniques previously reserved for institutional players.
  • Furthermore, the demand for hyper-personalized investments has accelerated the use of separately managed accounts, driving a 20% increase in portfolio customization efficiency. These trends compel advisory practices to elevate technical capabilities, ensuring comprehensive sustainability risk assessment and robust long-term growth for a broader demographic.

What challenges does the North America Financial Advisory Services Industry face during its growth?

  • Heightened cybersecurity threats and escalating data privacy vulnerabilities pose significant challenges, necessitating substantial investments in protective digital infrastructure.

  • A formidable challenge constraining the Financial Advisory Services is the escalation of cyber threats targeting sensitive client data alongside stringent data privacy mandates. Because advisory firms increasingly rely on cloud architectures, they inadvertently expand attack surfaces, compelling organizations to divert capital toward cybersecurity threat detection and advanced encryption, increasing operational overhead by 22% annually.
  • Additionally, the industry grapples with margin compression due to low-cost automated platforms. This fee pressure challenges firms to maintain profitability while delivering resource-intensive services to high net worth and ultra high net worth clients. The complexities surrounding intergenerational wealth transfer demand bespoke estate planning frameworks, intricate family office governance structures, and complex succession planning structures, necessitating robust fiduciary risk mitigation.
  • Consequently, advisory practices must rigorously optimize workflows to sustain high-touch client relationships without sacrificing their operational viability.

Exclusive Technavio Analysis on Customer Landscape

The north america financial advisory services market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the north america financial advisory services market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
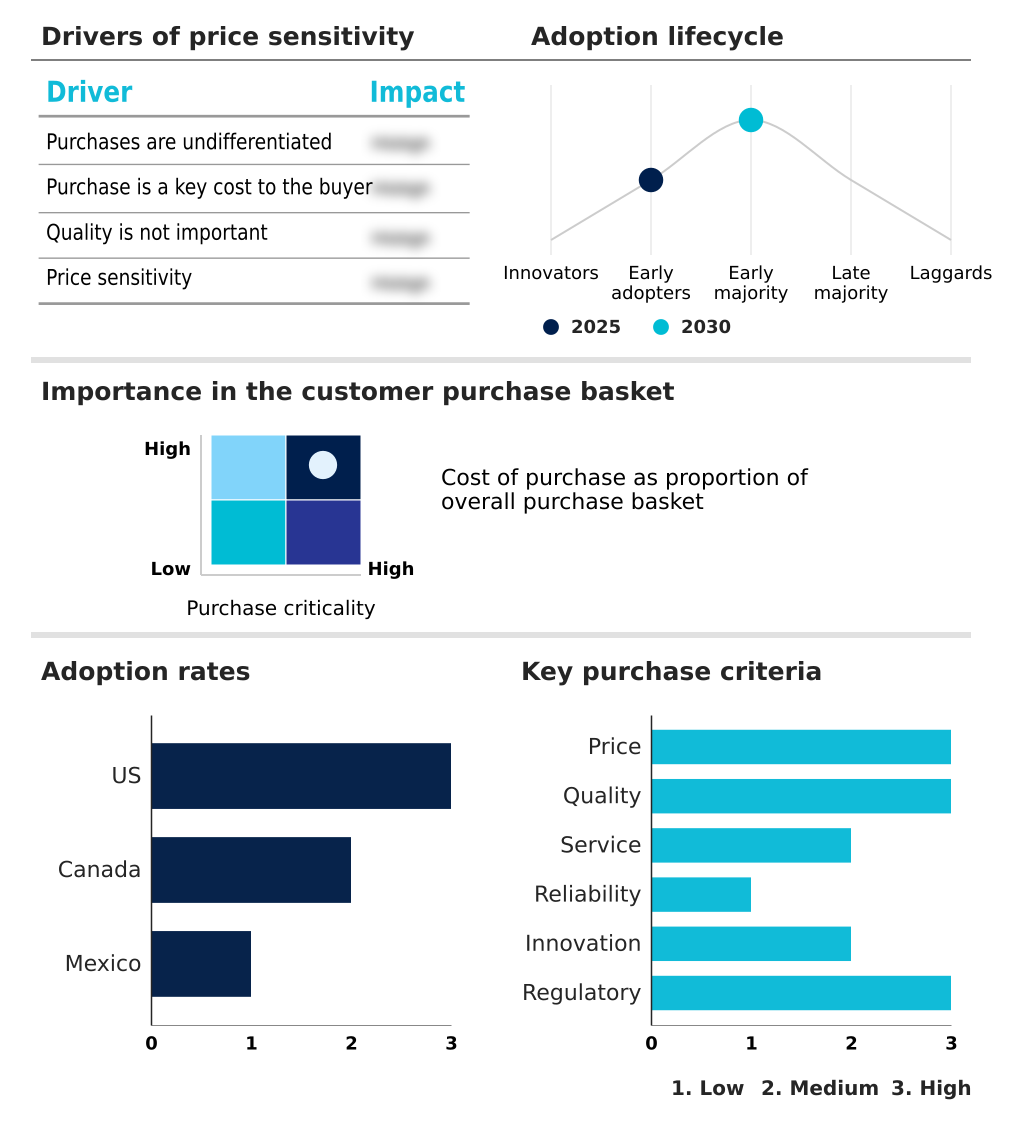
Customer Landscape of North America Financial Advisory Services Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, north america financial advisory services market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Ameriprise Financial Inc. - Delivers comprehensive wealth management, robust investment advisory, and tailored retirement planning solutions to optimize asset growth and ensure strategic financial stability for diverse client portfolios.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Ameriprise Financial Inc.
  • Bain and Co. Inc.
  • Bank of America Corp.
  • BlackRock Inc.
  • Boston Consulting Group Inc.
  • Citigroup Inc.
  • Deloitte Touche Tohmatsu Ltd.
  • Deutsche Bank AG
  • Ernst and Young Global Ltd.
  • Fidelity Investments
  • JPMorganChase
  • McKinsey and Co.
  • Morgan Stanley
  • PricewaterhouseCoopers LLP
  • State Street Corp.
  • The Charles Schwab Corp.
  • The Goldman Sachs Group Inc.
  • The Vanguard Group Inc.
  • UBS Group AG
  • Wells Fargo and Co.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in North america financial advisory services market

  • In the Specialized Consumer Services industry, the accelerated integration of digital wealth management tools has modernized client engagement, directly impacting Financial Advisory Services demand by increasing the adoption of automated reporting tools by 25%.
  • The enforcement of stricter data privacy mandates across consumer service sectors has mandated comprehensive cybersecurity threat detection upgrades, increasing the need for fiduciary risk mitigation and compliance advisory.
  • A structural shift toward environmental social governance frameworks in consumer spending has reshaped alternative investment structuring, prompting advisory firms to develop new sustainability risk assessment methodologies.
  • The rising frequency of intergenerational wealth transfer within private client services has expanded family office governance, elevating the demand for specialized estate planning frameworks and succession planning structures.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled North America Financial Advisory Services Market insights. See full methodology.

Market Scope
Page number 220
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.8%
Market growth 2026-2030 USD 10502.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 4.6%
Key countries US, Canada and Mexico
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Financial Advisory Services continuously adapts to structural economic shifts and the rapid digitization of wealth management protocols. A pivotal trend is the democratization of private market integration, which directly influences boardroom-level decisions regarding alternative investment structuring and institutional capital raising.
  • By moving beyond traditional public equities, firms have achieved a 30% reduction in overall portfolio volatility during turbulent economic cycles. Furthermore, the stringent requirements of asset liability management compel enterprises to execute precise purchase price allocation and rigorous goodwill impairment testing during complex merger events.
  • Boardrooms are increasingly prioritizing these valuation metrics to ensure accurate financial reporting and to support strategic long-term acquisitions. This evolution demands that advisory professionals not only provide transactional support but also deliver holistic risk management frameworks that safeguard enterprise value.
  • Consequently, the reliance on specialized advisory partnerships has become an essential operational mandate for organizations seeking sustainable expansion and strict adherence to evolving global compliance standards.

What are the Key Data Covered in this North America Financial Advisory Services Market Research and Growth Report?

  • What is the expected growth of the North America Financial Advisory Services Market between 2026 and 2030?

    • USD 10.50 billion, at a CAGR of 4.8%

  • What segmentation does the market report cover?

    • The report is segmented by Service (Corporate finance, Accounting advisory, Tax advisory, Transaction services, and Others), End-user (Large enterprises, and SMEs), Application (BFSI, IT and telecom, Manufacturing, Retail and e-commerce, and Others) and Geography (North America)

  • Which regions are analyzed in the report?

    • North America

  • What are the key growth drivers and market challenges?

    • Rising complexity of global financial markets and cross-border transactions, Heightened cybersecurity threats and data privacy vulnerabilities

  • Who are the major players in the North America Financial Advisory Services Market?

    • Ameriprise Financial Inc., Bain and Co. Inc., Bank of America Corp., BlackRock Inc., Boston Consulting Group Inc., Citigroup Inc., Deloitte Touche Tohmatsu Ltd., Deutsche Bank AG, Ernst and Young Global Ltd., Fidelity Investments, JPMorganChase, McKinsey and Co., Morgan Stanley, PricewaterhouseCoopers LLP, State Street Corp., The Charles Schwab Corp., The Goldman Sachs Group Inc., The Vanguard Group Inc., UBS Group AG and Wells Fargo and Co.

Market Research Insights

  • The Financial Advisory Services continuously evolves to address intricate client demands through advanced separately managed accounts and hyper-personalized strategies. The rapid democratization of interval fund structures has increased alternative asset participation by 30%, reshaping traditional portfolio models. High net worth demographics increasingly require robust ultra high net worth advisory frameworks, driving a 25% improvement in tax optimization efficiency.
  • Furthermore, the mandatory adoption of strict revenue recognition standards has enhanced corporate reporting accuracy by 18%. This structural transformation ensures that advisory firms deliver highly targeted, compliance-driven insights, solidifying their role in long-term wealth generation and precise capital management.

We can help! Our analysts can customize this north america financial advisory services market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Country Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Service
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Overview on factors of disruption

2.4 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on Regional - Market size and forecast 2025-2030 ($ million)
Chart on North America: Year-over-year growth 2025-2030 (%)
Data Table on Regional - Market size and forecast 2025-2030 ($ million)

5. Historic Market Size

5.1 Financial Advisory Services Market in North America 2020 - 2024

Historic Market Size - Data Table on Financial Advisory Services Market in North America 2020 - 2024 ($ million)

5.2 Service segment analysis 2020 - 2024

Historic Market Size - Service Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on financial advisory services market in North America

6.2 Impact of geopolitical conflicts on financial advisory services market in North America

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Service

8.1 Market segments

Chart on Service - Market share 2025-2030 (%)
Data Table on Service - Market share 2025-2030 (%)

8.2 Comparison by Service

Chart on Comparison by Service
Data Table on Comparison by Service

8.3 Corporate finance - Market size and forecast 2025-2030

Chart on Corporate finance - Market size and forecast 2025-2030 ($ million)
Data Table on Corporate finance - Market size and forecast 2025-2030 ($ million)
Chart on Corporate finance - Year-over-year growth 2025-2030 (%)
Data Table on Corporate finance - Year-over-year growth 2025-2030 (%)

8.4 Accounting advisory - Market size and forecast 2025-2030

Chart on Accounting advisory - Market size and forecast 2025-2030 ($ million)
Data Table on Accounting advisory - Market size and forecast 2025-2030 ($ million)
Chart on Accounting advisory - Year-over-year growth 2025-2030 (%)
Data Table on Accounting advisory - Year-over-year growth 2025-2030 (%)

8.5 Tax advisory - Market size and forecast 2025-2030

Chart on Tax advisory - Market size and forecast 2025-2030 ($ million)
Data Table on Tax advisory - Market size and forecast 2025-2030 ($ million)
Chart on Tax advisory - Year-over-year growth 2025-2030 (%)
Data Table on Tax advisory - Year-over-year growth 2025-2030 (%)

8.6 Transaction services - Market size and forecast 2025-2030

Chart on Transaction services - Market size and forecast 2025-2030 ($ million)
Data Table on Transaction services - Market size and forecast 2025-2030 ($ million)
Chart on Transaction services - Year-over-year growth 2025-2030 (%)
Data Table on Transaction services - Year-over-year growth 2025-2030 (%)

8.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Service

Market opportunity by Service ($ million)
Data Table on Market opportunity by Service ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Large enterprises - Market size and forecast 2025-2030

Chart on Large enterprises - Market size and forecast 2025-2030 ($ million)
Data Table on Large enterprises - Market size and forecast 2025-2030 ($ million)
Chart on Large enterprises - Year-over-year growth 2025-2030 (%)
Data Table on Large enterprises - Year-over-year growth 2025-2030 (%)

9.4 SMEs - Market size and forecast 2025-2030

Chart on SMEs - Market size and forecast 2025-2030 ($ million)
Data Table on SMEs - Market size and forecast 2025-2030 ($ million)
Chart on SMEs - Year-over-year growth 2025-2030 (%)
Data Table on SMEs - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 BFSI - Market size and forecast 2025-2030

Chart on BFSI - Market size and forecast 2025-2030 ($ million)
Data Table on BFSI - Market size and forecast 2025-2030 ($ million)
Chart on BFSI - Year-over-year growth 2025-2030 (%)
Data Table on BFSI - Year-over-year growth 2025-2030 (%)

10.4 IT and telecom - Market size and forecast 2025-2030

Chart on IT and telecom - Market size and forecast 2025-2030 ($ million)
Data Table on IT and telecom - Market size and forecast 2025-2030 ($ million)
Chart on IT and telecom - Year-over-year growth 2025-2030 (%)
Data Table on IT and telecom - Year-over-year growth 2025-2030 (%)

10.5 Manufacturing - Market size and forecast 2025-2030

Chart on Manufacturing - Market size and forecast 2025-2030 ($ million)
Data Table on Manufacturing - Market size and forecast 2025-2030 ($ million)
Chart on Manufacturing - Year-over-year growth 2025-2030 (%)
Data Table on Manufacturing - Year-over-year growth 2025-2030 (%)

10.6 Retail and e-commerce - Market size and forecast 2025-2030

Chart on Retail and e-commerce - Market size and forecast 2025-2030 ($ million)
Data Table on Retail and e-commerce - Market size and forecast 2025-2030 ($ million)
Chart on Retail and e-commerce - Year-over-year growth 2025-2030 (%)
Data Table on Retail and e-commerce - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography - 2025-2030 (%)
Data Table on Market share by geography - 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.4 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 Market opportunity by geography

Market opportunity by geography ($ million)
Data Table on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising complexity of global financial markets and cross-border transactions
Technological integration and proliferation of digital transformation
Evolving regulatory frameworks and compliance requirements

13.2 Market challenges

Heightened cybersecurity threats and data privacy vulnerabilities
Compression of fee structures and threat of margin erosion
Widening talent gap and succession planning obstacles

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Great generational wealth transfer and shifting client demographics
Expansion of private markets and alternative asset integration
Hyper-personalization through direct indexing and tailored solutions

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Ameriprise Financial Inc.

Ameriprise Financial Inc. - Overview
Ameriprise Financial Inc. - Business segments
Ameriprise Financial Inc. - Key offerings
Ameriprise Financial Inc. - Segment focus
SWOT

15.5 Bank of America Corp.

Bank of America Corp. - Overview
Bank of America Corp. - Business segments
Bank of America Corp. - Key news
Bank of America Corp. - Key offerings
Bank of America Corp. - Segment focus
SWOT

15.6 BlackRock Inc.

BlackRock Inc. - Overview
BlackRock Inc. - Product / Service
BlackRock Inc. - Key offerings
SWOT

15.7 Citigroup Inc.

Citigroup Inc. - Overview
Citigroup Inc. - Business segments
Citigroup Inc. - Key offerings
Citigroup Inc. - Segment focus
SWOT

15.8 Deloitte Touche Tohmatsu Ltd.

Deloitte Touche Tohmatsu Ltd. - Overview
Deloitte Touche Tohmatsu Ltd. - Business segments
Deloitte Touche Tohmatsu Ltd. - Key offerings
Deloitte Touche Tohmatsu Ltd. - Segment focus
SWOT

15.9 Fidelity Investments

Fidelity Investments - Overview
Fidelity Investments - Product / Service
Fidelity Investments - Key offerings
SWOT

15.10 JPMorganChase

JPMorganChase - Overview
JPMorganChase - Product / Service
JPMorganChase - Key offerings
SWOT

15.11 Morgan Stanley

Morgan Stanley - Overview
Morgan Stanley - Business segments
Morgan Stanley - Key offerings
Morgan Stanley - Segment focus
SWOT

15.12 PricewaterhouseCoopers LLP

PricewaterhouseCoopers LLP - Overview
PricewaterhouseCoopers LLP - Product / Service
PricewaterhouseCoopers LLP - Key offerings
SWOT

15.13 State Street Corp.

State Street Corp. - Overview
State Street Corp. - Business segments
State Street Corp. - Key offerings
State Street Corp. - Segment focus
SWOT

15.14 The Charles Schwab Corp.

The Charles Schwab Corp. - Overview
The Charles Schwab Corp. - Business segments
The Charles Schwab Corp. - Key news
The Charles Schwab Corp. - Key offerings
The Charles Schwab Corp. - Segment focus
SWOT

15.15 The Goldman Sachs Group Inc.

The Goldman Sachs Group Inc. - Overview
The Goldman Sachs Group Inc. - Business segments
The Goldman Sachs Group Inc. - Key offerings
The Goldman Sachs Group Inc. - Segment focus
SWOT

15.16 The Vanguard Group Inc.

The Vanguard Group Inc. - Overview
The Vanguard Group Inc. - Product / Service
The Vanguard Group Inc. - Key offerings
SWOT

15.17 UBS Group AG

UBS Group AG - Overview
UBS Group AG - Business segments
UBS Group AG - Key offerings
UBS Group AG - Segment focus
SWOT

15.18 Wells Fargo and Co.

Wells Fargo and Co. - Overview
Wells Fargo and Co. - Business segments
Wells Fargo and Co. - Key offerings
Wells Fargo and Co. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

North America Financial Advisory Services market growth will increase by USD 10502.3 million during 2026-2030.

The North America Financial Advisory Services market is expected to grow at a CAGR of 4.8% during 2026-2030.

North America Financial Advisory Services market is segmented by Service (Corporate finance, Accounting advisory, Tax advisory, Transaction services, Others) End-user (Large enterprises, SMEs) Application (BFSI, IT and telecom, Manufacturing, Retail and e-commerce, Others)

Ameriprise Financial Inc., Bain and Co. Inc., Bank of America Corp., BlackRock Inc., Boston Consulting Group Inc., Citigroup Inc., Deloitte Touche Tohmatsu Ltd., Deutsche Bank AG, Ernst and Young Global Ltd., Fidelity Investments, JPMorganChase, McKinsey and Co., Morgan Stanley, PricewaterhouseCoopers LLP, State Street Corp., The Charles Schwab Corp., The Goldman Sachs Group Inc., The Vanguard Group Inc., UBS Group AG, Wells Fargo and Co. are a few of the key vendors in the North America Financial Advisory Services market.

North America will register the highest growth rate of 100% among the other regions. Therefore, the North America Financial Advisory Services market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico

  • Rising complexity of global financial markets and cross-border transactions is the driving factor this market.

The North America Financial Advisory Services market vendors should focus on grabbing business opportunities from the Service segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
