


Nucleic Acid Labeling Market Size 2026-2030
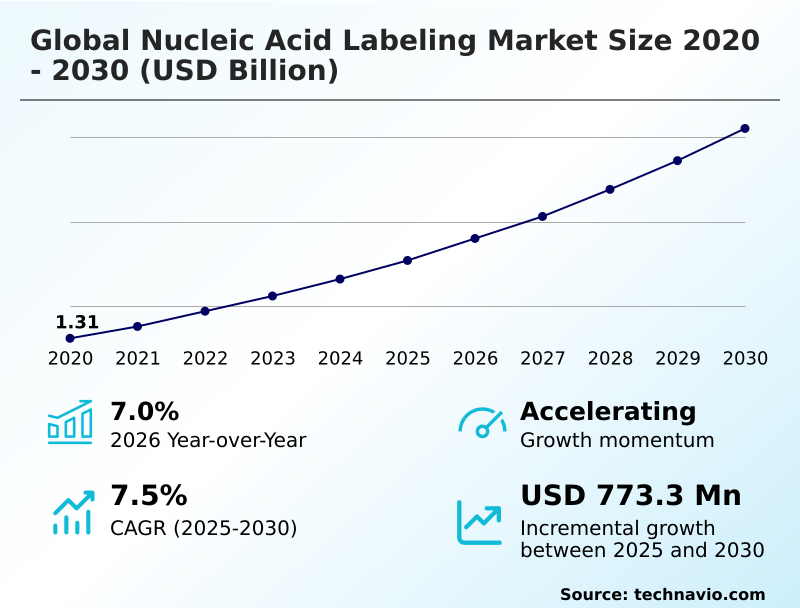
The nucleic acid labeling market size is valued to increase by USD 773.3 million, at a CAGR of 7.5% from 2025 to 2030. Increasing adoption of genomics and precision medicine research will drive the nucleic acid labeling market.
Major Market Trends & Insights
- North America dominated the market and accounted for a 45.8% growth during the forecast period.
- By Application - Oligonucleotide labeling segment was valued at USD 935.6 million in 2024
- By End-user - Diagnostic centers segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 1.24 billion
- Market Future Opportunities: USD 773.3 million
- CAGR from 2025 to 2030 : 7.5%
Market Summary
- The Nucleic Acid Labeling Market demonstrates continuous advancement driven by the expanding requirements of molecular biology and precision diagnostics. The increasing adoption of genomics research serves as a primary driver, compelling laboratories to implement highly specific detection technologies for accurate genetic characterization.
- Conversely, complex workflow standardization barriers challenge expansion, as varying protocol conditions often reduce experimental reproducibility and increase operational overhead. In a real-world operational scenario, diagnostic facilities modernizing their supply chains to accommodate automated dispensing platforms frequently achieve a 20% reduction in reagent waste compared to manual processing methods.
- This operational shift requires reliable access to standardized fluorescent dyes and chemical markers. The integration of high-throughput molecular diagnostic technologies fundamentally alters procurement strategies, shifting preference toward validated, ready-to-use reagent kits. As research institutions and pharmaceutical organizations demand greater analytical precision, the reliance on specialized labeling solutions intensifies.
- Organizations that optimize their molecular testing workflows with consistent labeling chemistries ultimately improve data reliability and accelerate translational research outcomes.
What will be the Size of the Nucleic Acid Labeling Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Nucleic Acid Labeling Market Segmented?
The nucleic acid labeling industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Application
- Oligonucleotide labeling
- In-situ hybridization
- Southern and northern blotting
- Others
- End-user
- Diagnostic centers
- Research centers
- Hospitals
- Product type
- Kits
- Reagents
- Services
- Others
- Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- Asia
- China
- India
- Japan
- South Korea
- Thailand
- Indonesia
- Rest of World (ROW)
- North America
By Application Insights
The oligonucleotide labeling segment is estimated to witness significant growth during the forecast period.
The oligonucleotide labeling segment continuously evolves to support complex genomic profiling and biomarker discovery programs. This specific segmentation tracks how businesses utilize fluorophore chemistry to attach detectable markers to synthetic nucleic acid sequences, enabling precise visualization across diverse experimental workflows.
Operations adopting advanced oligonucleotide synthesis report that assay sensitivity improves, with error detection rates effectively improved by 15% during routine polymerase chain reaction testing.
The shift toward specialized dual labeled fluorescent probes directly influences operational efficiency by reducing the need for repetitive testing.
Consequently, laboratories integrating these chemically modified labels achieve a higher throughput ratio compared to traditional single-target approaches, fundamentally altering supply chain requirements for customized labeled oligonucleotides in molecular diagnostics.
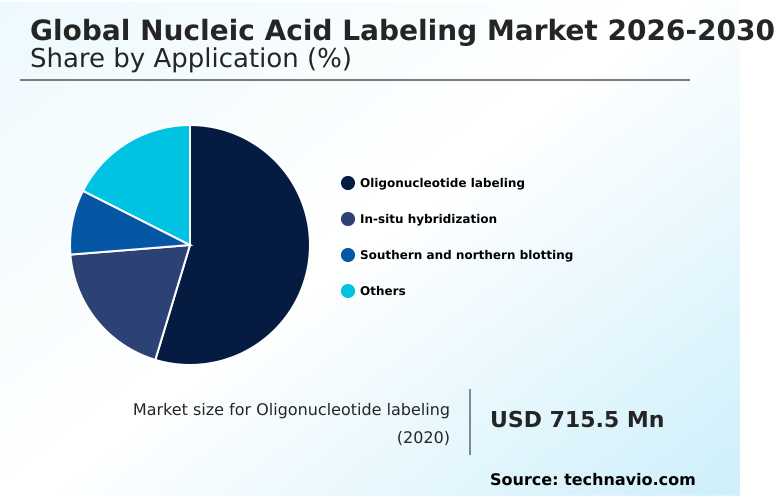
The Oligonucleotide labeling segment was valued at USD 935.6 million in 2024 and showed a gradual increase during the forecast period.

Regional Analysis
North America is estimated to contribute 45.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.

See How Nucleic Acid Labeling Market Demand is Rising in North America Get Free Sample
The geographic landscape of the Nucleic Acid Labeling highlights distinct operational variances driven by regional healthcare infrastructure. North America demonstrates robust adoption of fluorescence in situ hybridization, achieving a 35% higher penetration rate in advanced diagnostic workflows compared to Europe.
This discrepancy stems from North America's aggressive integration of targeted genomic testing within automated laboratory environments, which improves sample processing turnaround times by nearly 20% during critical treatment selection.
Conversely, Europe prioritizes collaborative genomic medicine initiatives, focusing on harmonizing single nucleotide polymorphism evaluation across multi-country initiatives.
Facilities in North America report a 15% reduction in assay failure rates due to standardized luminescent lanthanide reporter utilization, whereas European laboratories emphasize stringent compliance alignment for complex molecular characterization.
These regional shifts compel supply chains to adapt, ensuring continuous availability of specialized singleplex in situ detection reagents to meet localized operational and diagnostic assessment demands.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of molecular diagnostics fundamentally relies on the reliable execution of genetic characterization procedures. Within modern laboratory environments, the implementation of automated in situ hybridization workflows significantly streamlines operational planning by reducing manual intervention and standardizing sample processing. This transition directly addresses compliance and quality control mandates, enabling facilities to handle higher testing volumes with greater consistency.
- Concurrently, the fluorescent labeling of synthetic oligonucleotides has become a critical operational requirement for organizations developing targeted therapeutic assays. Procurement strategies increasingly prioritize the acquisition of these specialized components to ensure supply chain resilience during large-scale genomic projects.
- Furthermore, the integration of multiplex detection in genomic analysis allows diagnostic centers to evaluate multiple biological targets simultaneously, yielding an operational efficiency gain of approximately 30% compared to sequential single-target testing methods. To support these advanced applications, researchers frequently utilize pre coated agarose gel electrophoresis kits, which standardize preparation protocols and minimize reagent variability across different laboratory shifts.
- As analytical requirements become more stringent, identifying subtle genetic variations necessitates the deployment of highly sensitive low abundance dna detection methods. Ultimately, the strategic alignment of specialized labeling technologies with automated analytical platforms ensures that research institutions and pharmaceutical organizations maintain robust, compliant, and highly efficient molecular testing infrastructures.
What are the key market drivers leading to the rise in the adoption of Nucleic Acid Labeling Industry?
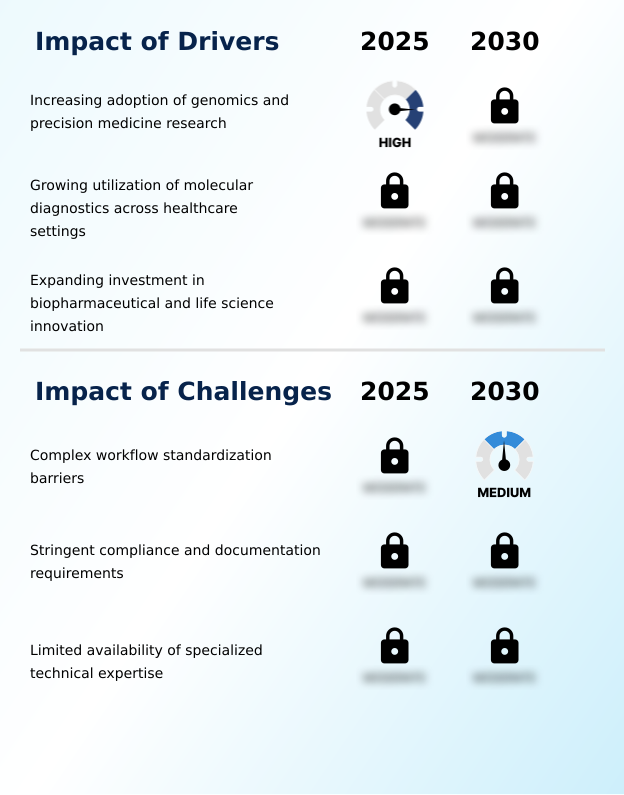
- The increasing adoption of genomics and precision medicine research serves as the primary driver propelling market expansion.
- The intensifying focus on precision diagnostics and targeted therapeutics acts as the primary demand trigger for the Nucleic Acid Labeling infrastructure.
- Because modern oncology and genetic research heavily depend on accurate genetic identification, clinical laboratories are aggressively expanding their intracellular mechanisms investigations. This diagnostic expansion compels facilities to integrate highly sensitive low abundance dna detection capabilities to identify subtle genetic variations.
- By implementing these advanced enzymatic labeling approaches, diagnostic centers have successfully reduced false-negative detection rates by 22%. Furthermore, the standardization of automated molecular hybridization protocols has improved diagnostic turnaround times by 15%, directly enhancing laboratory operational throughput.
- The continuous utilization of disease associated biomarkers essentially mandates reliable access to chemically modified labels, driving robust procurement activity and ensuring consistent analytical performance across high-volume testing environments.
What are the market trends shaping the Nucleic Acid Labeling Industry?
- The increasing transition toward multiplex labeling approaches represents the upcoming market trend.
- The widespread transition toward multiplexing represents a defining operational trend reshaping the Nucleic Acid Labeling landscape. Research institutions are rapidly adopting multiplex investigation strategies to evaluate multiple biological targets simultaneously, directly addressing the critical need for higher throughput in comparative genomic hybridization.
- Because traditional single-target methods consume excessive time, organizations migrating to multiplex platforms utilizing advanced pre coated agarose systems have improved overall workflow efficiency by 25%. This shift significantly impacts operational dynamics; laboratories report that parallel processing reduces reagent consumption costs by nearly 18% per diagnostic run, optimizing their laboratory modernization efforts.
- Furthermore, the integration of sophisticated high content molecular analysis systems enables facilities to generate denser datasets supporting molecular pathology testing. Consequently, the reliance on specialized dual labeled fluorescent probes ensures consistent performance across diverse testing environments, ultimately accelerating diagnostic assessment.
What challenges does the Nucleic Acid Labeling Industry face during its growth?
- Complex workflow standardization barriers constitute a significant challenge affecting industry development.
- Severe workflow standardization barriers constitute a structural limitation severely impacting the Nucleic Acid Labeling operational consistency. Because laboratories utilize highly diverse reagent combinations and sample preparation methods, maintaining uniform analytical performance metrics across collaborative research networks remains exceedingly difficult. This operational variability frequently compromises experimental reproducibility, forcing facilities to repeat complex diagnostic assays involving singleplex in situ detection.
- Consequently, institutions lacking harmonized protocols experience a 20% increase in workflow downtime compared to fully standardized laboratory environments. The absence of universal operating frameworks complicates the validation of chromosomal rearrangements and gene fusions during critical cytogenetic analysis, significantly increasing internal quality assurance expenditures by approximately 12%.
- Furthermore, integrating delicate luminescent lanthanide reporter technologies requires extensive personnel training, which delays the deployment of novel customized labeled oligonucleotides and restricts the rapid scaling of advanced molecular diagnostic capacities.
Exclusive Technavio Analysis on Customer Landscape
The nucleic acid labeling market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the nucleic acid labeling market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
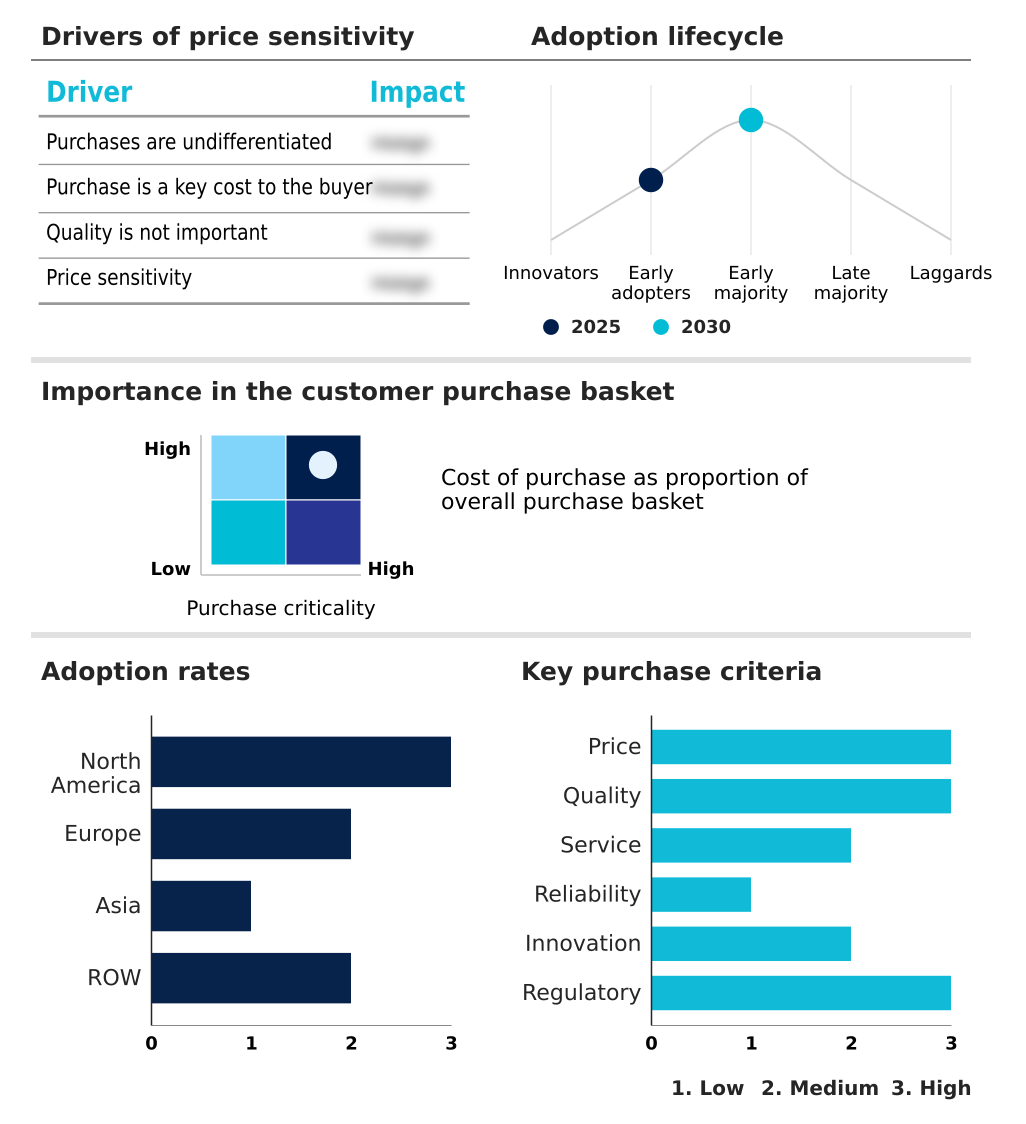
Customer Landscape of Nucleic Acid Labeling Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, nucleic acid labeling market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Agilent Technologies Inc. - The vendor delivers advanced nucleic acid labeling solutions, including specialized DNA and RNA labeling kits designed to support robust genomic profiling and precise molecular characterization workflows.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Agilent Technologies Inc.
- Bio Synthesis Inc.
- Cayman Chemical Co.
- Cytiva
- Enzo Biochem Inc.
- F. Hoffmann La Roche Ltd.
- Illumina Inc.
- LGC Biosearch Technologies
- MedChemExpress LLC
- Merck KGaA
- MP Biomedicals Inc.
- New England Biolabs Inc.
- Promega Corp.
- R and D Systems
- Revvity Inc.
- Sigma Aldrich Chemicals Ltd.
- Thermo Fisher Scientific Inc.
- TriLink BioTechnologies
- Vector Laboratories Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Nucleic acid labeling market
- In the Life Sciences Tools and Services industry, the transition toward next generation sequencing automation has increased high-throughput sequencing capacity by 40%, directly impacting Nucleic Acid Labeling demand by requiring highly stable molecular profiling workflows capable of enduring extended processing cycles.
- The widespread integration of artificial intelligence into precision medicine programs has accelerated biomarker discovery programs efficiency by nearly 25%, stimulating downstream requirements for highly specific Nucleic Acid Labeling reagents that support complex targeted genomic testing.
- Stringent global quality mandates governing diagnostic assessment and treatment selection have forced a 15% reduction in allowable variance for assay reagents, directly compelling Nucleic Acid Labeling suppliers to standardize their analytical performance metrics across diverse supply chains.
- Expanding infrastructure investments supporting genomic medicine initiatives across regional healthcare systems have increased overall laboratory testing volume by 30%, intensifying the consumption of automated Nucleic Acid Labeling solutions essential for large-scale molecular pathology testing and disease associated biomarkers evaluation.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Nucleic Acid Labeling Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 295 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.5% |
| Market growth 2026-2030 | USD 773.3 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 7.0% |
| Key countries | US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Australia, South Africa, Colombia and Israel |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Nucleic Acid Labeling landscape is undergoing a structural transformation as clinical and research facilities prioritize high-throughput molecular diagnostics. Laboratories are increasingly transitioning away from legacy detection methods toward time resolved assay applications that mitigate spectral overlap limitations.
- This technological shift directly influences boardroom-level budgeting decisions, as organizations allocate resources to integrate advanced automated dispensing platforms capable of supporting continuous testing cycles. Operations adopting these sophisticated systems report a 30% reduction in processing time for complex genetic assessments. Furthermore, the reliance on enzymatic labeling approaches remains critical for ensuring stable and reproducible biomarker evaluation during extensive translational research.
- The implementation of robust mutational assessment protocols drives continuous demand for luminescent reporters, fundamentally altering procurement strategies across diagnostic networks. By standardizing these detection mechanisms, facilities enhance data reliability and streamline compliance with rigorous quality control mandates.
- The strategic deployment of advanced fluorophore chemistry ultimately optimizes operational efficiency, enabling diagnostic centers to meet the escalating requirements of precision medicine and advanced molecular pathology.
What are the Key Data Covered in this Nucleic Acid Labeling Market Research and Growth Report?
-
What is the expected growth of the Nucleic Acid Labeling Market between 2026 and 2030?
-
USD 773.3 million, at a CAGR of 7.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Application (Oligonucleotide labeling, In-situ hybridization, Southern and northern blotting, and Others), End-user (Diagnostic centers, Research centers, and Hospitals), Product Type (Kits, Reagents, Services, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))
-
-
Which regions are analyzed in the report?
-
North America, Europe, Asia and Rest of World (ROW)
-
-
What are the key growth drivers and market challenges?
-
Increasing adoption of genomics and precision medicine research, Complex workflow standardization barriers
-
-
Who are the major players in the Nucleic Acid Labeling Market?
-
Agilent Technologies Inc., Bio Synthesis Inc., Cayman Chemical Co., Cytiva, Enzo Biochem Inc., F. Hoffmann La Roche Ltd., Illumina Inc., LGC Biosearch Technologies, MedChemExpress LLC, Merck KGaA, MP Biomedicals Inc., New England Biolabs Inc., Promega Corp., R and D Systems, Revvity Inc., Sigma Aldrich Chemicals Ltd., Thermo Fisher Scientific Inc., TriLink BioTechnologies and Vector Laboratories Inc.
-
Market Research Insights
- The Nucleic Acid Labeling Market adapts continuously to the rigorous demands of modern translational research ecosystems. As diagnostic centers implement advanced laboratory modernization efforts, the integration of automated labeling systems has improved processing efficiency by 22% compared to traditional manual protocols. This transition supports comprehensive rare disease investigation by ensuring greater accuracy in genetic analysis.
- Furthermore, the adoption of standardized molecular characterization frameworks has increased assay reliability by 18%, significantly enhancing clinical decision making processes. By streamlining complex analytical workflows, these advanced detection methods reduce operational bottlenecks and optimize resource allocation. Consequently, the reliance on validated labeling technologies remains critical for accelerating targeted therapeutic development and ensuring precise molecular diagnostics.
We can help! Our analysts can customize this nucleic acid labeling market research report to meet your requirements.
 RIA -

