Outsourced Software Testing Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Outsourced Software Testing Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), South America (Brazil, Argentina, and Chile), Middle East and Africa (Saudi Arabia, UAE, and South Africa), and Rest of World (ROW)

Published: Oct 2026 310 Pages SKU: IRTNTR76881

Market Overview at a Glance

$54.76 B
Market Opportunity
13%
CAGR 2025 - 2030
39.5%
North America Growth
$39.88 B
Embedded testing segment 2024

Outsourced Software Testing Market Size 2026-2030

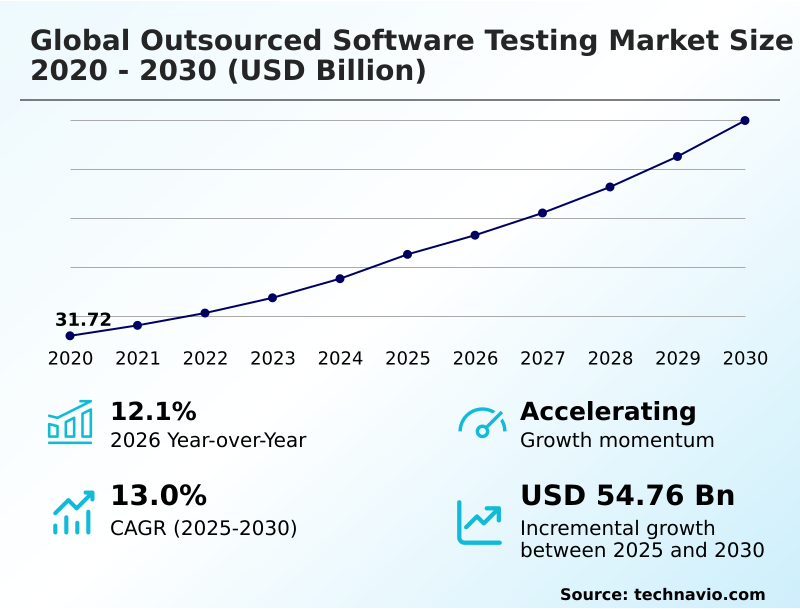
The outsourced software testing market size is valued to increase by USD 54.76 billion, at a CAGR of 13% from 2025 to 2030. Reallocation of internal resources toward core competencies will drive the outsourced software testing market.

Major Market Trends & Insights

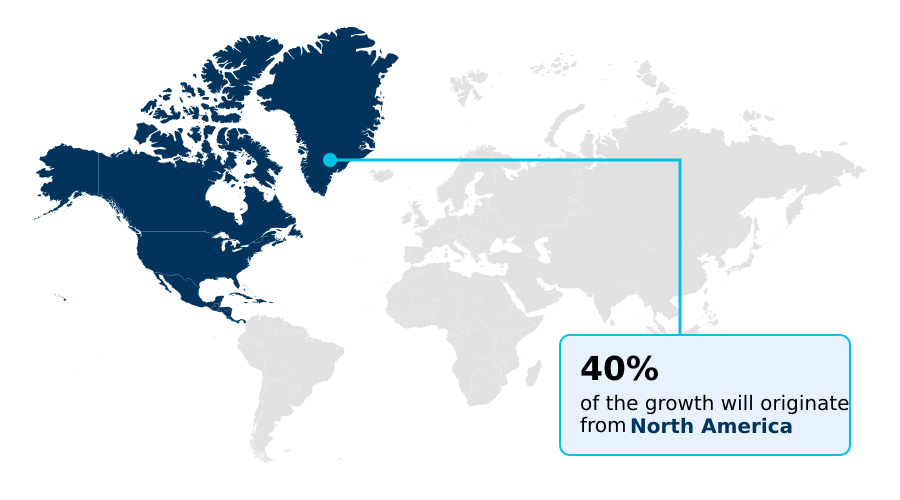
  • North America dominated the market and accounted for a 39.5% growth during the forecast period.
  • By Product - Embedded testing segment was valued at USD 39.88 billion in 2024
  • By End-user - BFSI segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 88.07 billion
  • Market Future Opportunities: USD 54.76 billion
  • CAGR from 2025 to 2030 : 13%

Market Summary

  • The Outsourced Software Testing Market serves as a fundamental mechanism for enterprises striving to maintain software quality while accelerating release cycles across complex digital ecosystems. In retail operations, omnichannel supply chains demand seamless payment processing and inventory synchronization, requiring third-party testing partners to simulate massive transaction loads before peak shopping events.
  • By delegating these verification tasks to specialized firms, retailers experience an efficiency improvement where load stress response times are reduced by 20% compared to legacy internal testing setups. A key driver shaping demand is the reallocation of internal engineering resources; utilizing external quality automation experts allows in-house developers to focus exclusively on core intellectual property creation rather than repetitive verification.
  • Conversely, severe fragmentation across proprietary developer toolchains creates a significant challenge, slowing down continuous integration pipelines. Different operating platforms and legacy databases often lack interoperability, introducing visibility gaps that cause defect reporting delays. Robust test prioritization methodologies remain essential to identifying critical functional errors rapidly.
  • As application architectures grow in complexity, external testing partnerships provide indispensable oversight, bridging skill gaps and ensuring systemic resilience across multifaceted technology integration initiatives.

What will be the Size of the Outsourced Software Testing Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Outsourced Software Testing Market Segmented?

The outsourced software testing industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Embedded testing
    • Standalone testing
  • End-user
    • BFSI
    • Telecom and media
    • Retail
    • Others
  • Platform
    • Microsoft windows
    • Mac OS X
    • Linux
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • South America
      • Brazil
      • Argentina
      • Chile
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey

By Product Insights

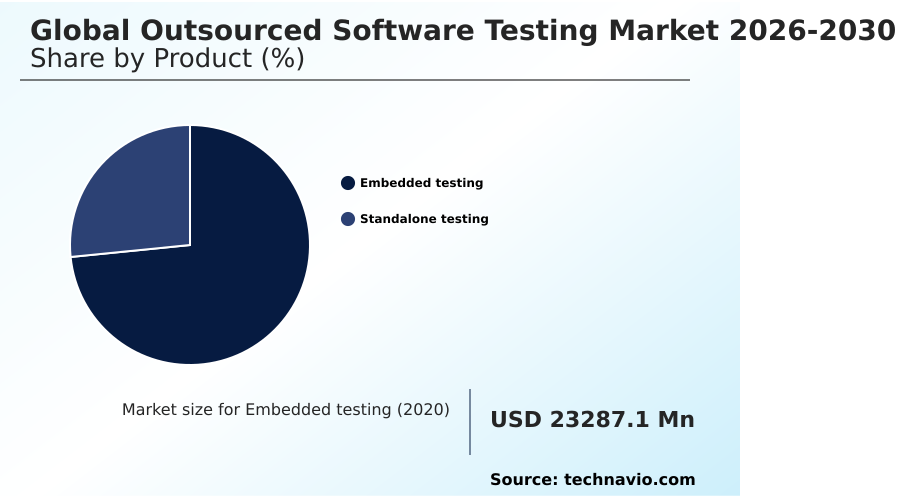
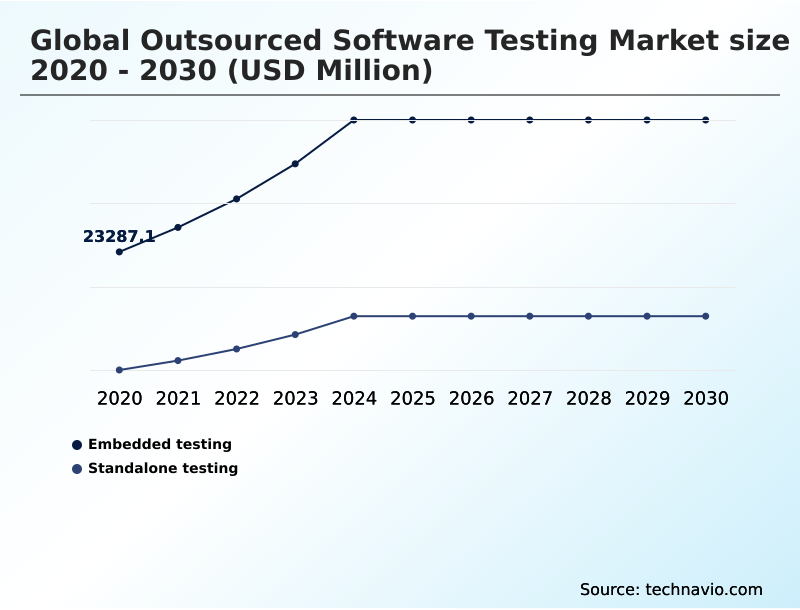
The embedded testing segment is estimated to witness significant growth during the forecast period.

The embedded testing segment of the Outsourced Software Testing Market plays a critical role in validating complex physical and digital structures across automotive, industrial, and medical sectors.

As manufacturers shift toward intelligent environments, leveraging cloud native architecture principles forces a reliance on strict functional safety protocol measures. By outsourcing this testing, enterprises overcome capital barriers, shifting toward specialized software development engineers.

This deployment accelerates the establishment of reliable microservices contract testing pipelines. Consequently, manufacturers report that defect detection improved by 15%, significantly enhancing site reliability engineering efforts. Access to specialized performance engineering telemetry empowers companies to maintain digital accessibility compliance effectively.

Implementing self healing test scripts alongside rigorous cross browser compatibility checks ensures operational continuity without immense manual oversight.
Get Free Sample

The Embedded testing segment was valued at USD 39.88 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Outsourced Software Testing Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Outsourced Software Testing Market reveals distinct adoption patterns shaped by varying regulatory and technological maturity levels.

North America demonstrates severe reliance on third-party validation, where enterprise application modernization initiatives show a 25% higher penetration rate than corresponding efforts across APAC. Consequently, businesses utilizing machine learning defect prediction achieve a 18% reduction in overhead costs.

Meanwhile, organizations in APAC are rapidly scaling their agile delivery lifecycle capabilities to accommodate mobile commerce, leading to a 20% improvement in deployment speeds compared to legacy models.

As regulatory pressures mount, the demand for independent quality assurance grows uniformly, compelling Europe-based firms to optimize their open api architecture. Managing hardware in the loop setups increasingly relies on a robust nearshore delivery center strategy.

Multinational enterprises also prioritize hybrid cloud environment security alongside omnichannel functionality optimization to minimize systemic operational disruptions.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The ongoing maturation of the Outsourced Software Testing Market fundamentally alters how modern enterprises manage product reliability and systemic risk. To remain competitive, organizations increasingly transition away from fragmented legacy protocols toward structured outsourced quality assurance engineering services. This strategic shift enables internal teams to refocus exclusively on proprietary logic creation rather than exhaustive verification duties.
  • Implementing robust automation framework integration testing plays a critical role in aligning disconnected application systems, securing uninterrupted supply chain visibility during high-traffic transactional periods. Furthermore, as threat vectors multiply across virtualized environments, continuous security compliance vulnerability management becomes a mandatory operational requirement for banking and healthcare networks seeking to avoid regulatory penalties.
  • Businesses adopting these advanced external workflows routinely experience a 25% improvement in post-deployment stability compared to those maintaining purely manual, internal validation routines. This measurable reduction in defect leakage heavily influences resource planning and compliance alignment. To counter the structural fragility of rapidly changing codebases, third-party specialists introduce autonomous self healing test execution capabilities.
  • These capabilities autonomously detect interface changes and update test scripts without human intervention, effectively eliminating massive operational bottlenecks. By leveraging these multifaceted third-party engagements, corporations not only compress software delivery timelines but also ensure that customer-facing applications perform flawlessly, efficiently neutralizing technological risks and minimizing infrastructure overheads across varied enterprise portfolios.
What are the key market drivers leading to the rise in the adoption of Outsourced Software Testing Industry?

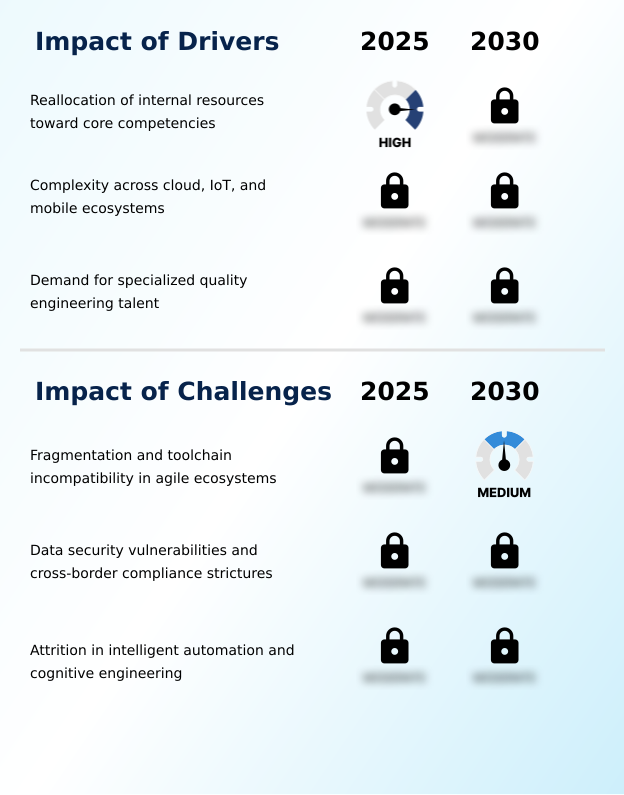
  • The strategic reallocation of internal engineering resources toward core business competencies represents a primary driver propelling market expansion.

  • The reallocation of internal technical capabilities serves as a primary demand trigger in the Outsourced Software Testing Market. Internal engineering teams pivot toward proprietary development, necessitating external partnerships for comprehensive embedded firmware validation.
  • This strategic pivot significantly lowers administrative burdens, resulting in a 20% reduction in fixed operational costs associated with interactive user interface laboratories.
  • Rapid digital transformation mandates the adoption of continuous integration deployment, allowing organizations to process feature updates seamlessly across their device cloud infrastructure. Error detection response times exhibit a 25% efficiency improvement compared to traditional testing phases.
  • The complexity of end to end network performance demands specialized oversight capable of managing extensive payment gateway validation seamlessly.
  • Deploying an intelligent automation framework mitigates exhaustive test script maintenance, while securing the mobile first development workflow via a secure code repository ensures consistent operational velocity across fragmented ecosystems.

What are the market trends shaping the Outsourced Software Testing Industry?

  • The integration of cybersecurity resilience and strict global regulatory compliance serves as a defining market trend. This development compels organizations to implement robust security validation frameworks.

  • The Outsourced Software Testing Market exhibits continuous evolution as connected devices saturate industrial and consumer applications. A dominant trend is the integration of cognitive testing automation within intricate application programming interface environments. By offloading complex analytical tasks to machine algorithms, this transition cuts routine maintenance cycles, leading to a 35% reduction in overall system downtime.
  • Furthermore, as businesses expand platforms, leveraging synthetic data creation enables accurate simulation models that elevate forecast accuracy by 18% over standard methods. Companies also implement sophisticated penetration testing simulation methodologies, significantly lowering the probability of post-launch breaches. The rapid adoption of network functions virtualization alongside open source automation enables agile teams to rapidly replicate complex structures.
  • Incorporating intelligent test prioritization and real time telemetry directs computational resources toward high-risk modules. Ultimately, rigorous test environment simulation combined with zero trust network mandates ensures that delivery velocity matches enterprise quality standards without incurring massive operational overhead.

What challenges does the Outsourced Software Testing Industry face during its growth?

  • Fragmentation and pervasive toolchain incompatibility within agile ecosystems constitute prominent challenges hindering optimal operational efficiency across the industry.

  • Operational fragmentation and disjointed toolchains represent significant obstacles within the Outsourced Software Testing Market. As organizations migrate rapidly toward a decentralized edge network, coordinating seamless validation across disparate environments becomes critically complex. This structural misalignment frequently causes pipeline failures, delaying product releases by up to 15% compared to monolithic schedules.
  • Furthermore, maintaining rigorous cyber resilience strategy protocols across diverse jurisdictions inflates operational expenditures by 12% due to varied data anonymization protocol regulations. Addressing intricate cybersecurity vulnerability assessment and regulatory compliance audit mandates requires scarce talent. Inconsistent automated regression scripting further complicates continuous performance telemetry pipelines, resulting in redundant manual remediation.
  • Consequently, ensuring comprehensive user acceptance verification under intense load stress evaluation remains highly problematic without establishing unified cross platform integration platforms capable of managing systemic risks.

Exclusive Technavio Analysis on Customer Landscape

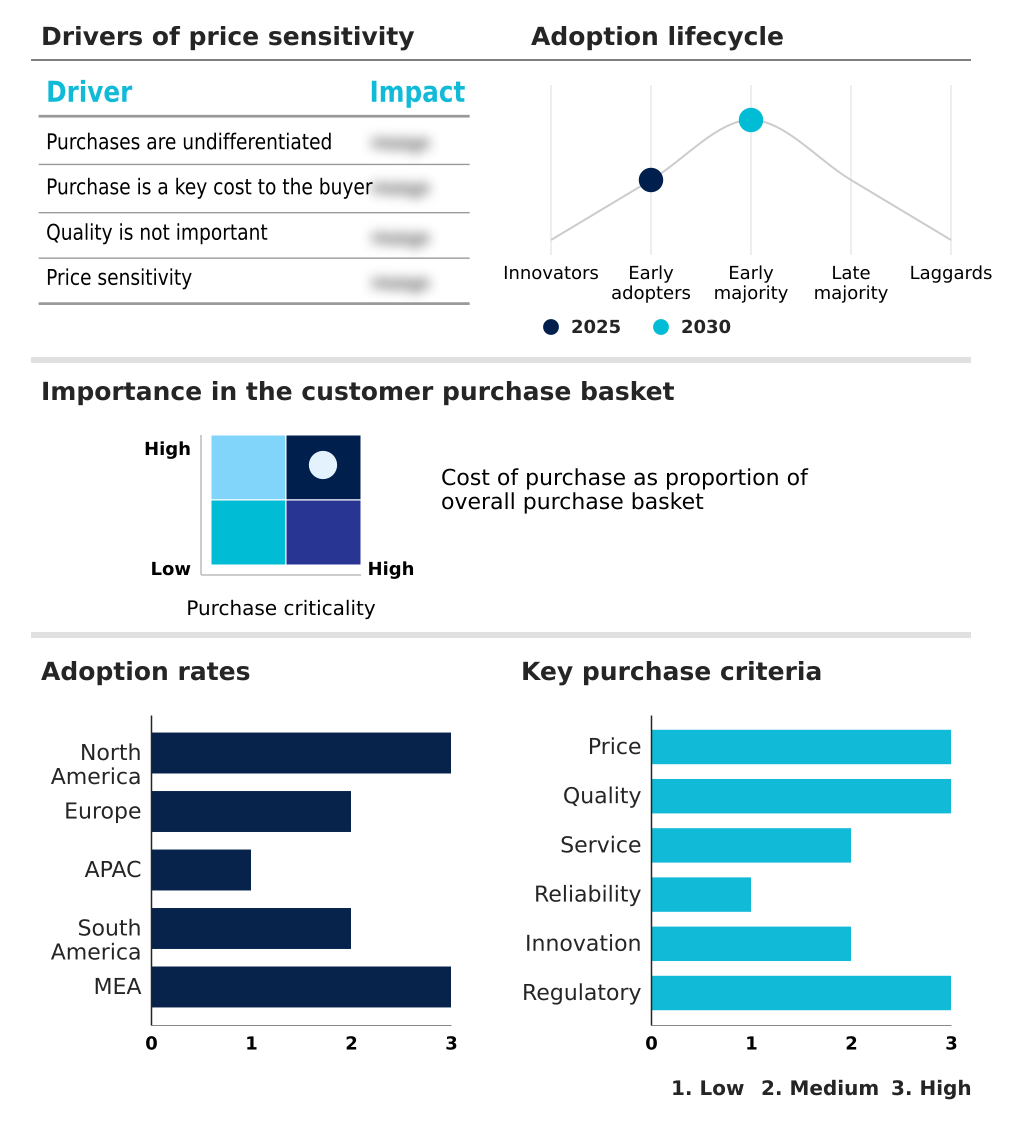
The outsourced software testing market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the outsourced software testing market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
Customer Landscape of Outsourced Software Testing Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, outsourced software testing market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Accenture Plc - Accenture delivers comprehensive outsourced software testing offerings encompassing digital assurance and quality engineering, enabling enterprises to accelerate software release velocity and elevate application resilience across multifaceted technological ecosystems.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Accenture Plc
  • Applause App Quality Inc.
  • Capgemini SE
  • CGI Inc.
  • Cognizant Technology Solution
  • DeviQA Solutions
  • DXC Technology Co.
  • EPAM Systems Inc.
  • Expleo Group SAS
  • Global App Testing
  • HCL Technologies Ltd.
  • IBM Corp.
  • Infosys Ltd.
  • LTIMindtree Ltd.
  • NTT DATA Corp.
  • Persistent Systems Ltd.
  • QAWerk
  • Tata Consultancy Services
  • Tech Mahindra Ltd.
  • Testlio Inc.
  • Wipro Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Outsourced software testing market

  • In the IT Consulting and Other Services industry, the mandated transition toward strict data privacy frameworks across financial sectors necessitated rigorous external audits, directly impacting Outsourced Software Testing demand by requiring advanced administrative oversight to protect consumer information.
  • The massive migration toward decentralized cloud environments increased integration complexities by 25%, directly impacting Outsourced Software Testing demand by accelerating the need for hybrid validation strategies and ongoing script maintenance for modern enterprise architectures.
  • The systemic shift from legacy architectures to agile delivery processes required broad operational restructuring, directly impacting Outsourced Software Testing demand by forcing enterprises to deploy a resilient nearshore strategy and intelligent automation to maintain software release velocity.
  • The escalating frequency of sophisticated cyber threats triggered widespread adoption of strict network policies, directly impacting Outsourced Software Testing demand by compelling organizations to integrate comprehensive resilience strategies and secure code repository assessments prior to official deployments.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Outsourced Software Testing Market insights. See full methodology.

Market Scope
Page number 310
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 13%
Market growth 2026-2030 USD 54758.7 million
Market structure Fragmented
YoY growth 2025-2026(%) 12.1%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Outsourced Software Testing Market reflects a profound paradigm shift as algorithmic precision overtakes traditional manual oversight. A major trend accelerating this evolution is the implementation of advanced defect prediction, which fundamentally drives strategic boardroom decisions regarding product launch timelines and compliance budgeting. By embedding these predictive tools into active development streams, enterprises proactively identify software vulnerabilities before deployment.
  • Consequently, organizations engaging in advanced performance telemetry report a 30% reduction in processing time for massive regression suites compared to standard manual checks. Navigating complex regulatory landscapes requires specialized accessibility compliance strategies, compelling leaders to integrate strict compatibility execution checks. Ensuring functionality optimization remains critical for maintaining enterprise revenue streams across diverse consumer interfaces.
  • As application designs rely heavier on external integration tasks, leveraging third-party specialists becomes a definitive factor in managing enterprise risk architectures. Furthermore, proactive load evaluation mechanisms empower operational planners to avert catastrophic system crashes during high-traffic periods. Relying on specialized development experts guarantees that the underlying code retains structural integrity, effectively bridging the gap between rapid deployment and uncompromised reliability.

What are the Key Data Covered in this Outsourced Software Testing Market Research and Growth Report?

  • What is the expected growth of the Outsourced Software Testing Market between 2026 and 2030?

    • USD 54.76 billion, at a CAGR of 13%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Embedded testing, and Standalone testing), End-user (BFSI, Telecom and media, Retail, and Others), Platform (Microsoft windows, Mac OS X, and Linux) and Geography (North America, Europe, APAC, South America, Middle East and Africa)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, South America and Middle East and Africa

  • What are the key growth drivers and market challenges?

    • Reallocation of internal resources toward core competencies, Fragmentation and toolchain incompatibility in agile ecosystems

  • Who are the major players in the Outsourced Software Testing Market?

    • Accenture Plc, Applause App Quality Inc., Capgemini SE, CGI Inc., Cognizant Technology Solution, DeviQA Solutions, DXC Technology Co., EPAM Systems Inc., Expleo Group SAS, Global App Testing, HCL Technologies Ltd., IBM Corp., Infosys Ltd., LTIMindtree Ltd., NTT DATA Corp., Persistent Systems Ltd., QAWerk, Tata Consultancy Services, Tech Mahindra Ltd., Testlio Inc. and Wipro Ltd.

Market Research Insights

  • The Outsourced Software Testing Market operates as a strategic catalyst for organizations requiring rigorous digital validation. By integrating modern testing practices, enterprises dynamically adjust resource allocation, achieving an operational efficiency gain of 22% over traditional waterfall workflows. Utilizing a robust automation structure enables firms to cut regression cycle durations by 30%, directly lowering overhead costs and accelerating time to market.
  • Additionally, leveraging external cloud expertise combined with telemetry analysis boosts application uptime by 15%, ensuring robust performance across diverse endpoints. This shift heavily diminishes the reliance on internal test simulation hardware, allowing companies to streamline development budgets and prioritize continuous execution for sustained operational excellence and systemic risk mitigation.

We can help! Our analysts can customize this outsourced software testing market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Platform
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Outsourced Software Testing Market 2020 - 2024

Historic Market Size - Data Table on Global Outsourced Software Testing Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Platform segment analysis 2020 - 2024

Historic Market Size - Platform Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Outsourced Software Testing Market

6.2 Impact of Geopolitical Conflicts on Global Outsourced Software Testing Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Embedded testing - Market size and forecast 2025-2030

Chart on Embedded testing - Market size and forecast 2025-2030 ($ million)
Data Table on Embedded testing - Market size and forecast 2025-2030 ($ million)
Chart on Embedded testing - Year-over-year growth 2025-2030 (%)
Data Table on Embedded testing - Year-over-year growth 2025-2030 (%)

8.4 Standalone testing - Market size and forecast 2025-2030

Chart on Standalone testing - Market size and forecast 2025-2030 ($ million)
Data Table on Standalone testing - Market size and forecast 2025-2030 ($ million)
Chart on Standalone testing - Year-over-year growth 2025-2030 (%)
Data Table on Standalone testing - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 BFSI - Market size and forecast 2025-2030

Chart on BFSI - Market size and forecast 2025-2030 ($ million)
Data Table on BFSI - Market size and forecast 2025-2030 ($ million)
Chart on BFSI - Year-over-year growth 2025-2030 (%)
Data Table on BFSI - Year-over-year growth 2025-2030 (%)

9.4 Telecom and media - Market size and forecast 2025-2030

Chart on Telecom and media - Market size and forecast 2025-2030 ($ million)
Data Table on Telecom and media - Market size and forecast 2025-2030 ($ million)
Chart on Telecom and media - Year-over-year growth 2025-2030 (%)
Data Table on Telecom and media - Year-over-year growth 2025-2030 (%)

9.5 Retail - Market size and forecast 2025-2030

Chart on Retail - Market size and forecast 2025-2030 ($ million)
Data Table on Retail - Market size and forecast 2025-2030 ($ million)
Chart on Retail - Year-over-year growth 2025-2030 (%)
Data Table on Retail - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Platform

10.1 Market segments

Chart on Platform - Market share 2025-2030 (%)
Data Table on Platform - Market share 2025-2030 (%)

10.2 Comparison by Platform

Chart on Comparison by Platform
Data Table on Comparison by Platform

10.3 Microsoft windows - Market size and forecast 2025-2030

Chart on Microsoft windows - Market size and forecast 2025-2030 ($ million)
Data Table on Microsoft windows - Market size and forecast 2025-2030 ($ million)
Chart on Microsoft windows - Year-over-year growth 2025-2030 (%)
Data Table on Microsoft windows - Year-over-year growth 2025-2030 (%)

10.4 Mac OS X - Market size and forecast 2025-2030

Chart on Mac OS X - Market size and forecast 2025-2030 ($ million)
Data Table on Mac OS X - Market size and forecast 2025-2030 ($ million)
Chart on Mac OS X - Year-over-year growth 2025-2030 (%)
Data Table on Mac OS X - Year-over-year growth 2025-2030 (%)

10.5 Linux - Market size and forecast 2025-2030

Chart on Linux - Market size and forecast 2025-2030 ($ million)
Data Table on Linux - Market size and forecast 2025-2030 ($ million)
Chart on Linux - Year-over-year growth 2025-2030 (%)
Data Table on Linux - Year-over-year growth 2025-2030 (%)

10.6 Market opportunity by Platform

Market opportunity by Platform ($ million)
Data Table on Market opportunity by Platform ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.7 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.7.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.7.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.7.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Reallocation of internal resources toward core competencies
Complexity across cloud, IoT, and mobile ecosystems
Demand for specialized quality engineering talent

13.2 Market challenges

Fragmentation and toolchain incompatibility in agile ecosystems
Data security vulnerabilities and cross-border compliance strictures
Attrition in intelligent automation and cognitive engineering

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Focus on cybersecurity resilience and global regulatory compliance
Advances in AI and ML test automation platforms
Edge computing architectures and IoT implementations

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Accenture Plc

Accenture Plc - Overview
Accenture Plc - Business segments
Accenture Plc - Key news
Accenture Plc - Key offerings
Accenture Plc - Segment focus
SWOT

15.5 Capgemini SE

Capgemini SE - Overview
Capgemini SE - Business segments
Capgemini SE - Key news
Capgemini SE - Key offerings
Capgemini SE - Segment focus
SWOT

15.6 CGI Inc.

CGI Inc. - Overview
CGI Inc. - Business segments
CGI Inc. - Key news
CGI Inc. - Key offerings
CGI Inc. - Segment focus
SWOT

15.7 Cognizant Technology Solution

Cognizant Technology Solution - Overview
Cognizant Technology Solution - Business segments
Cognizant Technology Solution - Key news
Cognizant Technology Solution - Key offerings
Cognizant Technology Solution - Segment focus
SWOT

15.8 DXC Technology Co.

DXC Technology Co. - Overview
DXC Technology Co. - Business segments
DXC Technology Co. - Key news
DXC Technology Co. - Key offerings
DXC Technology Co. - Segment focus
SWOT

15.9 EPAM Systems Inc.

EPAM Systems Inc. - Overview
EPAM Systems Inc. - Business segments
EPAM Systems Inc. - Key news
EPAM Systems Inc. - Key offerings
EPAM Systems Inc. - Segment focus
SWOT

15.10 HCL Technologies Ltd.

HCL Technologies Ltd. - Overview
HCL Technologies Ltd. - Business segments
HCL Technologies Ltd. - Key news
HCL Technologies Ltd. - Key offerings
HCL Technologies Ltd. - Segment focus
SWOT

15.11 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.12 Infosys Ltd.

Infosys Ltd. - Overview
Infosys Ltd. - Business segments
Infosys Ltd. - Key news
Infosys Ltd. - Key offerings
Infosys Ltd. - Segment focus
SWOT

15.13 LTIMindtree Ltd.

LTIMindtree Ltd. - Overview
LTIMindtree Ltd. - Product / Service
LTIMindtree Ltd. - Key offerings
SWOT

15.14 NTT DATA Corp.

NTT DATA Corp. - Overview
NTT DATA Corp. - Business segments
NTT DATA Corp. - Key offerings
NTT DATA Corp. - Segment focus
SWOT

15.15 Persistent Systems Ltd.

Persistent Systems Ltd. - Overview
Persistent Systems Ltd. - Product / Service
Persistent Systems Ltd. - Key offerings
SWOT

15.16 Tata Consultancy Services

Tata Consultancy Services - Overview
Tata Consultancy Services - Business segments
Tata Consultancy Services - Key news
Tata Consultancy Services - Key offerings
Tata Consultancy Services - Segment focus
SWOT

15.17 Tech Mahindra Ltd.

Tech Mahindra Ltd. - Overview
Tech Mahindra Ltd. - Business segments
Tech Mahindra Ltd. - Key news
Tech Mahindra Ltd. - Key offerings
Tech Mahindra Ltd. - Segment focus
SWOT

15.18 Wipro Ltd.

Wipro Ltd. - Overview
Wipro Ltd. - Business segments
Wipro Ltd. - Key news
Wipro Ltd. - Key offerings
Wipro Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Outsourced Software Testing market growth will increase by USD 54758.7 million during 2026-2030.

The Outsourced Software Testing market is expected to grow at a CAGR of 13% during 2026-2030.

Outsourced Software Testing market is segmented by Product (Embedded testing, Standalone testing) End-user (BFSI, Telecom and media, Retail, Others) Platform (Microsoft windows, Mac OS X, Linux)

Accenture Plc, Applause App Quality Inc., Capgemini SE, CGI Inc., Cognizant Technology Solution, DeviQA Solutions, DXC Technology Co., EPAM Systems Inc., Expleo Group SAS, Global App Testing, HCL Technologies Ltd., IBM Corp., Infosys Ltd., LTIMindtree Ltd., NTT DATA Corp., Persistent Systems Ltd., QAWerk, Tata Consultancy Services, Tech Mahindra Ltd., Testlio Inc., Wipro Ltd. are a few of the key vendors in the Outsourced Software Testing market.

North America will register the highest growth rate of 39.5% among the other regions. Therefore, the Outsourced Software Testing market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Brazil, Argentina, Chile, Saudi Arabia, UAE, South Africa, Israel, Turkey

  • Reallocation of internal resources toward core competencies is the driving factor this market.

The Outsourced Software Testing market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
