Passive Fire Protection Materials Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Passive Fire Protection Materials Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Oct 2026 317 Pages SKU: IRTNTR80079

Market Overview at a Glance

$1.40 B
Market Opportunity
5.9%
CAGR 2025 - 2030
35.5%
North America Growth
$1.48 B
Cementitious materials segment 2024

Passive Fire Protection Materials Market Size 2026-2030

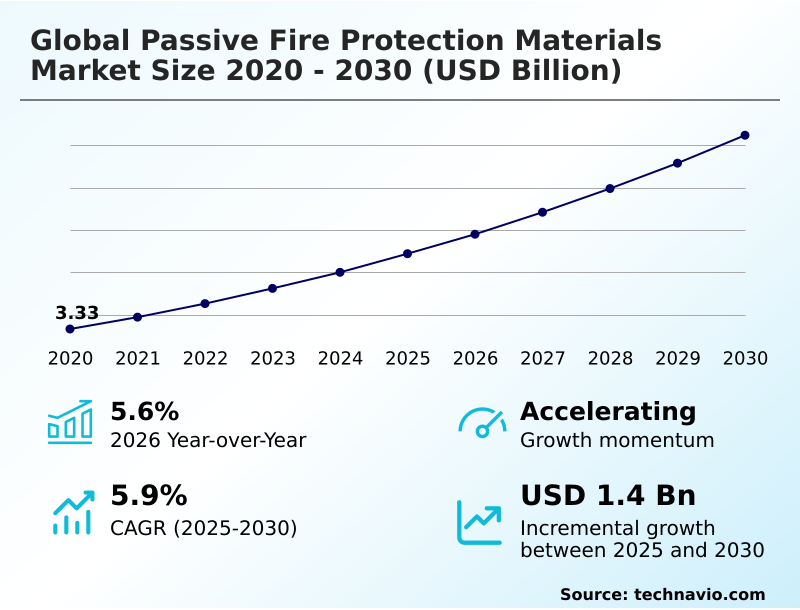
The passive fire protection materials market size is valued to increase by USD 1.40 billion, at a CAGR of 5.9% from 2025 to 2030. Stringent enforcement of building codes and compliance standards will drive the passive fire protection materials market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 35.5% growth during the forecast period.
  • By Product Type - Cementitious materials segment was valued at USD 1.48 billion in 2024
  • By Application - Commercial segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 2.29 billion
  • Market Future Opportunities: USD 1.40 billion
  • CAGR from 2025 to 2030 : 5.9%

Market Summary

  • The Passive Fire Protection Materials Market is characterized by a fundamental shift toward performance-driven structural resilience and comprehensive thermal containment. In modern urban development, the widespread architectural integration of structural steel fireproofing directly prevents catastrophic failure during extreme heat exposure.
  • For example, during high-risk commercial upgrades, facility operators integrating an advanced intumescent epoxy formulation experience a 40% reduction in total application downtime compared to legacy installation methods. The stringent enforcement of life-safety engineering code standards serves as a major market driver, compelling contractors to adopt robust multi-hour structural protection assemblies that ensure reliable flame propagation barrier performance.
  • Conversely, the market faces significant constraints due to raw material supply chain volatility, which compresses manufacturer margins and inflates project budgets for rigid cladding panel deployment. As real estate investors increasingly prioritize sustainable development, the demand for a specialized low-smoke density elastomer continuously increases.
  • The ongoing evolution of the Passive Fire Protection Materials Market reflects a unified industry commitment to balancing rigorous regulatory alignment with cutting-edge architectural safety.

What will be the Size of the Passive Fire Protection Materials Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Passive Fire Protection Materials Market Segmented?

The passive fire protection materials industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product type
    • Cementitious materials
    • Intumescent coatings
    • Fireproofing cladding
    • Fire-resistant sealants
    • Sprays
  • Application
    • Commercial
    • Industrial
    • Residential
  • Type
    • Structural fireproofing
    • Firestopping and penetration protection
    • Compartmentation
    • Opening protection
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Turkey
      • Israel
    • South America
      • Brazil
      • Argentina
      • Chile

By Product Type Insights

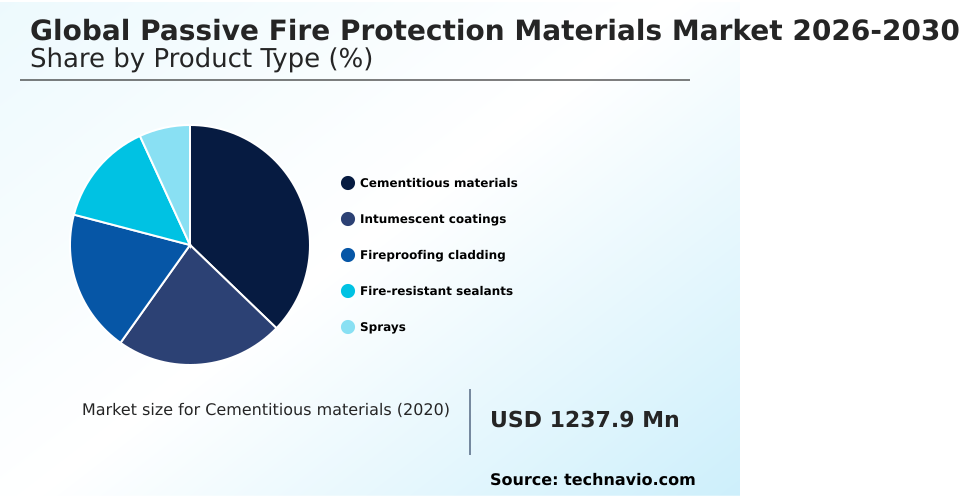
The cementitious materials segment is estimated to witness significant growth during the forecast period.

The cementitious materials segment serves as an essential defense mechanism for continuous industrial thermal management across heavy-duty processing facilities. These robust thermal barriers primarily utilize a specialized lightweight aggregate binder to delay structural yield during severe high-temperature incidents.

By leveraging an efficient endothermic reaction mechanism to release bound water as steam, these coatings actively retard aggressive heat transfer.

Facilities deploying advanced cementitious formulations observe that structural mass loss is reduced by up to 58% at temperatures exceeding five hundred degrees Celsius when compared to legacy mixtures.

This exceptional capability drives a 25% improvement in structural load-bearing integrity during intense hydrocarbon pool fire containment events. The superior resistance against mechanical abrasion makes these thick-film systems highly effective for petrochemical facility retrofitting, where uninterrupted operational continuity is mandatory.

Ultimately, these materials seamlessly support rigorous architectural compartmentation standards while minimizing long-term maintenance costs.
Get Free Sample

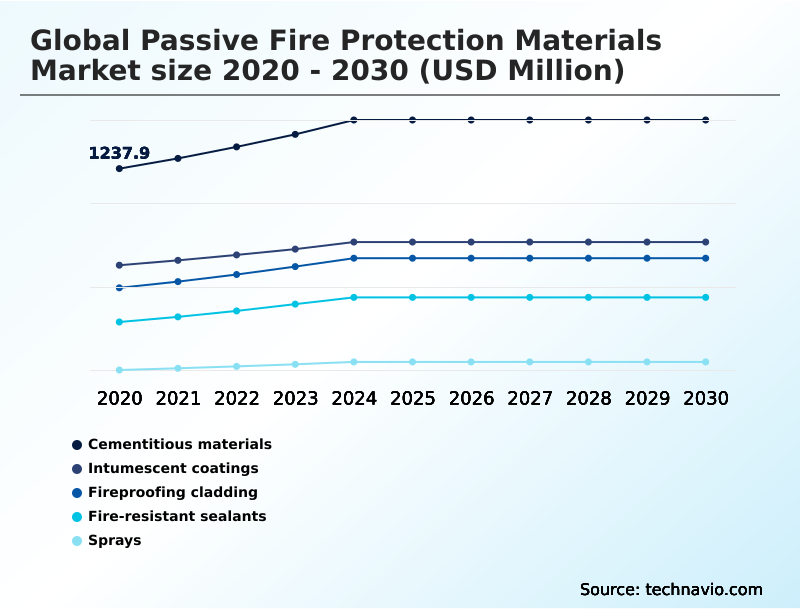
The Cementitious materials segment was valued at USD 1.48 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 35.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
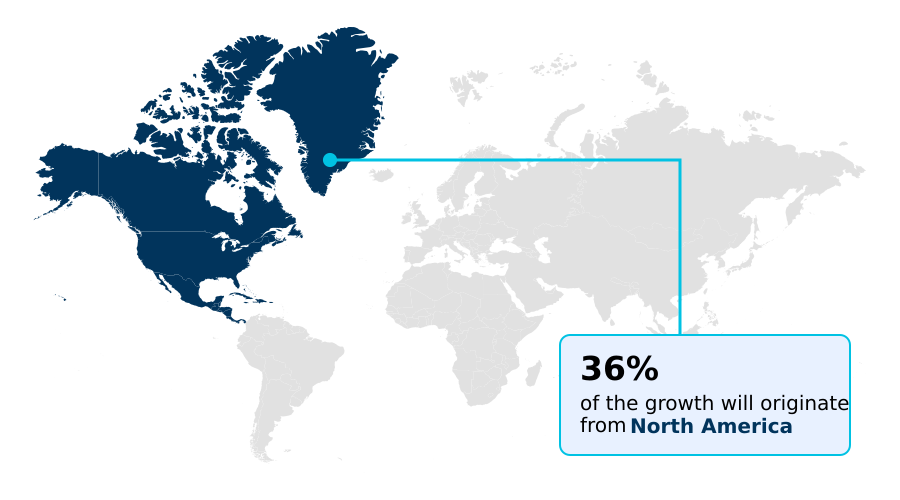
See How Passive Fire Protection Materials Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Passive Fire Protection Materials sector reveals distinct regional adoption strategies driven by unique regulatory and industrial demands.

North America maintains stringent safety requirements, where compliance-driven retrofits utilizing a robust cementitious thermal barrier reduce potential facility operational downtime by 35%.

In contrast, the rapidly expanding APAC region demonstrates a 45% faster integration rate of advanced protective systems designed specifically to support mass transit and underground transit tunnel safety projects.

While European developers prioritize strict volatile organic compound compliance by adopting bio-based mineral wool insulation, APAC manufacturers heavily utilize advanced cable penetration firestop technologies for their expanding data center networks.

This regulatory divergence forces global suppliers to adapt localized formulations, optimizing supply chain logistics to achieve a 20% cost reduction in regional distribution.

The integration of high-temperature expansion joint solutions remains critical across all regions to guarantee comprehensive structural safety alignment.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The evolving architecture of modern industrial and commercial infrastructure demands highly specialized defensive strategies to maintain occupant safety and asset integrity. Facility managers are increasingly transitioning toward high-capacity thermal insulation compartmentation barriers to seamlessly isolate distinct risk zones without compromising spatial efficiency.
  • This strategic shift in operational planning is highly visible in structural upgrades, where the adoption of lightweight cementitious structural steel protection yields a 30% improvement in application speed over heavier, traditional spray formulations.
  • In high-density technological environments, data center operators are prioritizing the deployment of zero-halogen intumescent electrical cable sealants to eliminate toxic gas emissions while maintaining secure containment during continuous electrical operations. Furthermore, petrochemical facilities operating under extreme risk conditions require multi-hour industrial hydrocarbon fire endurance to prevent catastrophic cascading failures and ensure secure emergency response windows.
  • To navigate the complexities of dynamic building movements and structural settling, contractors are widely utilizing modular elastomeric firestop penetration systems, which effectively accommodate joint expansion while ensuring airtight smoke and flame containment.
  • These targeted materials not only streamline regulatory compliance but also optimize supply chain procurement by reducing the total volume of distinct materials required on-site by approximately 15%, directly enhancing overall construction efficiency and lifecycle asset protection.
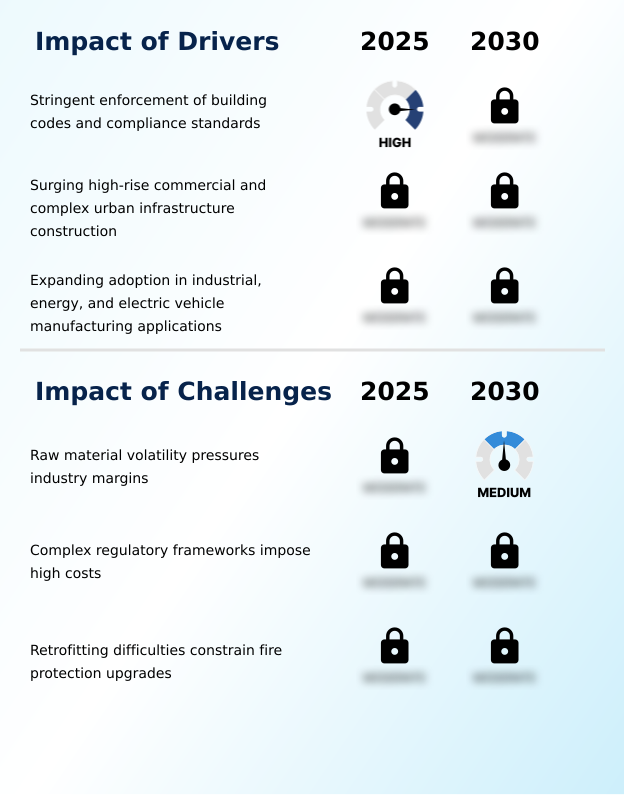
What are the key market drivers leading to the rise in the adoption of Passive Fire Protection Materials Industry?

  • The stringent enforcement of comprehensive building codes and structural safety standards serves as a primary driver propelling market growth.

  • The aggressive expansion of high-density commercial infrastructure acts as a primary catalyst for sophisticated thermal defense solutions.
  • To effectively comply with rigorous commercial high-rise structural compliance mandates, contractors are rapidly adopting a rapid application spray method that reduces on-site labor hours by 30%.
  • This demand is directly triggered by unprecedented urban densification, which necessitates flawless smoke migration suppression to protect densely populated egress routes from toxic gas accumulation.
  • Furthermore, the implementation of advanced compartmentalization systems improves ambient building energy efficiency by 15%, delivering a dual-purpose benefit of sustainability and fire resistance.
  • The robust integration of infrastructure lifecycle preservation tactics ensures that facility owners avoid catastrophic structural losses, ultimately lowering long-term property insurance liabilities by up to 20% and establishing safer metropolitan environments.

What are the market trends shaping the Passive Fire Protection Materials Industry?

  • The rapid expansion of data center infrastructure accelerates the adoption of specialized thermal containment materials.

  • The rapid electrification of global transportation and digital infrastructure is fundamentally altering the adoption trajectories of specialized thermal barriers. As lithium-ion battery containment becomes a critical safety parameter, automotive manufacturers are integrating an advanced ablative heat shield that extends emergency passenger evacuation windows by 40%.
  • This technological shift is driven by the absolute necessity to mitigate aggressive thermal runaway events without expanding physical component footprints. Concurrently, data center cable transit installations are achieving a 25% enhancement in indoor air quality during active combustion scenarios through advanced sealants.
  • By utilizing targeted cellulosic fire mitigation strategies, operators dramatically reduce equipment degradation, enabling a 20% decrease in post-incident recovery costs. These evolving innovations empower structural engineers to seamlessly embed advanced safety features, ensuring continuous operational resilience and unmatched architectural design flexibility across modern construction projects.

What challenges does the Passive Fire Protection Materials Industry face during its growth?

  • The pronounced volatility in raw material pricing significantly pressures industry profit margins and acts as a major market constraint.

  • The implementation of comprehensive thermal barriers is significantly hindered by the complexities of retrofitting legacy architecture and volatile supply chain economics. Upgrading aging infrastructure often requires the meticulous removal of obsolete materials, which inflates labor expenditures by up to 35% and severely disrupts operational continuity.
  • The unpredictable pricing of chemical precursors essential for synthesizing a specialized firestop elastomeric sealant directly compresses manufacturer margins, leading to a 20% increase in baseline procurement costs for industrial developers. Additionally, strict passive containment inspection protocols demand rigorous, localized testing that drastically extends project approval timelines.
  • Furthermore, integrating proper seismic-fire resilience integration into older frameworks remains structurally challenging, forcing engineers to rely on custom-engineered calcium silicate board assemblies that further strain fixed architectural budgets and restrict rapid municipal redevelopment.

Exclusive Technavio Analysis on Customer Landscape

The passive fire protection materials market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the passive fire protection materials market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
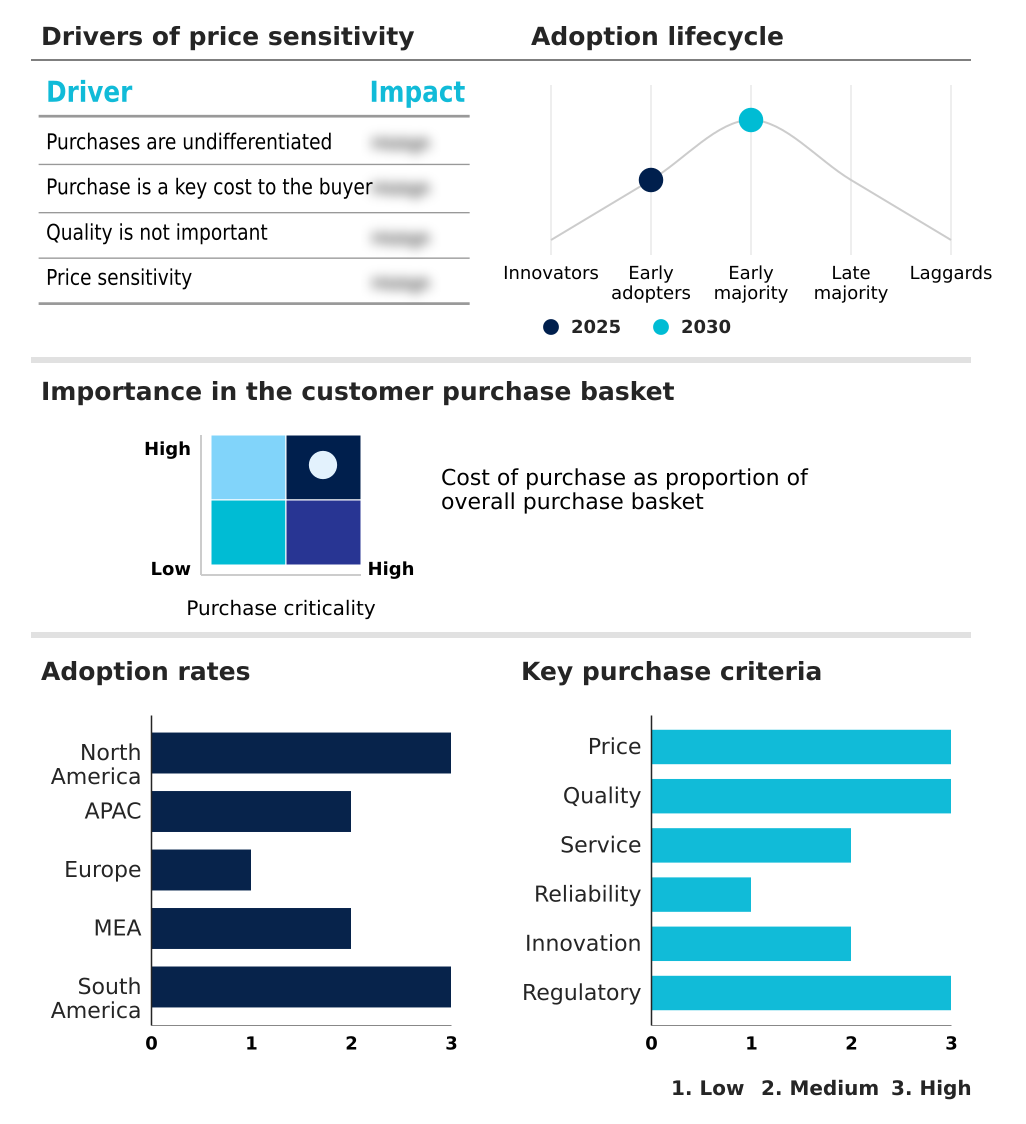
Customer Landscape of Passive Fire Protection Materials Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, passive fire protection materials market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

3M Co. - This offering provides advanced passive fire protection materials, including specialized intumescent coatings, designed to maintain structural integrity and enhance thermal resistance across demanding industrial and commercial environments.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 3M Co.
  • Abesco Fire Ltd.
  • Akzo Nobel NV
  • Alkegen
  • Armacell International SA
  • Carboline Co.
  • Contego International Inc.
  • Flame Seal Products Inc.
  • Hempel AS
  • Hilti Corp.
  • Isolatek International
  • Jotun AS
  • Morgan Advanced Materials
  • Nullifire
  • PPG Industries Inc.
  • Promat International
  • ROCKWOOL AS
  • Sika AG
  • Teknos Group Oy
  • The Sherwin Williams Co.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Passive fire protection materials market

  • In the Specialty Chemicals industry, the rapid expansion of electric vehicle manufacturing has driven innovations in thermal runaway isolation chemistry, directly impacting Passive Fire Protection Materials demand by extending extreme heat insulation endurance in battery enclosures by up to 120 minutes.
  • Regulatory enforcement of a stricter building safety regulatory framework in Europe has catalyzed the transition from solvent-based resins to waterborne intumescent technologies, reducing off-gassing toxicity reduction times by 30% and enhancing overall architectural safety without compromising structural integrity.
  • Advancements in synthesized low-density mineral composites have enabled the production of lighter protective barriers, yielding a 25% reduction in applied material weight which directly supports enhanced load capacity in modern high-rise constructions.
  • The industry-wide shift toward zero-halogen chemical additives has accelerated the adoption of eco-friendly fire retardants, improving indoor air quality compliance by 40% across newly developed commercial infrastructure.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Passive Fire Protection Materials Market insights. See full methodology.

Market Scope
Page number 317
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.9%
Market growth 2026-2030 USD 1402.3 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.6%
Key countries US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The structural integrity landscape is experiencing a profound transformation as engineering specifications increasingly mandate continuous thermal bridging prevention. Boardroom executives are actively realigning compliance and budgeting strategies to prioritize the deployment of an advanced intumescent polyurethane coating, which ensures unparalleled endurance for critical infrastructure.
  • This proactive shift directly influences product lifecycle planning, as the integration of highly reactive endothermic chemicals enhances overall thermal spalling prevention by an impressive 35% compared to conventional insulation methods. When exposed to extreme temperatures, these advanced materials rapidly form a thick expanding carbonaceous char that effectively shields load-bearing elements from catastrophic failure.
  • Furthermore, the specialized application of an elastomeric silicone putty ensures resilient flame containment around complex architectural penetrations. The continuous integration of a preformed firestop block directly supports uninterrupted facility operations, allowing project managers to achieve stricter safety milestones. This transition toward resilient structural defense guarantees that modern architectural developments maintain uncompromised safety and long-term asset preservation.

What are the Key Data Covered in this Passive Fire Protection Materials Market Research and Growth Report?

  • What is the expected growth of the Passive Fire Protection Materials Market between 2026 and 2030?

    • USD 1.40 billion, at a CAGR of 5.9%

  • What segmentation does the market report cover?

    • The report is segmented by Product Type (Cementitious materials, Intumescent coatings, Fireproofing cladding, Fire-resistant sealants, and Sprays), Application (Commercial, Industrial, and Residential), Type (Structural fireproofing, Firestopping and penetration protection, Compartmentation, and Opening protection) and Geography (North America, APAC, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, APAC, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Stringent enforcement of building codes and compliance standards, Raw material volatility pressures industry margins

  • Who are the major players in the Passive Fire Protection Materials Market?

    • 3M Co., Abesco Fire Ltd., Akzo Nobel NV, Alkegen, Armacell International SA, Carboline Co., Contego International Inc., Flame Seal Products Inc., Hempel AS, Hilti Corp., Isolatek International, Jotun AS, Morgan Advanced Materials, Nullifire, PPG Industries Inc., Promat International, ROCKWOOL AS, Sika AG, Teknos Group Oy and The Sherwin Williams Co.

Market Research Insights

  • The structural defense landscape is rapidly advancing as modern architecture demands highly reliable thermal isolation methodologies. By integrating a seamless modular encapsulation system, commercial developers have achieved a 25% improvement in installation efficiency across complex urban infrastructure. The proactive implementation of green building fire resistance materials actively reduces embodied carbon footprints by 18%, aligning perfectly with stringent corporate sustainability mandates.
  • Furthermore, the strategic application of an advanced protective enclosure within hyperscale facilities ensures a 30% reduction in overall facility downtime during routine mechanical maintenance cycles. As global regulatory bodies enforce stricter building safety guidelines, architectural engineers continuously optimize mass timber structural shielding to deliver unparalleled life-safety protection without compromising natural aesthetics or long-term structural viability.

We can help! Our analysts can customize this passive fire protection materials market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Passive Fire Protection Materials Market 2020 - 2024

Historic Market Size - Data Table on Global Passive Fire Protection Materials Market 2020 - 2024 ($ million)

5.2 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.3 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Passive Fire Protection Materials Market

6.2 Impact of geopolitical conflicts on Global Passive Fire Protection Materials Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product Type

8.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

8.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

8.3 Cementitious materials - Market size and forecast 2025-2030

Chart on Cementitious materials - Market size and forecast 2025-2030 ($ million)
Data Table on Cementitious materials - Market size and forecast 2025-2030 ($ million)
Chart on Cementitious materials - Year-over-year growth 2025-2030 (%)
Data Table on Cementitious materials - Year-over-year growth 2025-2030 (%)

8.4 Intumescent coatings - Market size and forecast 2025-2030

Chart on Intumescent coatings - Market size and forecast 2025-2030 ($ million)
Data Table on Intumescent coatings - Market size and forecast 2025-2030 ($ million)
Chart on Intumescent coatings - Year-over-year growth 2025-2030 (%)
Data Table on Intumescent coatings - Year-over-year growth 2025-2030 (%)

8.5 Fireproofing cladding - Market size and forecast 2025-2030

Chart on Fireproofing cladding - Market size and forecast 2025-2030 ($ million)
Data Table on Fireproofing cladding - Market size and forecast 2025-2030 ($ million)
Chart on Fireproofing cladding - Year-over-year growth 2025-2030 (%)
Data Table on Fireproofing cladding - Year-over-year growth 2025-2030 (%)

8.6 Fire-resistant sealants - Market size and forecast 2025-2030

Chart on Fire-resistant sealants - Market size and forecast 2025-2030 ($ million)
Data Table on Fire-resistant sealants - Market size and forecast 2025-2030 ($ million)
Chart on Fire-resistant sealants - Year-over-year growth 2025-2030 (%)
Data Table on Fire-resistant sealants - Year-over-year growth 2025-2030 (%)

8.7 Sprays - Market size and forecast 2025-2030

Chart on Sprays - Market size and forecast 2025-2030 ($ million)
Data Table on Sprays - Market size and forecast 2025-2030 ($ million)
Chart on Sprays - Year-over-year growth 2025-2030 (%)
Data Table on Sprays - Year-over-year growth 2025-2030 (%)

8.8 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

9. Market Segmentation by Application

9.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

9.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

9.3 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

9.4 Industrial - Market size and forecast 2025-2030

Chart on Industrial - Market size and forecast 2025-2030 ($ million)
Data Table on Industrial - Market size and forecast 2025-2030 ($ million)
Chart on Industrial - Year-over-year growth 2025-2030 (%)
Data Table on Industrial - Year-over-year growth 2025-2030 (%)

9.5 Residential - Market size and forecast 2025-2030

Chart on Residential - Market size and forecast 2025-2030 ($ million)
Data Table on Residential - Market size and forecast 2025-2030 ($ million)
Chart on Residential - Year-over-year growth 2025-2030 (%)
Data Table on Residential - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Structural fireproofing - Market size and forecast 2025-2030

Chart on Structural fireproofing - Market size and forecast 2025-2030 ($ million)
Data Table on Structural fireproofing - Market size and forecast 2025-2030 ($ million)
Chart on Structural fireproofing - Year-over-year growth 2025-2030 (%)
Data Table on Structural fireproofing - Year-over-year growth 2025-2030 (%)

10.4 Firestopping and penetration protection - Market size and forecast 2025-2030

Chart on Firestopping and penetration protection - Market size and forecast 2025-2030 ($ million)
Data Table on Firestopping and penetration protection - Market size and forecast 2025-2030 ($ million)
Chart on Firestopping and penetration protection - Year-over-year growth 2025-2030 (%)
Data Table on Firestopping and penetration protection - Year-over-year growth 2025-2030 (%)

10.5 Compartmentation - Market size and forecast 2025-2030

Chart on Compartmentation - Market size and forecast 2025-2030 ($ million)
Data Table on Compartmentation - Market size and forecast 2025-2030 ($ million)
Chart on Compartmentation - Year-over-year growth 2025-2030 (%)
Data Table on Compartmentation - Year-over-year growth 2025-2030 (%)

10.6 Opening protection - Market size and forecast 2025-2030

Chart on Opening protection - Market size and forecast 2025-2030 ($ million)
Data Table on Opening protection - Market size and forecast 2025-2030 ($ million)
Chart on Opening protection - Year-over-year growth 2025-2030 (%)
Data Table on Opening protection - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Stringent enforcement of building codes and compliance standards
Surging high-rise commercial and complex urban infrastructure construction
Expanding adoption in industrial, energy, and electric vehicle manufacturing applications

13.2 Market challenges

Raw material volatility pressures industry margins
Complex regulatory frameworks impose high costs
Retrofitting difficulties constrain fire protection upgrades

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Data center growth accelerates material adoption
Electric vehicle infrastructure requires specialized fireproofing
Rapid mass transit projects demand advanced sealants

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 3M Co.

3M Co. - Overview
3M Co. - Business segments
3M Co. - Key news
3M Co. - Key offerings
3M Co. - Segment focus
SWOT

15.5 Akzo Nobel NV

Akzo Nobel NV - Overview
Akzo Nobel NV - Business segments
Akzo Nobel NV - Key offerings
Akzo Nobel NV - Segment focus
SWOT

15.6 Alkegen

Alkegen - Overview
Alkegen - Product / Service
Alkegen - Key offerings
SWOT

15.7 Armacell International SA

Armacell International SA - Overview
Armacell International SA - Product / Service
Armacell International SA - Key offerings
SWOT

15.8 Carboline Co.

Carboline Co. - Overview
Carboline Co. - Product / Service
Carboline Co. - Key offerings
SWOT

15.9 Hempel AS

Hempel AS - Overview
Hempel AS - Product / Service
Hempel AS - Key offerings
SWOT

15.10 Hilti Corp.

Hilti Corp. - Overview
Hilti Corp. - Product / Service
Hilti Corp. - Key offerings
SWOT

15.11 Jotun AS

Jotun AS - Overview
Jotun AS - Product / Service
Jotun AS - Key offerings
SWOT

15.12 Morgan Advanced Materials

Morgan Advanced Materials - Overview
Morgan Advanced Materials - Business segments
Morgan Advanced Materials - Key offerings
Morgan Advanced Materials - Segment focus
SWOT

15.13 PPG Industries Inc.

PPG Industries Inc. - Overview
PPG Industries Inc. - Business segments
PPG Industries Inc. - Key offerings
PPG Industries Inc. - Segment focus
SWOT

15.14 Promat International

Promat International - Overview
Promat International - Product / Service
Promat International - Key offerings
SWOT

15.15 ROCKWOOL AS

ROCKWOOL AS - Overview
ROCKWOOL AS - Business segments
ROCKWOOL AS - Key offerings
ROCKWOOL AS - Segment focus
SWOT

15.16 Sika AG

Sika AG - Overview
Sika AG - Business segments
Sika AG - Key news
Sika AG - Key offerings
Sika AG - Segment focus
SWOT

15.17 Teknos Group Oy

Teknos Group Oy - Overview
Teknos Group Oy - Product / Service
Teknos Group Oy - Key offerings
SWOT

15.18 The Sherwin Williams Co.

The Sherwin Williams Co. - Overview
The Sherwin Williams Co. - Business segments
The Sherwin Williams Co. - Key offerings
The Sherwin Williams Co. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Passive Fire Protection Materials market growth will increase by USD 1402.3 million during 2026-2030.

The Passive Fire Protection Materials market is expected to grow at a CAGR of 5.9% during 2026-2030.

Passive Fire Protection Materials market is segmented by Product type (Cementitious materials, Intumescent coatings, Fireproofing cladding, Fire-resistant sealants, Sprays) Application (Commercial, Industrial, Residential) Type (Structural fireproofing, Firestopping and penetration protection, Compartmentation, Opening protection)

3M Co., Abesco Fire Ltd., Akzo Nobel NV, Alkegen, Armacell International SA, Carboline Co., Contego International Inc., Flame Seal Products Inc., Hempel AS, Hilti Corp., Isolatek International, Jotun AS, Morgan Advanced Materials, Nullifire, PPG Industries Inc., Promat International, ROCKWOOL AS, Sika AG, Teknos Group Oy, The Sherwin Williams Co. are a few of the key vendors in the Passive Fire Protection Materials market.

North America will register the highest growth rate of 35.5% among the other regions. Therefore, the Passive Fire Protection Materials market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Turkey, Israel, Brazil, Argentina, Chile

  • Stringent enforcement of building codes and compliance standards is the driving factor this market.

The Passive Fire Protection Materials market vendors should focus on grabbing business opportunities from the Product type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
