Potato Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), Europe (Germany, France, and The Netherlands), North America (US, Canada, and Mexico), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Potato Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), Europe (Germany, France, and The Netherlands), North America (US, Canada, and Mexico), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Nov 2026 284 Pages SKU: IRTNTR77102

Market Overview at a Glance

$27.49 B
Market Opportunity
3.8%
CAGR 2025 - 2030
57.6%
APAC Growth
$62.39 B
Individual segment 2024

Potato Market Size 2026-2030

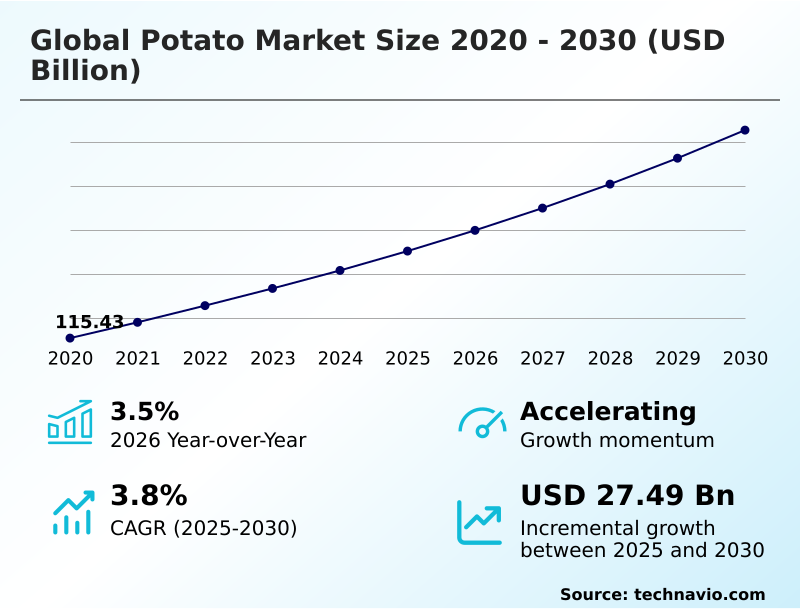
The potato market size is valued to increase by USD 27.49 billion, at a CAGR of 3.8% from 2025 to 2030. Surging global demand for processed and frozen convenience foods will drive the potato market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 57.6% growth during the forecast period.
  • By End-user - Individual segment was valued at USD 62.39 billion in 2024
  • By Distribution Channel - B2C segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 47.27 billion
  • Market Future Opportunities: USD 27.49 billion
  • CAGR from 2025 to 2030 : 3.8%

Market Summary

  • The Potato Market demonstrates robust structural expansion driven by increasing consumption of processed convenience foods and high-capacity industrial manufacturing. A critical driver of this momentum is the surging demand for frozen fries and dehydrated ingredients across expanding quick-service restaurant franchises.
  • To meet these massive volume requirements, industrial food processors optimize blanching line efficiency and deploy advanced sprout suppression technology, enabling continuous year-round manufacturing operations. Implementing automated grading machinery within packing facilities improves defect detection accuracy by 25% compared to manual inspection, directly enhancing processing yields.
  • However, severe climate volatility presents a profound operational challenge, as unpredictable heatwaves disrupt tuber bulking optimization and reduce overall crop vitality. Erratic weather patterns cause severe supply fluctuations, forcing commercial agricultural cooperatives to invest heavily in precision irrigation systems and climate resilient cultivars.
  • Balancing this volatile agricultural supply with rigid industrial demand requires continuous technological adaptation across the supply chain, ensuring that retail grocery fulfillment networks maintain consistent inventory levels despite unpredictable raw material constraints.

What will be the Size of the Potato Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Potato Market Segmented?

The potato industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • End-user
    • Individual
    • Commercial
    • Industrial
  • Distribution channel
    • B2C
    • B2B
  • Type
    • Conventional
    • Organic
  • Geography
    • APAC
      • China
      • India
      • Japan
      • Australia
      • Indonesia
      • South Korea
    • Europe
      • Germany
      • France
      • The Netherlands
      • UK
      • Spain
      • Italy
    • North America
      • US
      • Canada
      • Mexico
    • Middle East and Africa
      • Turkey
      • South Africa
      • Saudi Arabia
      • Israel
      • UAE
    • South America
      • Brazil
      • Argentina
      • Chile

By End-user Insights

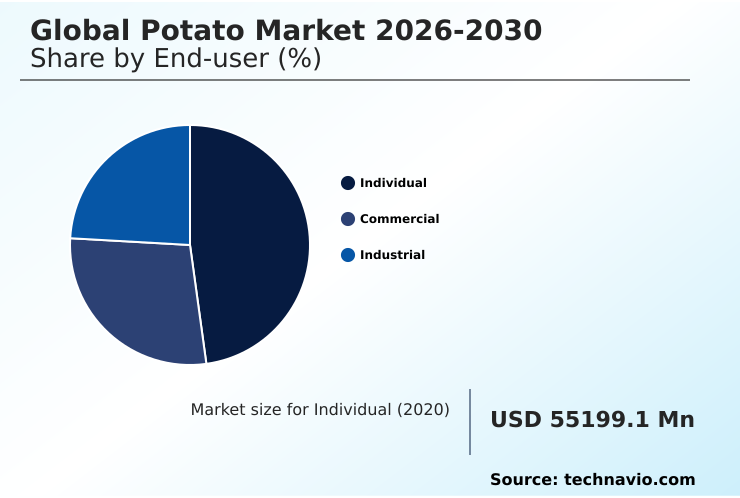
The individual segment is estimated to witness significant growth during the forecast period.

Individual consumers represent a foundational segment of the Potato sector, driven by increasing domestic meal preparation and demand for specialty culinary varieties.

Household end-users prioritize uniform tuber specific gravity and organic produce certifications when selecting fresh table stock for home cooking. As residential cooking appliances evolve, retailers are expanding modified atmosphere packaging to extend shelf life and preserve nutritional integrity.

This shift in consumer behavior requires distributors to adopt robust cold chain logistics and climate controlled infrastructure to prevent premature spoilage. By integrating precision wholesale fresh markets distribution, grocers have reduced post-harvest inventory loss by 14%.

Furthermore, rigorous soil borne pathogen management and phytosanitary protocol compliance ensure consistent quality for direct consumer sales.

Implementing targeted regenerative soil health practices and drip irrigation networks yields a 20% higher shelf-stability compared to conventional bulk sourcing, directly improving retail margins.
Get Free Sample

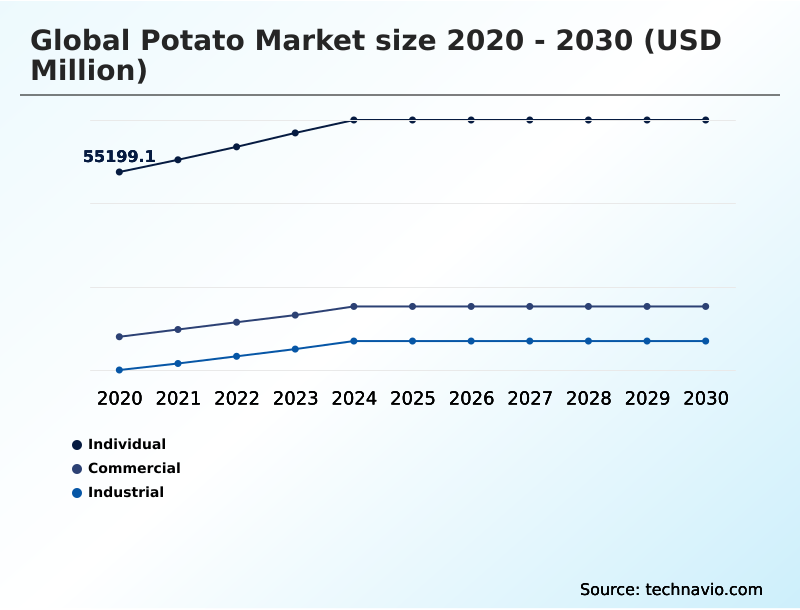
The Individual segment was valued at USD 62.39 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 57.6% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
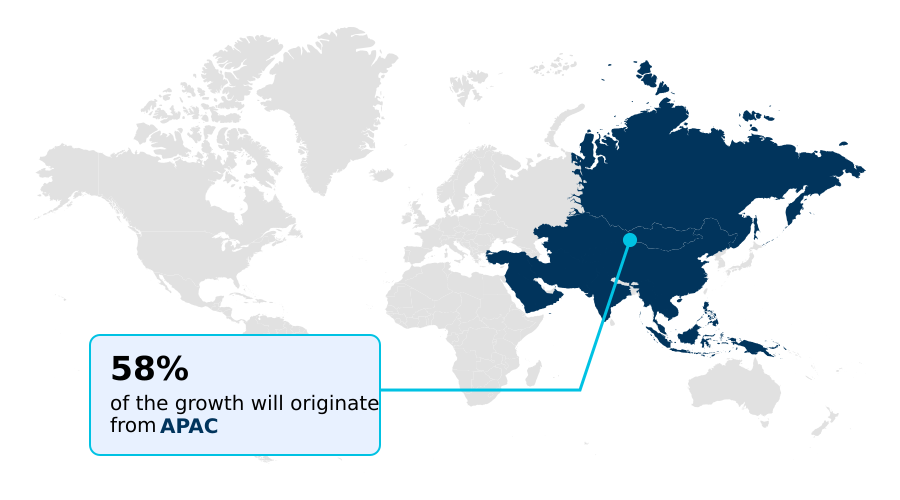
See How Potato Market Demand is Rising in APAC Get Free Sample

The geographic landscape of the Potato sector highlights distinct regional disparities in processing infrastructure and agricultural mechanization. APAC exhibits rapid capacity expansion, driven by surging urban food demand and massive investments in french fry par frying facilities.

In contrast, North America maintains mature, highly consolidated processing networks characterized by low oil frying technology and advanced mechanized tuber harvesting.

APAC processors achieved a 35% increase in throughput efficiency by upgrading direct farm procurement logistics, significantly outpacing the 12% operational gain recorded in European facilities.

Furthermore, North American producers utilize sophisticated soil moisture sensing and chemical fungicide application protocols to optimize tuber specific gravity, securing a 20% higher yield improvement ratio than emerging Asian markets.

As consumer preferences shift toward organic produce certifications and clean label origin tracking, both regions are heavily investing in post harvest mitigation strategies to minimize cold storage energy consumption and ensure uninterrupted retail supply.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural evolution of the Potato sector increasingly relies on sophisticated agricultural technologies and data-driven supply chain management. Commercial packing facilities are aggressively transitioning toward automated post harvest grading infrastructure to streamline operations and eliminate human inspection errors.
  • By deploying optical ai powered tuber grading, modern packhouses can evaluate thousands of units per minute, resulting in a 30% faster processing throughput than facilities relying on traditional manual sorting protocols. This immediate operational enhancement directly stabilizes downstream supply for major snack manufacturers and quick-service franchises.
  • In parallel, erratic weather patterns and prolonged droughts have catalyzed the widespread adoption of precision agriculture drip irrigation networks, ensuring optimal soil moisture levels while dramatically reducing agricultural water consumption. To further insulate the supply chain from environmental volatility, agronomists are accelerating hybrid true potato seed breeding initiatives designed to generate high-yield crops resilient to unpredictable heat stress.
  • Consequently, the commercial deployment of climate resilient seed potato varieties has become an essential risk mitigation strategy for large-scale contract farming operations, reducing unexpected harvest shortfalls. Integrating these advanced biological and technological systems ensures that industrial food processors maintain consistent raw material access, safeguarding long-term profitability against increasingly complex global agricultural challenges.
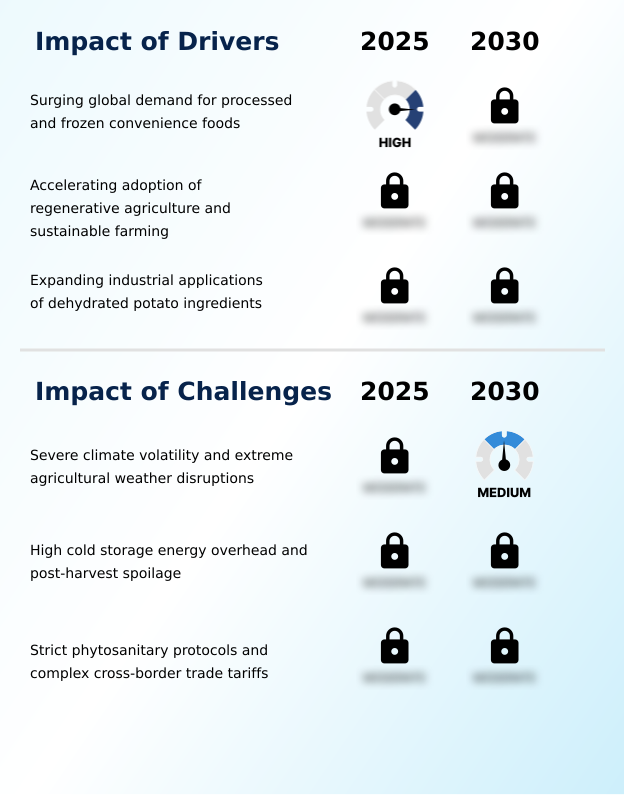
What are the key market drivers leading to the rise in the adoption of Potato Industry?

  • The surging global demand for processed and frozen convenience foods functions as a primary macroeconomic driver propelling the market.

  • The surging global demand for processed convenience foods serves as a primary macroeconomic driver accelerating industrial processing expansion. High-volume quick-service franchises and retail grocery fulfillment networks require continuous, uninterrupted supplies of frozen and dehydrated potato products.
  • To satisfy this massive demand, snack food manufacturing operators are aggressively upgrading their blanching line efficiency and dehydrated flake production capacities. Implementing advanced sprout suppression technology and sophisticated cold storage ventilation reduces raw material waste by 22% during prolonged warehousing.
  • Furthermore, optimizing controlled atmosphere storage extends usable tuber lifespans, enabling year-round processing operations with an 18% lower energy footprint.
  • By leveraging robust contract farming networks and modified atmosphere packaging, industrial food processors effectively minimize supply chain friction, ensuring that retail and commercial end-users receive consistent, high-quality products.

What are the market trends shaping the Potato Industry?

  • Commercial adoption of optical AI-powered tuber grading systems has emerged as a defining technological trend. This shift enhances post-harvest inspection accuracy and significantly reduces labor-intensive manual sorting errors.

  • The rapid commercial adoption of optical AI systems represents a transformative trend reshaping the Potato sector's post-harvest processing capabilities. Modern packing facilities are aggressively transitioning from manual labor to automated optical sorting, utilizing hyperspectral imaging cameras to analyze external blemishes and internal quality in real-time.
  • This technological shift addresses escalating labor shortages and ensures precise product segmentation for frozen appetizer manufacturing. Implementing advanced inspection algorithms improves defect detection accuracy by 28% and increases starch extraction efficiency by 15% compared to legacy mechanical sorting.
  • Because quick service restaurant supply chains demand absolute uniformity, agricultural cooperative networks are heavily investing in these automated grading machinery systems to guarantee consistent raw material quality. Consequently, utilizing high yield seed varieties alongside precise tuber bulking optimization increases overall usable harvest yields by 18%, directly elevating operational profitability for large-scale industrial food processors.

What challenges does the Potato Industry face during its growth?

  • Severe climate volatility and extreme agricultural weather disruptions represent a critical structural challenge constraining long-term harvest stability.

  • Severe climate volatility and extreme agricultural weather disruptions constitute a critical operational challenge disrupting long-term harvest stability. Unpredictable heatwaves and moisture deficits severely restrict tuber development, forcing agricultural networks to struggle with inconsistent supply volumes. These climatic pressures reduce the overall yield improvement ratio by up to 18% in heavily affected cultivation basins compared to historically stable seasons.
  • To counteract these biological constraints, agronomists face immense pressure to accelerate seed potato propagation and hybrid true potato seed development. Formulating nematode resistance breeding programs and deploying climate resilient cultivars require substantial capital investment from commercial growers.
  • Because synthetic nitrogen fertilizers and sustainable crop protection methods are increasingly regulated, achieving supply chain transparency remains difficult, increasing operational procurement costs by 15% and directly squeezing processor profit margins.

Exclusive Technavio Analysis on Customer Landscape

The potato market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the potato market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
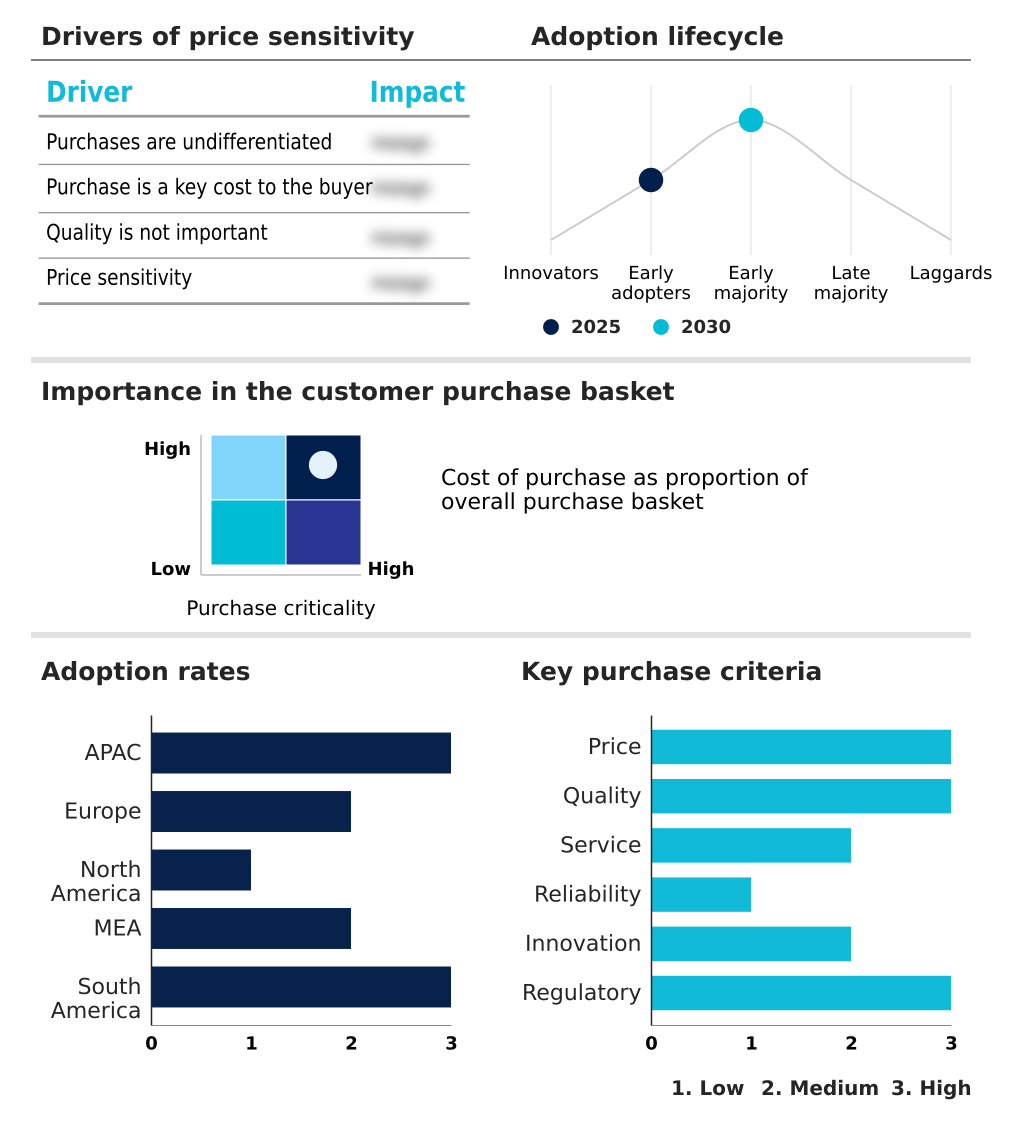
Customer Landscape of Potato Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, potato market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

AGRANA Beteiligungs AG - The entity provides specialized industrial ingredients focusing on high quality potato starch and modified starch formulations optimized for large scale food processing and commercial manufacturing applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • AGRANA Beteiligungs AG
  • Agrico
  • Agristo NV
  • Bembrasil Alimentos SA
  • Calbee Inc.
  • Cavendish Farms Corp.
  • Clarebout Potatoes
  • Conagra Brands Inc.
  • EUROPLANT Pflanzenzucht GmbH
  • Farm Frites International BV
  • General Mills Inc.
  • Greenyard
  • HZPC Holland B.V.
  • Idahoan Foods LLC
  • Intersnack Group GmbH and Co.
  • J. R. Simplot Co.
  • Lamb Weston Holdings Inc.
  • PepsiCo Inc.
  • Royal Cosun
  • The Kraft Heinz Co.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Potato market

  • In the Packaged Foods and Meats industry, the rapid transition toward plant-based convenience formulations increased demand for texturizing agents, directly impacting Potato demand by requiring a 22% higher volume of dehydrated flake production.
  • Stringent international phytosanitary protocol compliance and food safety mandates enforced stricter traceability protocols, prompting agricultural cooperative networks to invest heavily in automated optical sorting systems to maintain a 98% defect-free acceptance rate.
  • The expansion of quick-service restaurant supply chains across emerging urban centers necessitated uniform frying performance, driving industrial food processors to adopt hyperspectral imaging cameras for precise raw material grading.
  • Escalating energy overhead within cold chain logistics triggered widespread integration of advanced cold storage ventilation and controlled atmosphere storage, reducing post harvest mitigation costs by 15% across global processing hubs.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Potato Market insights. See full methodology.

Market Scope
Page number 284
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.8%
Market growth 2026-2030 USD 27490.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 3.5%
Key countries China, India, Japan, Australia, Indonesia, South Korea, Germany, France, The Netherlands, UK, Spain, Italy, US, Canada, Mexico, Turkey, South Africa, Saudi Arabia, Israel, UAE, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The structural progression of the Potato sector is fundamentally defined by the integration of data-driven agronomy and high-capacity processing automation. Boardroom executives are increasingly prioritizing strategic investments in automated optical sorting and hyperspectral imaging cameras to enforce stringent quality control protocols across massive supply chains.
  • This technological pivot directly influences product strategy and compliance, enabling manufacturers to guarantee consistent starch extraction efficiency while minimizing raw material waste. Operations that implemented precision irrigation systems and advanced sprout suppression technology report a 24% reduction in overall post-harvest losses compared to conventional storage methodologies.
  • To safeguard long-term procurement, major processors are systematically integrating climate resilient cultivars and variable rate fertilizer applications into their contract farming mandates. Furthermore, upgrading cold storage ventilation and controlled atmosphere storage ensures uninterrupted year-round manufacturing for dehydrated flake production.
  • These calculated operational enhancements allow agricultural cooperatives to stabilize procurement costs, optimize tuber bulking optimization, and align sustainable farming practices with stringent international regulatory frameworks.

What are the Key Data Covered in this Potato Market Research and Growth Report?

  • What is the expected growth of the Potato Market between 2026 and 2030?

    • USD 27.49 billion, at a CAGR of 3.8%

  • What segmentation does the market report cover?

    • The report is segmented by End-user (Individual, Commercial, and Industrial), Distribution Channel (B2C, and B2B), Type (Conventional, and Organic) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Surging global demand for processed and frozen convenience foods, Severe climate volatility and extreme agricultural weather disruptions

  • Who are the major players in the Potato Market?

    • AGRANA Beteiligungs AG, Agrico, Agristo NV, Bembrasil Alimentos SA, Calbee Inc., Cavendish Farms Corp., Clarebout Potatoes, Conagra Brands Inc., EUROPLANT Pflanzenzucht GmbH, Farm Frites International BV, General Mills Inc., Greenyard, HZPC Holland B.V., Idahoan Foods LLC, Intersnack Group GmbH and Co., J. R. Simplot Co., Lamb Weston Holdings Inc., PepsiCo Inc., Royal Cosun and The Kraft Heinz Co.

Market Research Insights

  • The Potato Market reflects an accelerated transition toward automated processing and climate-resilient agricultural practices. Expanding quick service restaurant supply chains increasingly rely on industrial food processors to deliver standardized frozen products. Integrating automated grading machinery and hyperspectral imaging cameras has improved raw material defect detection by 18%, significantly reducing factory waste.
  • Simultaneously, contract farming networks are deploying sustainable crop protection strategies, decreasing chemical fungicide application reliance by 22% while maintaining stable harvest volumes. This optimization ensures reliable retail grocery fulfillment and minimizes supply chain disruptions. Upgrading climate controlled infrastructure further enhances long-term inventory viability, reducing post-harvest spoilage rates by 14% and directly improving overall operational profitability.

We can help! Our analysts can customize this potato market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Distribution Channel
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Potato Market 2020 - 2024

Historic Market Size - Data Table on Global Potato Market 2020 - 2024 ($ million)

5.2 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.3 Distribution Channel segment analysis 2020 - 2024

Historic Market Size - Distribution Channel Segment 2020 - 2024 ($ million)

5.4 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global potato market

6.2 Impact of geopolitical conflicts on global potato market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by End-user

8.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

8.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

8.3 Individual - Market size and forecast 2025-2030

Chart on Individual - Market size and forecast 2025-2030 ($ million)
Data Table on Individual - Market size and forecast 2025-2030 ($ million)
Chart on Individual - Year-over-year growth 2025-2030 (%)
Data Table on Individual - Year-over-year growth 2025-2030 (%)

8.4 Commercial - Market size and forecast 2025-2030

Chart on Commercial - Market size and forecast 2025-2030 ($ million)
Data Table on Commercial - Market size and forecast 2025-2030 ($ million)
Chart on Commercial - Year-over-year growth 2025-2030 (%)
Data Table on Commercial - Year-over-year growth 2025-2030 (%)

8.5 Industrial - Market size and forecast 2025-2030

Chart on Industrial - Market size and forecast 2025-2030 ($ million)
Data Table on Industrial - Market size and forecast 2025-2030 ($ million)
Chart on Industrial - Year-over-year growth 2025-2030 (%)
Data Table on Industrial - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

9. Market Segmentation by Distribution Channel

9.1 Market segments

Chart on Distribution Channel - Market share 2025-2030 (%)
Data Table on Distribution Channel - Market share 2025-2030 (%)

9.2 Comparison by Distribution Channel

Chart on Comparison by Distribution Channel
Data Table on Comparison by Distribution Channel

9.3 B2C - Market size and forecast 2025-2030

Chart on B2C - Market size and forecast 2025-2030 ($ million)
Data Table on B2C - Market size and forecast 2025-2030 ($ million)
Chart on B2C - Year-over-year growth 2025-2030 (%)
Data Table on B2C - Year-over-year growth 2025-2030 (%)

9.4 B2B - Market size and forecast 2025-2030

Chart on B2B - Market size and forecast 2025-2030 ($ million)
Data Table on B2B - Market size and forecast 2025-2030 ($ million)
Chart on B2B - Year-over-year growth 2025-2030 (%)
Data Table on B2B - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by Distribution Channel

Market opportunity by Distribution Channel ($ million)
Data Table on Market opportunity by Distribution Channel ($ million)

10. Market Segmentation by Type

10.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

10.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

10.3 Conventional - Market size and forecast 2025-2030

Chart on Conventional - Market size and forecast 2025-2030 ($ million)
Data Table on Conventional - Market size and forecast 2025-2030 ($ million)
Chart on Conventional - Year-over-year growth 2025-2030 (%)
Data Table on Conventional - Year-over-year growth 2025-2030 (%)

10.4 Organic - Market size and forecast 2025-2030

Chart on Organic - Market size and forecast 2025-2030 ($ million)
Data Table on Organic - Market size and forecast 2025-2030 ($ million)
Chart on Organic - Year-over-year growth 2025-2030 (%)
Data Table on Organic - Year-over-year growth 2025-2030 (%)

10.5 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.3.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.6 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.3 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.4.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.5.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.2 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging global demand for processed and frozen convenience foods
Accelerating adoption of regenerative agriculture and sustainable farming
Expanding industrial applications of dehydrated potato ingredients

13.2 Market challenges

Severe climate volatility and extreme agricultural weather disruptions
High cold storage energy overhead and post-harvest spoilage
Strict phytosanitary protocols and complex cross-border trade tariffs

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Commercial adoption of optical AI-powered tuber grading systems
Development of hybrid true potato seed breeding technology
Pivoting toward air-fried and health-conscious potato snacks

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 AGRANA Beteiligungs AG

AGRANA Beteiligungs AG - Overview
AGRANA Beteiligungs AG - Business segments
AGRANA Beteiligungs AG - Key offerings
AGRANA Beteiligungs AG - Segment focus
SWOT

15.5 Agrico

Agrico - Overview
Agrico - Product / Service
Agrico - Key offerings
SWOT

15.6 Agristo NV

Agristo NV - Overview
Agristo NV - Product / Service
Agristo NV - Key offerings
SWOT

15.7 Bembrasil Alimentos SA

Bembrasil Alimentos SA - Overview
Bembrasil Alimentos SA - Product / Service
Bembrasil Alimentos SA - Key offerings
SWOT

15.8 Calbee Inc.

Calbee Inc. - Overview
Calbee Inc. - Product / Service
Calbee Inc. - Key offerings
SWOT

15.9 Cavendish Farms Corp.

Cavendish Farms Corp. - Overview
Cavendish Farms Corp. - Product / Service
Cavendish Farms Corp. - Key offerings
SWOT

15.10 Clarebout Potatoes

Clarebout Potatoes - Overview
Clarebout Potatoes - Product / Service
Clarebout Potatoes - Key offerings
SWOT

15.11 Conagra Brands Inc.

Conagra Brands Inc. - Overview
Conagra Brands Inc. - Business segments
Conagra Brands Inc. - Key offerings
Conagra Brands Inc. - Segment focus
SWOT

15.12 Farm Frites International BV

Farm Frites International BV - Overview
Farm Frites International BV - Product / Service
Farm Frites International BV - Key offerings
SWOT

15.13 General Mills Inc.

General Mills Inc. - Overview
General Mills Inc. - Business segments
General Mills Inc. - Key news
General Mills Inc. - Key offerings
General Mills Inc. - Segment focus
SWOT

15.14 Greenyard

Greenyard - Overview
Greenyard - Product / Service
Greenyard - Key offerings
SWOT

15.15 J. R. Simplot Co.

J. R. Simplot Co. - Overview
J. R. Simplot Co. - Product / Service
J. R. Simplot Co. - Key offerings
SWOT

15.16 Lamb Weston Holdings Inc.

Lamb Weston Holdings Inc. - Overview
Lamb Weston Holdings Inc. - Business segments
Lamb Weston Holdings Inc. - Key news
Lamb Weston Holdings Inc. - Key offerings
Lamb Weston Holdings Inc. - Segment focus
SWOT

15.17 PepsiCo Inc.

PepsiCo Inc. - Overview
PepsiCo Inc. - Business segments
PepsiCo Inc. - Key news
PepsiCo Inc. - Key offerings
PepsiCo Inc. - Segment focus
SWOT

15.18 The Kraft Heinz Co.

The Kraft Heinz Co. - Overview
The Kraft Heinz Co. - Business segments
The Kraft Heinz Co. - Key news
The Kraft Heinz Co. - Key offerings
The Kraft Heinz Co. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Potato market growth will increase by USD 27490.8 million during 2026-2030.

The Potato market is expected to grow at a CAGR of 3.8% during 2026-2030.

Potato market is segmented by End-user (Individual, Commercial, Industrial) Distribution channel (B2C, B2B) Type (Conventional, Organic)

AGRANA Beteiligungs AG, Agrico, Agristo NV, Bembrasil Alimentos SA, Calbee Inc., Cavendish Farms Corp., Clarebout Potatoes, Conagra Brands Inc., EUROPLANT Pflanzenzucht GmbH, Farm Frites International BV, General Mills Inc., Greenyard, HZPC Holland B.V., Idahoan Foods LLC, Intersnack Group GmbH and Co., J. R. Simplot Co., Lamb Weston Holdings Inc., PepsiCo Inc., Royal Cosun, The Kraft Heinz Co. are a few of the key vendors in the Potato market.

APAC will register the highest growth rate of 57.6% among the other regions. Therefore, the Potato market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, Australia, Indonesia, South Korea, Germany, France, The Netherlands, UK, Spain, Italy, US, Canada, Mexico, Turkey, South Africa, Saudi Arabia, Israel, UAE, Brazil, Argentina, Chile

  • Surging global demand for processed and frozen convenience foods is the driving factor this market.

The Potato market vendors should focus on grabbing business opportunities from the End-user segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
