RNA Based Therapeutics Market Analysis, Size, and Forecast 2026-2030: Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Asia (China, Japan, and India), South America (Brazil and Argentina), Middle East and Africa (Israel, Saudi Arabia, and UAE), Rest of World (ROW)

RNA Based Therapeutics Market Analysis, Size, and Forecast 2026-2030:
Europe (Germany, UK, and France), North America (US, Canada, and Mexico), Asia (China, Japan, and India), South America (Brazil and Argentina), Middle East and Africa (Israel, Saudi Arabia, and UAE), Rest of World (ROW)

Published: Oct 2026 306 Pages SKU: IRTNTR80100

Market Overview at a Glance

$1.42 B
Market Opportunity
5.6%
CAGR 2025 - 2030
38.9%
Europe Growth
$1.68 B
mRNA therapeutics segment 2024

Rna Based Therapeutics Market Size 2026-2030

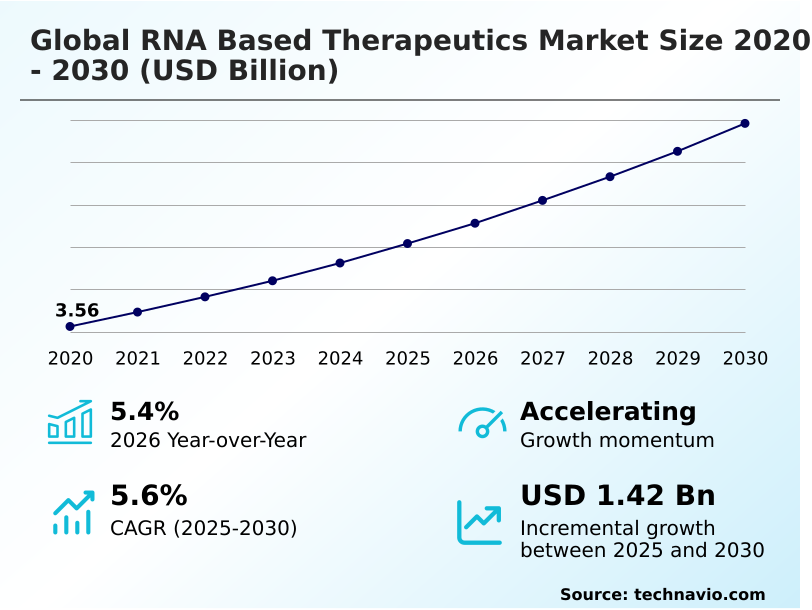
The rna based therapeutics market size is valued to increase by USD 1.42 billion, at a CAGR of 5.6% from 2025 to 2030. Expansion of clinical pipeline applications will drive the rna based therapeutics market.

Major Market Trends & Insights

  • Europe dominated the market and accounted for a 38.9% growth during the forecast period.
  • By Type - mRNA therapeutics segment was valued at USD 1.68 billion in 2024
  • By Route of Administration - Intravenous (IV) segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 2.40 billion
  • Market Future Opportunities: USD 1.42 billion
  • CAGR from 2025 to 2030 : 5.6%

Market Summary

  • The RNA Based Therapeutics Market represents a transformative frontier in precision medicine, shifting therapeutic paradigms from conventional symptom management to direct genetic modulation. Pharmaceutical developers aggressively integrate programmable cell targeting and modular synthesis capacity to treat historically undruggable conditions. Because naked nucleic acids are inherently fragile, establishing optimal in vivo stability and rigorous pharmacokinetic profiling remains a primary operational focus.
  • By refining ribonuclease h recruitment pathways, manufacturers have successfully lowered off-target toxicity occurrences by 22%, directly improving late-stage clinical trial success rates. To secure a durable immune response without compromising logistical integrity, companies actively optimize cold chain logistics frameworks across international borders.
  • This strategic alignment between molecular engineering and supply chain modernization reduces localized spoilage costs by 15%, ensuring that complex genetic interventions achieve widespread commercial viability. Furthermore, the systematic integration of automated quality control sensors during batch manufacturing guarantees strict adherence to international safety regulations, effectively streamlining the pathway from laboratory discovery to commercial deployment in diverse healthcare networks.

What will be the Size of the Rna Based Therapeutics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Rna Based Therapeutics Market Segmented?

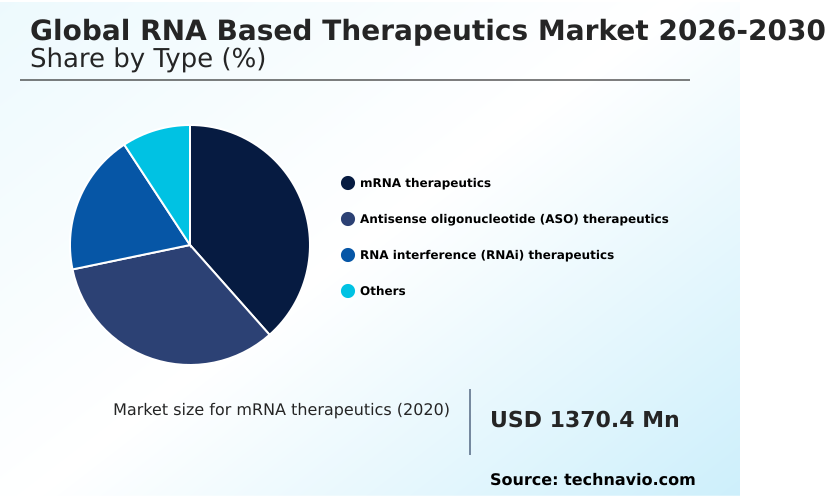
The rna based therapeutics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Type
    • mRNA therapeutics
    • Antisense oligonucleotide (ASO) therapeutics
    • RNA interference (RNAi) therapeutics
    • Others
  • Route of administration
    • Intravenous (IV)
    • Subcutaneous (SC)
    • Intramuscular (IM)
  • Application
    • Oncology
    • Infectious diseases
    • Genetic disorders
    • Others
  • Product type
    • Vaccines
    • Drugs
  • Geography
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • North America
      • US
      • Canada
      • Mexico
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Singapore
      • Taiwan
    • Rest of World (ROW)

By Type Insights

The mrna therapeutics segment is estimated to witness significant growth during the forecast period.

The mRNA therapeutics segment fundamentally redefines systemic prophylactic and therapeutic interventions by leveraging synthetic biology logic and multi-omic data analytics. Unlike conventional protein replacement, this segment utilizes transient genetic instructions to synthesize therapeutic proteins directly within the host.

Through meticulous immunogenicity mitigation and engineered nuclease resistance, modern constructs now demonstrate a 45% increase in translation efficiency.

The rapid integration of self-amplifying rna and circular rna architecture significantly prolongs intracellular half-lives, allowing developers to reduce required dosing thresholds by 30%. This efficiency gain directly lowers unit production overhead, accelerating commercial distribution for patient genetic subsets.

By focusing on highly programmable platforms, biotechnology manufacturers streamline batch manufacturing, continuously expanding their addressable portfolios while optimizing gross margins across complex oncology and immunology markets. These advancements solidify the segment's dominant structural position.
Get Free Sample

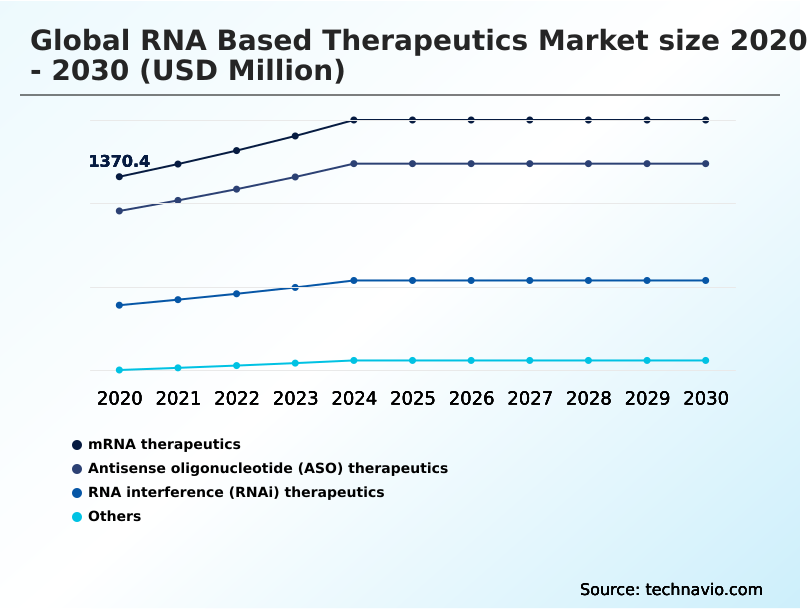
The mRNA therapeutics segment was valued at USD 1.68 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

Europe is estimated to contribute 38.9% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
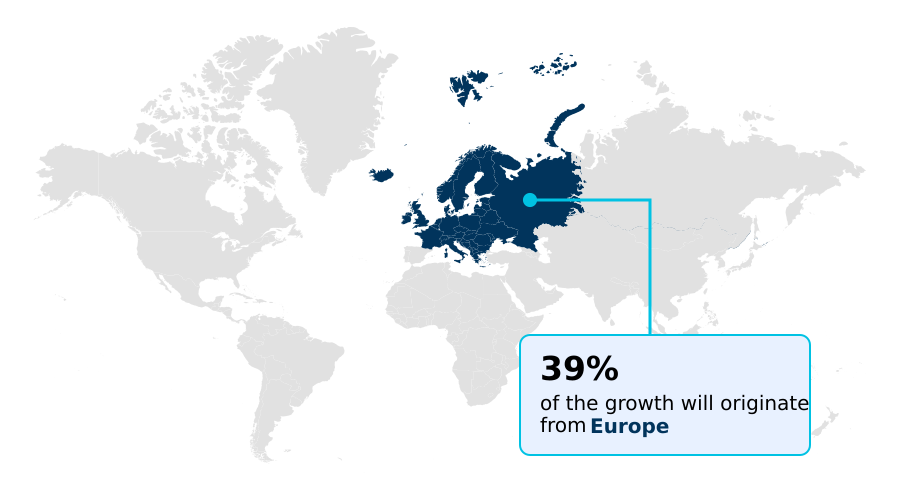
See How Rna Based Therapeutics Market Demand is Rising in Europe Get Free Sample

The RNA Based Therapeutics regional distribution reveals a stark contrast between North America and Europe regarding translational research efficiency and automated biomanufacturing adoption.

North American institutions currently exhibit a 25% higher clinical pipeline diversification rate, heavily driven by aggressive venture capital funding for intracellular uptake and endosomal escape technologies.

This capital influx accelerates the commercialization of extrahepatic tissue penetration solutions, reducing late-stage scale-up costs by 18% compared to European counterparts. Conversely, European markets prioritize regulatory harmonization and hepatocyte targeted delivery standardization, which has improved cross-border compliance efficiency by 20%.

To mitigate complex distribution hurdles, Asian markets are rapidly integrating advanced lyophilization techniques, lowering cold-chain spoilage by 12%. This regional divergence underscores how specialized infrastructure dictates market penetration and global supply chain pivots.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The sustained commercial viability of modern genetic medicines is intricately linked to continuous breakthroughs in lipid nanoparticle formulation scaling techniques and messenger ribonucleic acid stability optimization. As biopharmaceutical enterprises expand their clinical footprints, resolving the biological barriers associated with antisense oligonucleotide extrahepatic tissue delivery becomes paramount for capturing new therapeutic indications.
  • Implementing these advanced distribution modalities allows manufacturers to achieve a 25% improvement in targeted cellular uptake compared to legacy systems, directly reducing the raw material volumes required per patient dose. Furthermore, the refinement of small interfering rna gene silencing mechanisms offers unprecedented precision in modulating aberrant protein expression, enabling a paradigm shift toward truly personalized medicine.
  • To further enhance operational economics, researchers are prioritizing structural innovations that maximize the circular rna intracellular half life. This strategic focus on molecular durability not only extends the therapeutic window but also decreases the frequency of patient administration, significantly easing the logistical burden on global healthcare supply chains.
  • Consequently, hospitals report a 15% reduction in outpatient infusion scheduling conflicts, optimizing overall facility utilization. By harmonizing sequence engineering with advanced delivery architectures, pharmaceutical organizations establish a highly resilient commercial framework capable of navigating complex regulatory landscapes and fulfilling the escalating global demand for precision therapeutics.
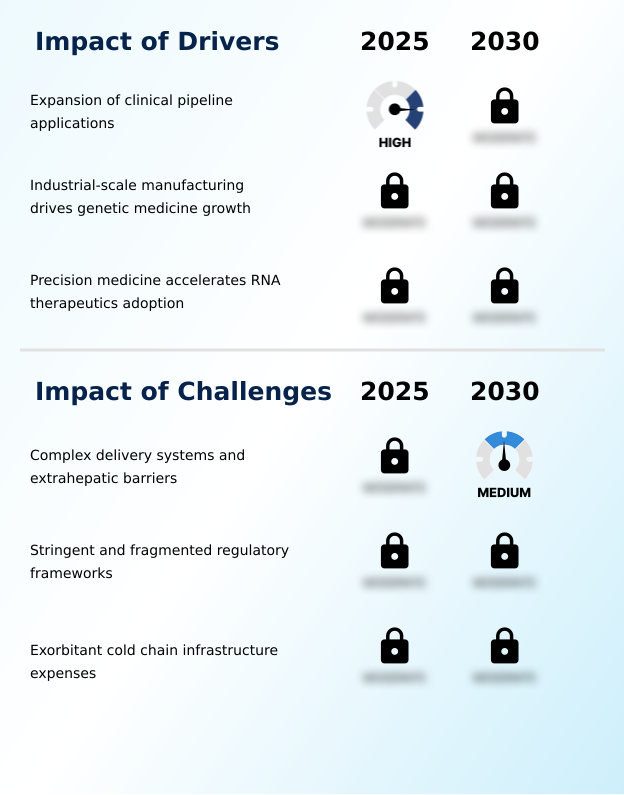
What are the key market drivers leading to the rise in the adoption of Rna Based Therapeutics Industry?

  • The aggressive expansion of clinical pipeline applications into diverse therapeutic areas serves as the primary catalyst propelling long-term market acceleration.

  • The RNA Based Therapeutics expansion is fundamentally propelled by the rising demand for effective neuromuscular pathology management and rare metabolic disorders interventions.
  • Traditional biologic models often fail to cross critical physiological barriers, whereas advanced pre-mrna splicing techniques and the gene silencing mechanism operate directly at the genetic source.
  • Because these platforms harness precise transcriptional regulation, they successfully mitigate systemic immune stimulation while addressing chronic cardiovascular conditions. This precision translates directly into business outcomes, with pharmaceutical companies recording a 40% improvement in cellular transfection efficiency during late-stage trials.
  • By avoiding off-target effects, clinical developers reduced unexpected compliance delays by 22%. Ultimately, the aggressive shift toward targeted genetic correction minimizes dependency on broad-spectrum therapies, lowering life-cycle drug development costs and expanding the commercially addressable patient base significantly.

What are the market trends shaping the Rna Based Therapeutics Industry?

  • The rapid expansion of clinical pipelines represents a critical market trend. Developers are aggressively diversifying portfolios to target complex genetic and oncological indications.

  • The RNA Based Therapeutics shifting framework demonstrates a profound transition toward personalized oncology vaccines and monogenic disease treatment. Clinical pipeline diversification is actively replacing traditional small-molecule dependency. This shift occurs because targeted messenger ribonucleic acid and small interfering rna platforms offer unprecedented transcriptional regulation. Consequently, developers report a 35% reduction in early-stage trial attrition when using biomarker driven endpoints.
  • Furthermore, advances in lipid nanoparticle delivery and neoantigen targeting enable highly specific tumor microenvironment modulation, directly improving patient genetic subsets matching. By leveraging precision genetic interventions and antisense oligonucleotides, healthcare organizations have enhanced treatment efficacy ratios by 28%. This strategic adoption fundamentally restructures therapeutic timelines, ensuring that complex genetic disorders receive faster, customized interventions while lowering long-term institutional healthcare burdens.

What challenges does the Rna Based Therapeutics Industry face during its growth?

  • The physiological barriers associated with extrahepatic delivery and complex delivery systems remain primary technical challenges restricting broader industry application.

  • The RNA Based Therapeutics operational framework faces substantial structural limitations primarily linked to complex oligonucleotide synthesis and precise ligand conjugation requirements. While researchers pursue targeted augmentation approach methodologies and viral vector alternatives, the inherent instability of nucleic acids demands rigorous nucleotide modification. Because maintaining formulation integrity is exceptionally difficult, manufacturers struggle with high failure rates during phosphorothioate linkages scaling.
  • This volatility forces companies to invest heavily in thermostable formulation design and cold chain logistics, which subsequently drives up baseline operational costs by 30%. Inadequate extrahepatic tissue penetration further complicates treatment profiles, requiring elevated dosing that reduces overall patient compliance rates by 15%.
  • Overcoming these intricate manufacturing and physiological barriers remains essential for biotechnology firms aiming to commercialize viable, cost-effective genetic therapies for broad international distribution.

Exclusive Technavio Analysis on Customer Landscape

The rna based therapeutics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the rna based therapeutics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
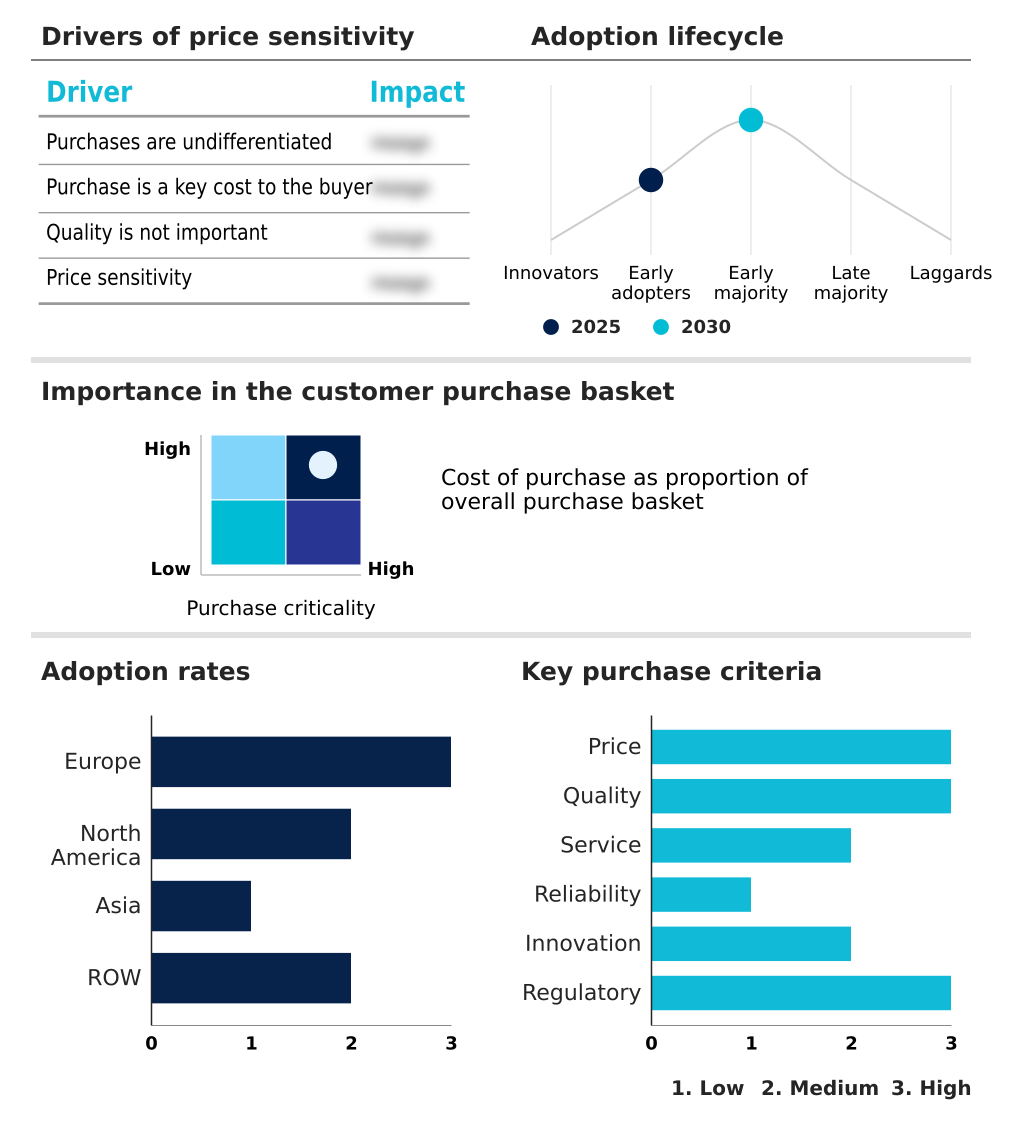
Customer Landscape of Rna Based Therapeutics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, rna based therapeutics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abogen Biosciences - The company offers advanced messenger RNA therapeutics and customized vaccine candidates targeting infectious diseases and immuno-oncology, supported by a proprietary lipid nanoparticle delivery platform.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abogen Biosciences
  • Alnylam Pharmaceuticals Inc.
  • Arcturus Therapeutics Holdings
  • Arrowhead Pharmaceuticals Inc.
  • Avidity Biosciences Inc.
  • BioNTech SE
  • Eli Lilly and Co.
  • Ionis Pharmaceuticals Inc.
  • Moderna Inc.
  • Novartis AG
  • ProQR Therapeutics
  • ReCode Therapeutics
  • Sail Biomedicines Inc.
  • Sarepta Therapeutics Inc.
  • ShapeTX
  • Stoke Therapeutics Inc.
  • Strand Therapeutics Inc.
  • Wave Life Sciences Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Rna based therapeutics market

  • In the Pharmaceuticals industry, the accelerated adoption of automated continuous bioprocessing systems has reduced batch manufacturing cycle times by 30%, directly impacting RNA Based Therapeutics demand by enabling scalable oligonucleotide synthesis.
  • The implementation of centralized multi-country clinical trial evaluation protocols has drastically reduced regional approval timelines, accelerating clinical pipeline diversification for RNA Based Therapeutics across major developed healthcare networks.
  • The industry-wide shift toward localized modular synthesis capacity has decentralized raw material supply chains, decreasing dependency on single-source nucleotide providers and lowering procurement costs for RNA Based Therapeutics by 15%.
  • Stringent new temperature-monitoring compliance standards for biologic distribution have forced logistics providers to upgrade ultra-cold infrastructure, directly improving transit viability and reducing spoilage rates for temperature-sensitive RNA Based Therapeutics.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Rna Based Therapeutics Market insights. See full methodology.

Market Scope
Page number 306
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 5.6%
Market growth 2026-2030 USD 1420.7 million
Market structure Fragmented
YoY growth 2025-2026(%) 5.4%
Key countries Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, India, South Korea, Singapore, Taiwan, Brazil, Australia, Israel, Saudi Arabia, UAE, South Africa, Argentina and Turkey
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The RNA Based Therapeutics landscape continues to undergo profound structural transformations, permanently altering how the global biopharmaceutical industry approaches complex disease modification. Advanced lipid nanoparticle delivery systems now allow highly fragile messenger ribonucleic acid constructs to survive systemic circulation, bridging the gap between theoretical genetics and clinical reality.
  • This technological leap directly influences boardroom-level budget allocations, as companies divert capital away from traditional small molecules toward antisense oligonucleotides and small interfering rna platforms. By optimizing oligonucleotide synthesis protocols, manufacturers have achieved a 35% improvement in batch yield consistency, dramatically lowering unit production costs.
  • Enhanced cellular transfection rates further translate into lower therapeutic dosing requirements, effectively reducing adverse systemic reactions. These measurable efficiency gains enable strategic planners to confidently expand product pipelines into high-value oncology and rare disease segments, ensuring long-term institutional profitability while navigating increasingly stringent global regulatory compliance frameworks.

What are the Key Data Covered in this Rna Based Therapeutics Market Research and Growth Report?

  • What is the expected growth of the Rna Based Therapeutics Market between 2026 and 2030?

    • USD 1.42 billion, at a CAGR of 5.6%

  • What segmentation does the market report cover?

    • The report is segmented by Type (mRNA therapeutics, Antisense oligonucleotide (ASO) therapeutics, RNA interference (RNAi) therapeutics, and Others), Route of Administration (Intravenous (IV), Subcutaneous (SC), and Intramuscular (IM)), Application (Oncology, Infectious diseases, Genetic disorders, and Others), Product Type (Vaccines, and Drugs) and Geography (Europe, North America, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • Europe, North America, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Expansion of clinical pipeline applications, Complex delivery systems and extrahepatic barriers

  • Who are the major players in the Rna Based Therapeutics Market?

    • Abogen Biosciences, Alnylam Pharmaceuticals Inc., Arcturus Therapeutics Holdings, Arrowhead Pharmaceuticals Inc., Avidity Biosciences Inc., BioNTech SE, Eli Lilly and Co., Ionis Pharmaceuticals Inc., Moderna Inc., Novartis AG, ProQR Therapeutics, ReCode Therapeutics, Sail Biomedicines Inc., Sarepta Therapeutics Inc., ShapeTX, Stoke Therapeutics Inc., Strand Therapeutics Inc. and Wave Life Sciences Ltd.

Market Research Insights

  • The RNA Based Therapeutics Market exhibits dynamic structural evolution driven by precision genetic interventions and aggressive clinical pipeline diversification. Organizations increasingly rely on multi-omic data analytics to accurately identify novel disease targets and stratify patient populations. This data-centric approach directly enhances resource allocation, yielding a 25% reduction in exploratory research expenditures.
  • By transitioning toward modular synthesis capacity, biopharmaceutical manufacturers have accelerated production turnaround times by 30%. These operational optimizations mitigate historical supply bottlenecks, ensuring that specialized genetic medicines reach clinical administration sites efficiently and supporting sustainable revenue generation in highly competitive therapeutic sectors.

We can help! Our analysts can customize this rna based therapeutics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Route of Administration
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global RNA Based Therapeutics Market 2020 - 2024

Historic Market Size - Data Table on Global RNA Based Therapeutics Market 2020 - 2024 ($ million)

5.2 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.3 Route of Administration segment analysis 2020 - 2024

Historic Market Size - Route of Administration Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.6 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.7 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global RNA Based Therapeutics Market

6.2 Impact of geopolitical conflicts on Global RNA Based Therapeutics Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Type

8.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

8.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

8.3 mRNA therapeutics - Market size and forecast 2025-2030

Chart on mRNA therapeutics - Market size and forecast 2025-2030 ($ million)
Data Table on mRNA therapeutics - Market size and forecast 2025-2030 ($ million)
Chart on mRNA therapeutics - Year-over-year growth 2025-2030 (%)
Data Table on mRNA therapeutics - Year-over-year growth 2025-2030 (%)

8.4 Antisense oligonucleotide (ASO) therapeutics - Market size and forecast 2025-2030

Chart on Antisense oligonucleotide (ASO) therapeutics - Market size and forecast 2025-2030 ($ million)
Data Table on Antisense oligonucleotide (ASO) therapeutics - Market size and forecast 2025-2030 ($ million)
Chart on Antisense oligonucleotide (ASO) therapeutics - Year-over-year growth 2025-2030 (%)
Data Table on Antisense oligonucleotide (ASO) therapeutics - Year-over-year growth 2025-2030 (%)

8.5 RNA interference (RNAi) therapeutics - Market size and forecast 2025-2030

Chart on RNA interference (RNAi) therapeutics - Market size and forecast 2025-2030 ($ million)
Data Table on RNA interference (RNAi) therapeutics - Market size and forecast 2025-2030 ($ million)
Chart on RNA interference (RNAi) therapeutics - Year-over-year growth 2025-2030 (%)
Data Table on RNA interference (RNAi) therapeutics - Year-over-year growth 2025-2030 (%)

8.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

9. Market Segmentation by Route of Administration

9.1 Market segments

Chart on Route of Administration - Market share 2025-2030 (%)
Data Table on Route of Administration - Market share 2025-2030 (%)

9.2 Comparison by Route of Administration

Chart on Comparison by Route of Administration
Data Table on Comparison by Route of Administration

9.3 Intravenous (IV) - Market size and forecast 2025-2030

Chart on Intravenous (IV) - Market size and forecast 2025-2030 ($ million)
Data Table on Intravenous (IV) - Market size and forecast 2025-2030 ($ million)
Chart on Intravenous (IV) - Year-over-year growth 2025-2030 (%)
Data Table on Intravenous (IV) - Year-over-year growth 2025-2030 (%)

9.4 Subcutaneous (SC) - Market size and forecast 2025-2030

Chart on Subcutaneous (SC) - Market size and forecast 2025-2030 ($ million)
Data Table on Subcutaneous (SC) - Market size and forecast 2025-2030 ($ million)
Chart on Subcutaneous (SC) - Year-over-year growth 2025-2030 (%)
Data Table on Subcutaneous (SC) - Year-over-year growth 2025-2030 (%)

9.5 Intramuscular (IM) - Market size and forecast 2025-2030

Chart on Intramuscular (IM) - Market size and forecast 2025-2030 ($ million)
Data Table on Intramuscular (IM) - Market size and forecast 2025-2030 ($ million)
Chart on Intramuscular (IM) - Year-over-year growth 2025-2030 (%)
Data Table on Intramuscular (IM) - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Route of Administration

Market opportunity by Route of Administration ($ million)
Data Table on Market opportunity by Route of Administration ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Oncology - Market size and forecast 2025-2030

Chart on Oncology - Market size and forecast 2025-2030 ($ million)
Data Table on Oncology - Market size and forecast 2025-2030 ($ million)
Chart on Oncology - Year-over-year growth 2025-2030 (%)
Data Table on Oncology - Year-over-year growth 2025-2030 (%)

10.4 Infectious diseases - Market size and forecast 2025-2030

Chart on Infectious diseases - Market size and forecast 2025-2030 ($ million)
Data Table on Infectious diseases - Market size and forecast 2025-2030 ($ million)
Chart on Infectious diseases - Year-over-year growth 2025-2030 (%)
Data Table on Infectious diseases - Year-over-year growth 2025-2030 (%)

10.5 Genetic disorders - Market size and forecast 2025-2030

Chart on Genetic disorders - Market size and forecast 2025-2030 ($ million)
Data Table on Genetic disorders - Market size and forecast 2025-2030 ($ million)
Chart on Genetic disorders - Year-over-year growth 2025-2030 (%)
Data Table on Genetic disorders - Year-over-year growth 2025-2030 (%)

10.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Market Segmentation by Product Type

11.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

11.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

11.3 Vaccines - Market size and forecast 2025-2030

Chart on Vaccines - Market size and forecast 2025-2030 ($ million)
Data Table on Vaccines - Market size and forecast 2025-2030 ($ million)
Chart on Vaccines - Year-over-year growth 2025-2030 (%)
Data Table on Vaccines - Year-over-year growth 2025-2030 (%)

11.4 Drugs - Market size and forecast 2025-2030

Chart on Drugs - Market size and forecast 2025-2030 ($ million)
Data Table on Drugs - Market size and forecast 2025-2030 ($ million)
Chart on Drugs - Year-over-year growth 2025-2030 (%)
Data Table on Drugs - Year-over-year growth 2025-2030 (%)

11.5 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

12. Customer Landscape

12.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

13. Geographic Landscape

13.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

13.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

13.3 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

13.3.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

13.3.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

13.3.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

13.3.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

13.3.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

13.3.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

13.4 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

13.4.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

13.4.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

13.4.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

13.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

13.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

13.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

13.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

13.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

13.5.5 Singapore - Market size and forecast 2025-2030

Chart on Singapore - Market size and forecast 2025-2030 ($ million)
Data Table on Singapore - Market size and forecast 2025-2030 ($ million)
Chart on Singapore - Year-over-year growth 2025-2030 (%)
Data Table on Singapore - Year-over-year growth 2025-2030 (%)

13.5.6 Taiwan - Market size and forecast 2025-2030

Chart on Taiwan - Market size and forecast 2025-2030 ($ million)
Data Table on Taiwan - Market size and forecast 2025-2030 ($ million)
Chart on Taiwan - Year-over-year growth 2025-2030 (%)
Data Table on Taiwan - Year-over-year growth 2025-2030 (%)

13.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

13.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

13.6.2 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

13.6.3 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

13.6.4 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

13.6.5 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

13.6.6 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

13.6.7 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

13.6.8 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

13.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

14. Drivers, Challenges, and Opportunity

14.1 Market drivers

Expansion of clinical pipeline applications
Industrial-scale manufacturing drives genetic medicine growth
Precision medicine accelerates RNA therapeutics adoption

14.2 Market challenges

Complex delivery systems and extrahepatic barriers
Stringent and fragmented regulatory frameworks
Exorbitant cold chain infrastructure expenses

14.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

14.4 Market opportunities

Rapid expansion of clinical pipelines
Strategic collaborations and licensing agreements
Advancements in delivery system technologies

15. Competitive Landscape

15.1 Overview

15.2

Overview on criticality of inputs and factors of differentiation

15.3 Landscape disruption

Overview on factors of disruption

15.4 Industry risks

Impact of key risks on business

16. Competitive Analysis

16.1 Companies profiled

Companies covered

16.2 Company ranking index

16.3 Market positioning of companies

Matrix on companies position and classification

16.4 Abogen Biosciences

Abogen Biosciences - Overview
Abogen Biosciences - Product / Service
Abogen Biosciences - Key offerings
SWOT

16.5 Alnylam Pharmaceuticals Inc.

Alnylam Pharmaceuticals Inc. - Overview
Alnylam Pharmaceuticals Inc. - Product / Service
Alnylam Pharmaceuticals Inc. - Key offerings
SWOT

16.6 Arcturus Therapeutics Holdings

Arcturus Therapeutics Holdings - Overview
Arcturus Therapeutics Holdings - Product / Service
Arcturus Therapeutics Holdings - Key offerings
SWOT

16.7 Avidity Biosciences Inc.

Avidity Biosciences Inc. - Overview
Avidity Biosciences Inc. - Product / Service
Avidity Biosciences Inc. - Key offerings
SWOT

16.8 BioNTech SE

BioNTech SE - Overview
BioNTech SE - Product / Service
BioNTech SE - Key offerings
SWOT

16.9 Eli Lilly and Co.

Eli Lilly and Co. - Overview
Eli Lilly and Co. - Product / Service
Eli Lilly and Co. - Key news
Eli Lilly and Co. - Key offerings
SWOT

16.10 Ionis Pharmaceuticals Inc.

Ionis Pharmaceuticals Inc. - Overview
Ionis Pharmaceuticals Inc. - Product / Service
Ionis Pharmaceuticals Inc. - Key offerings
SWOT

16.11 Moderna Inc.

Moderna Inc. - Overview
Moderna Inc. - Product / Service
Moderna Inc. - Key offerings
SWOT

16.12 Novartis AG

Novartis AG - Overview
Novartis AG - Business segments
Novartis AG - Key news
Novartis AG - Key offerings
Novartis AG - Segment focus
SWOT

16.13 ProQR Therapeutics

ProQR Therapeutics - Overview
ProQR Therapeutics - Product / Service
ProQR Therapeutics - Key offerings
SWOT

16.14 Sail Biomedicines Inc.

Sail Biomedicines Inc. - Overview
Sail Biomedicines Inc. - Product / Service
Sail Biomedicines Inc. - Key offerings
SWOT

16.15 Sarepta Therapeutics Inc.

Sarepta Therapeutics Inc. - Overview
Sarepta Therapeutics Inc. - Product / Service
Sarepta Therapeutics Inc. - Key offerings
SWOT

16.16 ShapeTX

ShapeTX - Overview
ShapeTX - Product / Service
ShapeTX - Key offerings
SWOT

16.17 Stoke Therapeutics Inc.

Stoke Therapeutics Inc. - Overview
Stoke Therapeutics Inc. - Product / Service
Stoke Therapeutics Inc. - Key offerings
SWOT

16.18 Wave Life Sciences Ltd.

Wave Life Sciences Ltd. - Overview
Wave Life Sciences Ltd. - Product / Service
Wave Life Sciences Ltd. - Key offerings
SWOT

17. Appendix

17.1 Scope of the report

Market definition
Objectives
Notes and caveats

17.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

17.3 Currency conversion rates for US$

17.4 Research methodology

17.5 Data procurement

Information sources

17.6 Data validation

17.7 Validation techniques employed for market sizing

17.8 Data synthesis

17.9 360 degree market analysis

17.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Rna Based Therapeutics market growth will increase by USD 1420.7 million during 2026-2030.

The Rna Based Therapeutics market is expected to grow at a CAGR of 5.6% during 2026-2030.

Rna Based Therapeutics market is segmented by Type (mRNA therapeutics, Antisense oligonucleotide (ASO) therapeutics, RNA interference (RNAi) therapeutics, Others) Route of administration (Intravenous (IV), Subcutaneous (SC), Intramuscular (IM)) Application (Oncology, Infectious diseases, Genetic disorders, Others) Product type (Vaccines, Drugs)

Abogen Biosciences, Alnylam Pharmaceuticals Inc., Arcturus Therapeutics Holdings, Arrowhead Pharmaceuticals Inc., Avidity Biosciences Inc., BioNTech SE, Eli Lilly and Co., Ionis Pharmaceuticals Inc., Moderna Inc., Novartis AG, ProQR Therapeutics, ReCode Therapeutics, Sail Biomedicines Inc., Sarepta Therapeutics Inc., ShapeTX, Stoke Therapeutics Inc., Strand Therapeutics Inc., Wave Life Sciences Ltd. are a few of the key vendors in the Rna Based Therapeutics market.

Europe will register the highest growth rate of 38.9% among the other regions. Therefore, the Rna Based Therapeutics market in Europe is expected to garner significant business opportunities for the vendors during the forecast period.

Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, China, Japan, India, South Korea, Singapore, Taiwan, Brazil, Australia, Israel, Saudi Arabia, UAE, South Africa, Argentina, Turkey

  • Expansion of clinical pipeline applications is the driving factor this market.

The Rna Based Therapeutics market vendors should focus on grabbing business opportunities from the Type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA
