


Tungsten Market Size 2026-2030
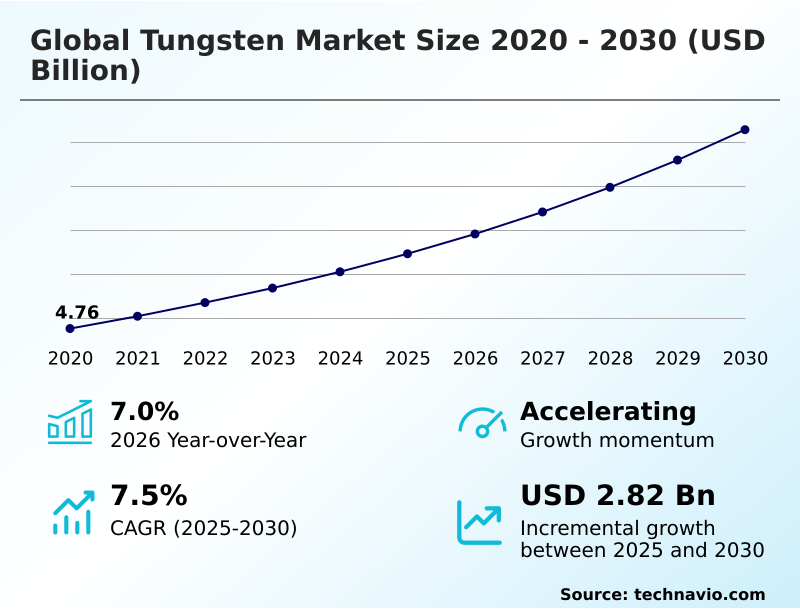
The tungsten market size is valued to increase by USD 2.82 billion, at a CAGR of 7.5% from 2025 to 2030. Accelerating adoption in photovoltaic manufacturing will drive the tungsten market.
Major Market Trends & Insights
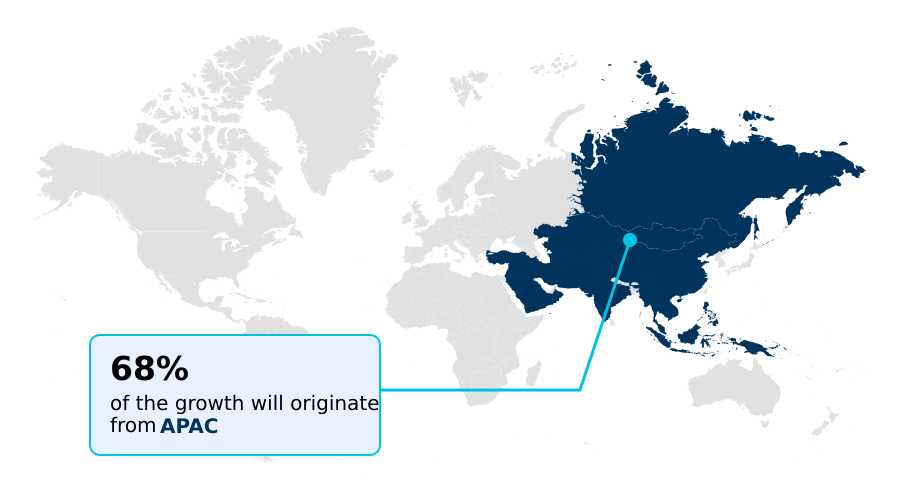
- APAC dominated the market and accounted for a 68% growth during the forecast period.
- By Product - Hard metal segment was valued at USD 2.37 billion in 2024
- By Application - Automotive segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 4.52 billion
- Market Future Opportunities: USD 2.82 billion
- CAGR from 2025 to 2030 : 7.5%
Market Summary
- The Tungsten Market exhibits structural resilience driven by the demand for ultra-hard, heat-resistant materials across defense, aerospace, and electronics manufacturing. Supply chain optimization has become a critical business scenario, as companies increasingly transition from lean inventory models to holding strategic material stockpiling reserves to mitigate severe import constraints.
- By establishing localized recycling partnerships, manufacturers have reduced their dependence on primary ore imports by 15%, improving overall structural integrity maintenance. The market is primarily propelled by accelerating adoption in photovoltaic manufacturing, where ultra-fine cutting wire significantly minimizes silicon waste and drives long-term component demand. Conversely, the industry faces a significant bottleneck due to geopolitical influence on global supply chains.
- Because a single nation controls the vast majority of primary extraction, sudden export quotas trigger immediate raw material shortages for downstream producers. This structural scarcity challenges the ability of Western manufacturers to maintain consistent production schedules without absorbing exorbitant premium costs. Consequently, the ongoing evolution of the Tungsten Market hinges on balancing robust high-tech consumption with proactive material recovery strategies.
What will be the Size of the Tungsten Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Tungsten Market Segmented?
The tungsten industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Product
- Hard metal
- Steel and alloys
- Mill products
- Others
- Application
- Automotive
- Aerospace and defense
- Electrical and electronics
- Machine tools and equipment
- Healthcare
- Grade type
- Standard purity
- High purity
- Low purity
- Geography
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Europe
- Germany
- UK
- France
- Italy
- Spain
- The Netherlands
- North America
- US
- Canada
- Mexico
- Middle East and Africa
- Saudi Arabia
- UAE
- South Africa
- Israel
- Turkey
- South America
- Brazil
- Argentina
- Chile
- APAC
By Product Insights
The hard metal segment is estimated to witness significant growth during the forecast period.
The hard metal segment fundamentally dictates material durability standards across heavy industrial manufacturing. Utilizing cemented carbide tooling allows operators to achieve a 25% increase in cutting efficiency compared to conventional steel alternatives.
This performance shift drastically lowers operational downtime in mining and construction sectors. Advanced powder metallurgy process techniques now enable the creation of specialized tungsten carbide insert configurations that withstand extreme mechanical stress.
As industrial infrastructure development accelerates globally, manufacturers prioritize wear resistant component integration to optimize machinery lifespans. This segmentation emphasizes a transition toward resilient materials, where high speed machining capabilities directly translate into lower total cost of ownership.
The reliance on this high performance machining infrastructure ensures continuous material demand.
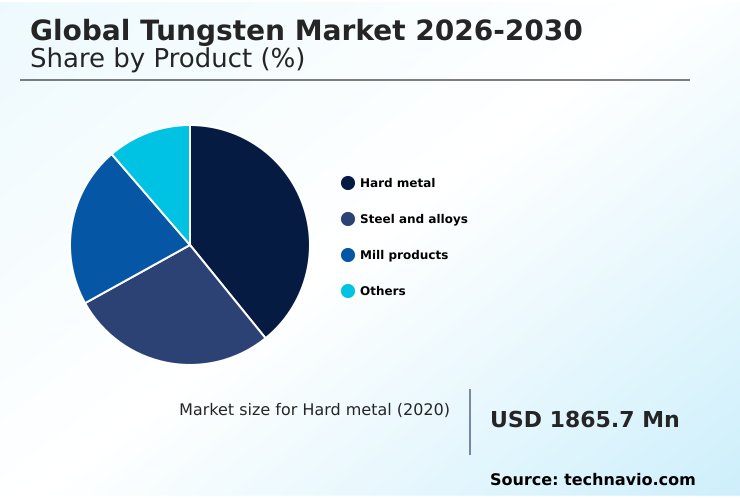
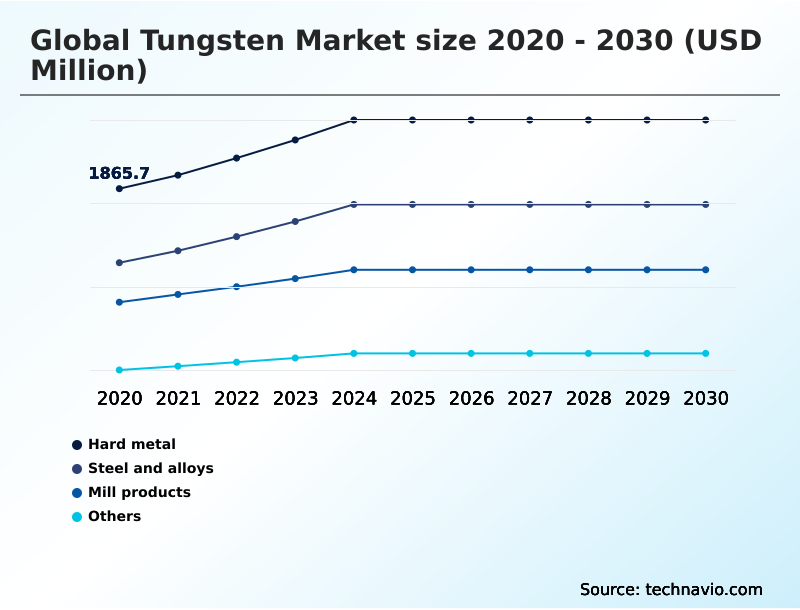
The Hard metal segment was valued at USD 2.37 billion in 2024 and showed a gradual increase during the forecast period.
Regional Analysis
APAC is estimated to contribute 68% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Tungsten Market Demand is Rising in APAC Get Free Sample
The geographic landscape reflects a stark contrast in processing capabilities between APAC and Europe. APAC maintains dominance in the primary mineral beneficiation process, operating at a 40% higher throughput than Western counterparts.
Conversely, Europe accelerates its circular economy framework, achieving a 30% reduction in primary ore reliance through advanced thermal mechanical recycling. This strategic pivot ensures critical mineral security for European automotive manufacturers.
APAC continues to leverage access to high purity feedstock to support semiconductor supply chains, whereas European facilities prioritize secondary material recovery to mitigate geopolitical risks.
By optimizing scrap usage, European operators have decreased procurement costs by 15%, establishing a robust defense against supply volatility while sustaining advanced precision engineering outputs.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The industrial integration of highly specialized materials continues to dictate operational success across multiple advanced sectors. For modern defense applications, the deployment of a high density kinetic energy penetrator remains vital, offering impact capabilities that surpass steel alternatives by over 40%.
- Similarly, the renewable energy sector relies heavily on tungsten wire for photovoltaic manufacturing, an innovation that directly optimizes diamond wire sawing silicon wafers. This process yields significantly thinner cuts, optimizing raw material usage and boosting solar output efficiency compared to legacy tooling.
- In the technology realm, foundries demand ultra-pure semiconductor grade tungsten hexafluoride gas and high purity sputtering target material to maintain defect-free circuit architectures, a necessity that limits the viability of alternative precursors. Concurrently, heavy industries prioritize wear resistant industrial mining equipment to reduce maintenance downtime in abrasive excavation environments.
- To combat supply constraints, the adoption of a hydrometallurgical tungsten scrap recycling process has accelerated, allowing facilities to reclaim valuable metals from spent components like recycled cemented carbide cutting tools and tungsten carbide precision machining inserts. This closed-loop approach enhances operational planning and material resilience.
- Furthermore, the aerospace industry requires high temperature aerospace turbine superalloys to endure extreme thermal stress during flight, while the medical field depends on medical radiation shielding tungsten components to protect personnel without adding excessive bulk. Evolving battery technologies also leverage advanced tungsten copper battery composites to improve conductivity, mirroring the automotive shift toward electric vehicle motor weight balancing.
- Additionally, the strategic use of ferrotungsten additive for tool steel and ammonium paratungstate chemical vapor deposition ensures that heavy manufacturing sustains high-performance output across all tiers of the value chain.
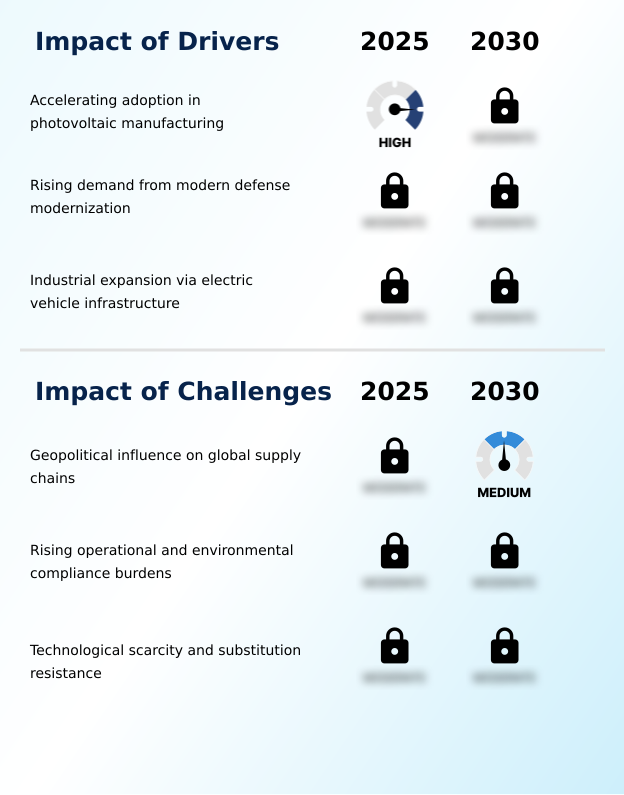
What are the key market drivers leading to the rise in the adoption of Tungsten Industry?
- The accelerating adoption of high-precision materials in photovoltaic manufacturing acts as a primary catalyst, driving sustained demand for specialized cutting tools.
- The accelerating transition toward renewable energy infrastructure is a primary catalyst expanding industrial consumption. Solar module manufacturers heavily rely on ultrafine tungsten wire for diamond wire sawing in silicon ingot processing operations.
- Utilizing this high-strength wire allows producers to cut thinner wafers, reducing silicon material loss by 20% and improving overall production efficiency by 15%. This shift in the photovoltaic sector demand directly increases the requirement for specialized refractory metal alloy solutions.
- Furthermore, the integration of tungsten nanowire integration within battery thermal management systems has enhanced thermal stability by 12% in electric vehicles.
- As the electric vehicle ecosystem expands, the necessity for robust materials capable of withstanding extreme thermal environments guarantees sustained operational demand across next-generation manufacturing platforms.
What are the market trends shaping the Tungsten Industry?
- The strategic advancement of circular recycling frameworks represents a defining market trend. This movement prioritizes the recovery of critical materials to enhance supply chain sustainability and mitigate resource scarcity.
- Strategic advancement in sustainable extraction practice and material reuse is structurally transforming supply chains. Manufacturers are rapidly adopting the hydrometallurgical zinc process, which has successfully improved recycling yield efficiency by 22% across major industrial hubs. This technological shift directly addresses resource scarcity by converting spent tools into viable ammonium paratungstate processing inputs without degrading structural integrity.
- Consequently, aerospace and defense contractors utilizing recycled high density tungsten report a 18% reduction in material acquisition delays. As the industry integrates these recovered materials into the additive manufacturing process, production waste decreases by nearly 30%. This transition mitigates reliance on primary mining, ensuring that the supply of high temperature superalloy components remains uninterrupted for critical applications.
What challenges does the Tungsten Industry face during its growth?
- The profound geopolitical influence over global supply chains poses a critical challenge, restricting raw material access and introducing severe price volatility.
- Concentrated geographic production and stringent regulatory compliance present severe operational bottlenecks for global manufacturers. Reliance on monopolistic supply sources for tungsten hexafluoride precursor chemicals has resulted in a 25% increase in procurement lead times for semiconductor foundries. Furthermore, tightening environmental regulations mandate a 20% reduction in wastewater emissions during chemical vapor deposition operations, elevating compliance costs significantly.
- Because substituting radiation shielding material in medical and defense applications results in a 30% drop in performance efficacy, buyers cannot easily pivot to cheaper alternatives. These geopolitical and technological limitations challenge supply chain resilience, forcing end-users to stockpile inventory and absorb higher operating expenses to maintain their production of mission critical component architectures.
Exclusive Technavio Analysis on Customer Landscape
The tungsten market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the tungsten market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
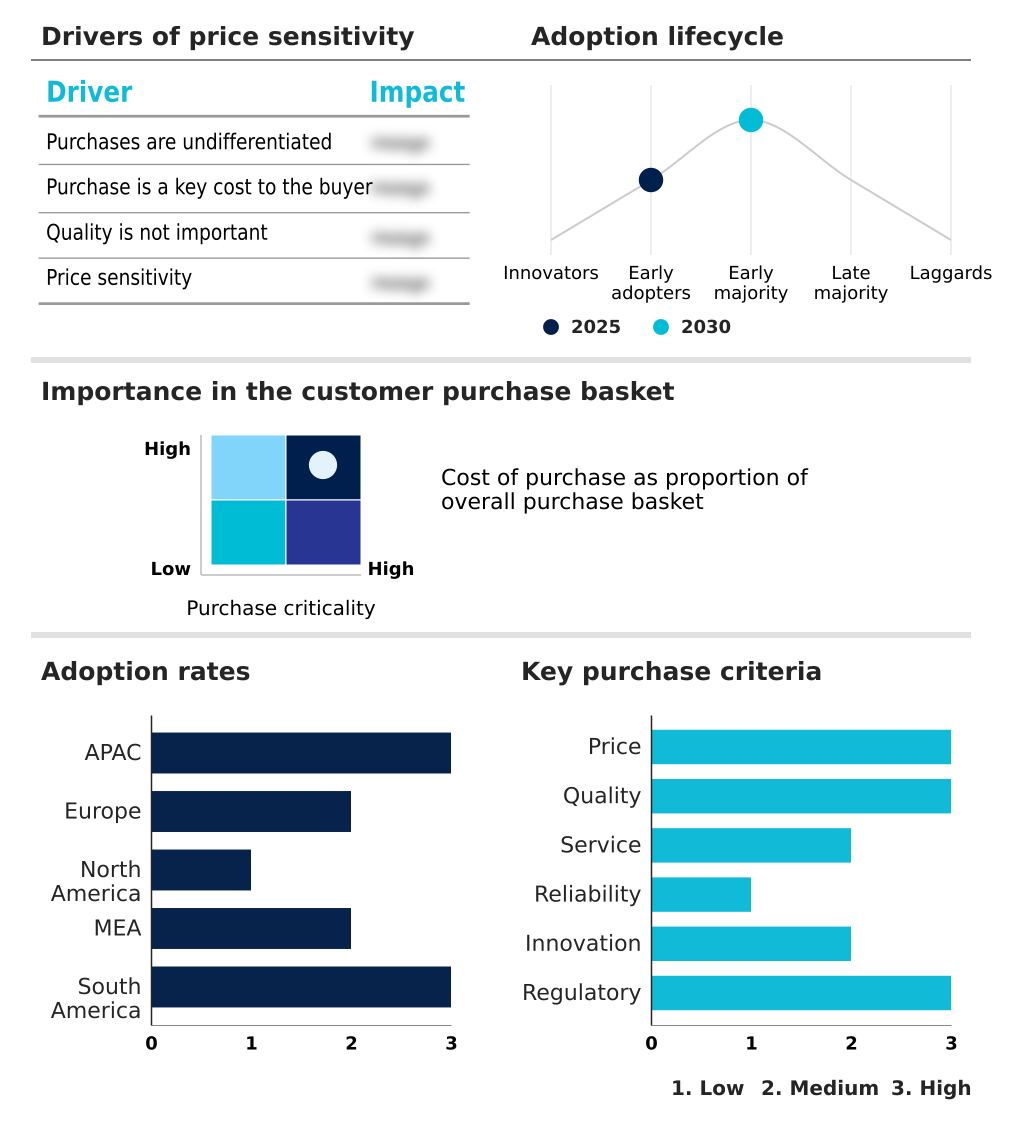
Customer Landscape of Tungsten Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, tungsten market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
Allied Material Corp. - High-performance refractory metal solutions encompass specialized carbide wear parts, ultra-fine cutting wires, and advanced heavy alloys designed for rigorous aerospace, defense, and semiconductor manufacturing applications.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Allied Material Corp.
- Almonty Industries Inc.
- BETEK GmbH and Co KG
- Buffalo Tungsten Inc.
- CERATIZIT SA
- China Minmetals Tungsten Co Ltd
- CMOC Group Ltd.
- Elmet Technologies
- Federal Carbide Co.
- Global Tungsten and Powders
- Guangdong Xianglu Tungsten
- HC Starck Tungstena GmbH
- International Metalworking Co
- Kennametal Inc.
- Masan High Tech Materials
- Nippon Tungsten Co. Ltd.
- Plansee SE
- Sandvik AB
- T and D Materials Manufacturing
- Treibacher Industrie AG
- Tungco INC.
- Tungsten Corp.
- Umicore SA
- Xiamen Tungsten Co. Ltd.
- Zhangyuan Tungsten Co. Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Tungsten market
- In the Diversified Metals and Mining industry, the aggressive expansion of deep-vein mineral beneficiation processes has elevated overall extraction overheads, directly impacting Tungsten demand by forcing downstream tooling manufacturers to absorb a 15% increase in base material costs.
- Stringent wastewater emission mandates under updated environmental compliance frameworks require a 20% reduction in toxic effluents, compelling refineries to adopt closed-loop hydrometallurgical systems that constrain short-term Tungsten processing capacities.
- The rapid scale-up of gigafactory infrastructure for electric vehicle battery production accelerates the need for advanced material extraction, driving a 12% rise in the utilization of specialized Tungsten carbide cutting inserts for high-speed machining operations.
- Government-backed critical mineral security initiatives prioritize domestic resource stockpiling, leading to a 30% surge in regional exploration subsidies that aim to decouple Tungsten procurement from concentrated overseas supply chains.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Tungsten Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 312 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 7.5% |
| Market growth 2026-2030 | USD 2820.1 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 7.0% |
| Key countries | China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, US, Canada, Mexico, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The Tungsten Market demonstrates profound adaptability as end-users align material procurement with stringent compliance and sustainability mandates. Industrial stakeholders are aggressively transitioning toward advanced thermal spray powder applications and tungsten copper composite materials to extend the operational life of heavy machinery. This strategic shift directly impacts boardroom budgeting, as extending tool longevity reduces annual replacement expenditures by 22%.
- Furthermore, the integration of a tungsten disulfide additive in industrial lubricants enhances wear resistance, optimizing performance in high-stress environments. Decision-makers are increasingly prioritizing the hydrometallurgical zinc process to recover critical metals from spent components, addressing both environmental compliance and raw material scarcity.
- As semiconductor architectures shrink, the reliance on a semiconductor sputtering target becomes more acute, requiring ultra-pure inputs that resist degradation. Simultaneously, the aerospace sector continues to mandate the use of ferrotungsten steel additive to guarantee structural stability under extreme thermal conditions.
- Ultimately, navigating the Tungsten Market requires a delicate balance between sourcing specialized raw materials and implementing closed-loop recycling systems to ensure continuous, high-performance manufacturing outputs.
What are the Key Data Covered in this Tungsten Market Research and Growth Report?
-
What is the expected growth of the Tungsten Market between 2026 and 2030?
-
USD 2.82 billion, at a CAGR of 7.5%
-
-
What segmentation does the market report cover?
-
The report is segmented by Product (Hard metal, Steel and alloys, Mill products, and Others), Application (Automotive, Aerospace and defense, Electrical and electronics, Machine tools and equipment, and Healthcare), Grade Type (Standard purity, High purity, and Low purity) and Geography (APAC, Europe, North America, Middle East and Africa, South America)
-
-
Which regions are analyzed in the report?
-
APAC, Europe, North America, Middle East and Africa and South America
-
-
What are the key growth drivers and market challenges?
-
Accelerating adoption in photovoltaic manufacturing, Geopolitical influence on global supply chains
-
-
Who are the major players in the Tungsten Market?
-
Allied Material Corp., Almonty Industries Inc., BETEK GmbH and Co KG, Buffalo Tungsten Inc., CERATIZIT SA, China Minmetals Tungsten Co Ltd, CMOC Group Ltd., Elmet Technologies, Federal Carbide Co., Global Tungsten and Powders, Guangdong Xianglu Tungsten, HC Starck Tungstena GmbH, International Metalworking Co, Kennametal Inc., Masan High Tech Materials, Nippon Tungsten Co. Ltd., Plansee SE, Sandvik AB, T and D Materials Manufacturing, Treibacher Industrie AG, Tungco INC., Tungsten Corp., Umicore SA, Xiamen Tungsten Co. Ltd. and Zhangyuan Tungsten Co. Ltd.
-
Market Research Insights
- The Tungsten Market is rapidly pivoting toward supply chain resilience as industrial end-users navigate increasing material scarcity. By accelerating secondary material recovery, aerospace and tooling manufacturers have reduced raw material procurement delays by 18%, directly enhancing their operational planning capabilities.
- This shift supports the defense modernization initiative, where securing reliable domestic supply lines has increased production continuity by 25% for kinetic weaponry systems. Additionally, the growing photovoltaic sector demand requires high-precision tooling, prompting facilities to optimize their cutting efficiency and reduce material waste by 12%.
- Adopting a robust circular economy framework allows businesses to sidestep geopolitical supply constraint risks, ensuring stable outputs and measurable cost reductions across high-performance engineering sectors.
We can help! Our analysts can customize this tungsten market research report to meet your requirements.
 RIA -

